
The ritual of checking the Powerball numbers is a unique intersection of hope, probability, and financial fantasy. For millions of Americans, that moment when the white balls tumble and the red Powerball settles into place represents more than just a game; it represents a potential pivot point in their financial lives. Whether you are checking your ticket against the latest draw or analyzing the trends of past winners, understanding the mechanics of these numbers is the first step in a much larger journey involving wealth management, tax strategy, and personal finance.
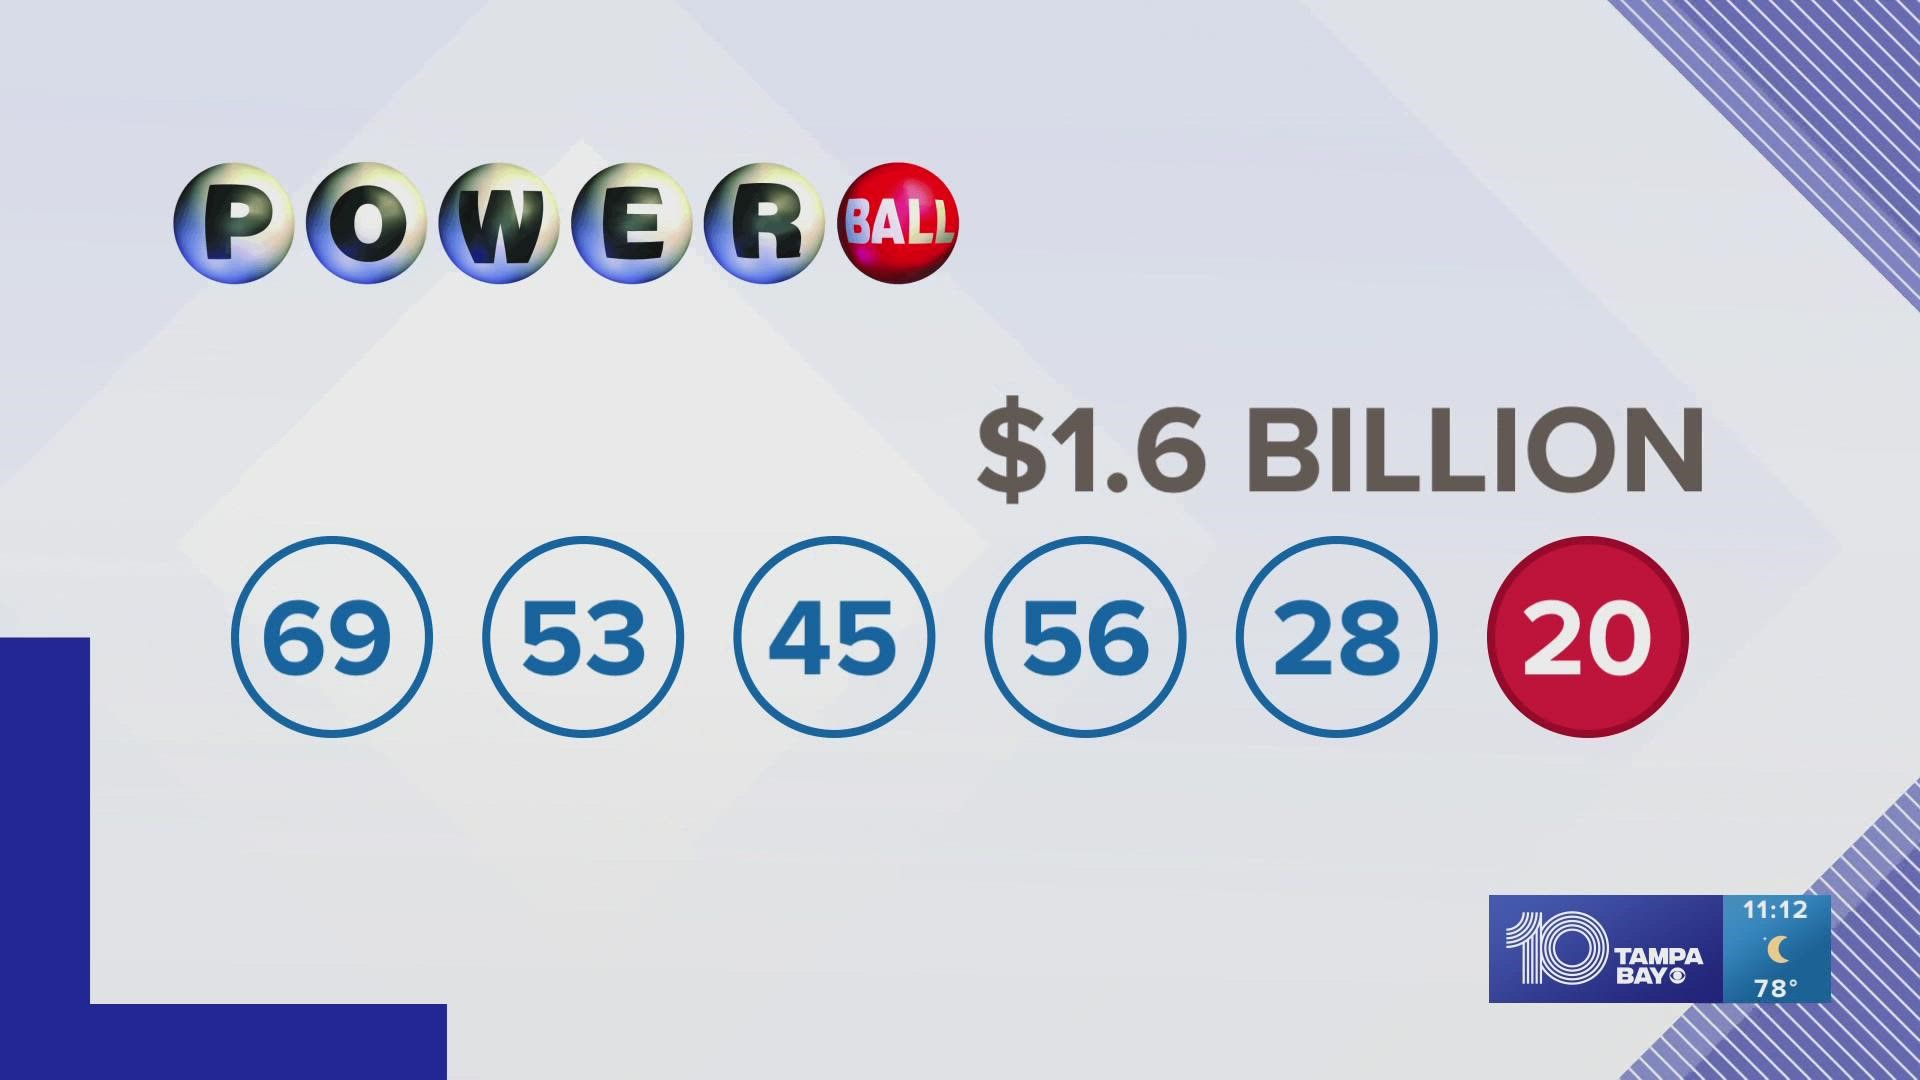
While the immediate query is often centered on the digits themselves, the broader financial implications of those numbers are where the true complexity lies. Winning a major jackpot is less about “hitting it big” and more about the sudden acquisition of a massive, complex asset that requires sophisticated handling.
Understanding the Financial Mechanics of Major Jackpots
When you check the numbers and find a match, you aren’t just winning a pile of cash; you are entering into a legal and financial contract with the Multi-State Lottery Association (MUSL). The headline figure you see on billboards—the $500 million, $1 billion, or $2 billion marks—is a projection of an annuity, not a liquid bank balance.
Cash Option vs. Annuity: The Long-Term Math
One of the first and most critical financial decisions a winner must make is choosing between the lump-sum cash option and the 30-payment annuity.
The cash option is the actual amount of liquid cash the lottery has on hand from ticket sales to fund the jackpot. It is typically significantly lower than the advertised jackpot, often hovering around 50% to 60% of the headline figure. From a professional financial perspective, the cash option is frequently preferred by those who believe they can achieve a higher rate of return through private investment than the lottery’s internal treasury yields. By taking the cash upfront, an investor gains control over the capital, allowing for immediate diversification into equities, real estate, and fixed-income assets.
Conversely, the annuity option offers a structured series of payments that increase by 5% each year. This is often described as “winning-proof” because it prevents a winner from spending the entire windfall in a short period. For those without a background in disciplined capital management, the annuity acts as a forced budget, ensuring a high standard of living for three decades.
The Tax Man Cometh: Calculating Your Net Winnings
Before you begin allocating your theoretical millions, it is vital to understand the tax liabilities associated with those winning numbers. The IRS views lottery winnings as ordinary income.
As soon as you claim a prize over $5,000, the lottery commission is required to withhold 24% for federal taxes. However, since the top federal income tax bracket is 37%, you will likely owe an additional 13% when you file your return the following year. Furthermore, state taxes vary wildly. If you live in a state like California or Florida, you may face no state tax on lottery winnings. However, in states like New York or New Jersey, you could see another 8% to 10% carved out of your prize.
When you account for both federal and state liabilities, a winner should generally expect to lose approximately 45% to 50% of the total cash value to the government before the first dollar is spent.
The Strategic Approach to Sudden Wealth Management
Finding out that you held the winning numbers is a high-stress event known as “Sudden Wealth Syndrome.” The psychological impact of transitioning from a standard income to an ultra-high-net-worth individual can lead to impulsive decision-making. A strategic, professional approach is required to ensure that the windfall lasts for generations rather than years.
Building Your Financial Dream Team
No individual should attempt to manage a Powerball-sized fortune alone. The moment those winning numbers are confirmed, your priority shifts from “checking tickets” to “assembling a board of directors.”
A comprehensive financial team typically includes:
- A Tax Attorney: To navigate the complex filing requirements and structure the claim to minimize tax leakage.
- A Certified Financial Planner (CFP): To create a long-term investment strategy and sustainable withdrawal rate.
- A CPA: To handle the immediate tax payments and ongoing accounting for new investments.
- An Estate Attorney: To set up trusts and protect the assets from future litigation or probate issues.
The goal of this team is to create a barrier between the winner and the capital. By the time the check is deposited, a sophisticated structure—often involving blind trusts or limited liability companies (LLCs)—should be in place to receive the funds.
Protecting Your Privacy and Assets
In many states, lottery winners are public record. This exposure can lead to a deluge of requests from “long-lost” relatives, fraudulent charities, and unscrupulous investment “opportunities.” Protecting your identity is a financial security measure.
In states that allow it, claiming the prize through a trust can keep your name out of the headlines. This level of anonymity is essential for maintaining a sense of normalcy and preventing the social pressures that often lead winners to bankruptcy. Asset protection also involves insurance; a sudden increase in net worth makes you a target for lawsuits. Implementing high-limit umbrella insurance policies is a standard move for any lottery winner looking to safeguard their new financial status.
Lottery vs. Conventional Investing: A Risk-Reward Analysis
While checking the winning numbers tonight is a form of entertainment, it is important to contrast the “lottery strategy” with traditional wealth-building mechanisms. The Powerball is, statistically speaking, an outlier event, whereas compound interest in a diversified portfolio is a historical reliability.
The Opportunity Cost of the Ticket
The odds of winning the Powerball jackpot are approximately 1 in 292.2 million. To put this in financial perspective, you are far more likely to become a billionaire through entrepreneurship or disciplined investing than through a lottery ticket.
If an individual spends $10 a week on Powerball tickets starting at age 20, they will have spent approximately $23,400 by age 65. If that same $40 per month had been invested in an S&P 500 index fund with an average annual return of 7%, it would grow to roughly $150,000. While $150,000 isn’t a billion-dollar jackpot, it is a guaranteed financial cushion built on the power of time and compounding, rather than the near-zero probability of a random draw.
Diversification and the “Found Money” Fallacy
Psychologically, people treat “found money”—like a lottery win or a tax refund—differently than “earned money.” This is known as mental accounting. Winners often take far more risks with their jackpot than they would with their hard-earned salary.
A professional financial approach dictates that once the winning numbers have been validated and the cash is in hand, that money must be treated with the same (or more) reverence as earned income. This means diversifying away from “get rich quick” schemes. A winner’s portfolio should be a balanced mix of low-cost index funds, municipal bonds for tax-free income, and perhaps a small allocation for “passion investments” like real estate or venture capital. The objective shifts from “wealth creation” to “wealth preservation.”
Navigating the Emotional and Psychological Impact of a Windfall
The financial world is littered with stories of lottery winners who ended up in worse positions than they started. This phenomenon, often called the “Lottery Curse,” is rarely about the numbers themselves and almost always about the lack of a financial framework.
Avoiding Lifestyle Creep
The most common pitfall after matching those winning numbers is immediate, massive lifestyle inflation. Buying a fleet of luxury cars, a private jet, or a 20-bedroom mansion creates an enormous “burn rate.” These assets have high carrying costs—maintenance, insurance, property taxes, and staffing.
Financial advisors recommend a “cooling-off period” of six months to a year before making any major purchases. This allows the winner to adjust to their new reality without depleting the principal of their investment. By living off the interest generated by the win rather than the win itself, a winner can enjoy a high-end lifestyle indefinitely.

Philanthropy and Legacy Planning
For many, the ultimate goal of seeing their numbers called is the ability to help others. However, unchecked giving can be a faster path to ruin than luxury spending.
Strategic philanthropy involves setting up a private foundation or a donor-advised fund (DAF). These vehicles allow the winner to take a tax deduction upfront while distributing the money to charities over many years. This ensures that the generosity is sustainable and that the winner isn’t simply writing checks until the account is empty. Legacy planning also involves setting up generational trusts that provide for children and grandchildren with specific “incentive clauses” (such as requiring a college degree) to ensure the wealth remains a blessing rather than a burden.
Checking the winning numbers for the Powerball is the beginning of a complex financial narrative. While the odds are slim, the exercise highlights the importance of financial literacy, the reality of taxation, and the necessity of long-term planning. Whether those numbers match your ticket tonight or not, the principles of managing large sums of money remain the same: prioritize protection, understand your liabilities, and always invest with a vision that extends far beyond the next drawing.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.