
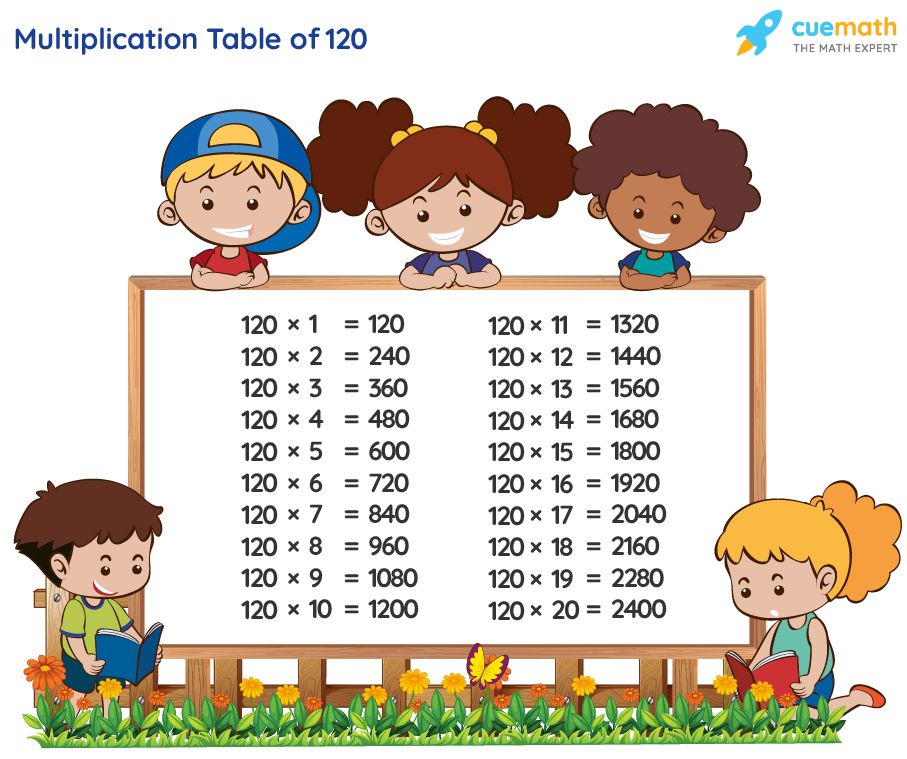
In the realm of mathematics, the question “what times what equals 120” has several straightforward answers: 10 times 12, 5 times 24, or perhaps 3 times 40. However, when we transition from the chalkboard to the balance sheet, this equation takes on a far more profound meaning. In personal finance, business scaling, and investment strategy, “120” is rarely just a product of two integers. Instead, it represents a milestone—a target revenue, a percentage of return, or a strategic allocation ratio that defines the trajectory of one’s financial future.
To understand the multipliers of wealth, one must look past basic arithmetic and into the mechanics of financial leverage, compounding interest, and revenue modeling. Whether you are attempting to scale a business to $120,000 in annual recurring revenue or seeking to understand the “Rule of 120” in portfolio management, the goal remains the same: identifying the variables that, when multiplied, produce exponential growth.
The Mathematics of Wealth Accumulation
At its core, wealth creation is a multiplication problem. Every financial success story is built upon a fundamental equation: Capital multiplied by Rate of Return over Time. If your target is 120—representing a 120% return on investment or a 12x multiple on a seed project—you must manipulate these variables with precision.
Understanding the Variable Equation
In the world of investing, the “what times what” refers to the synergy between your principal investment and your yield. To reach a total value of 120 starting from a base of 1, you require a massive multiplier. This is often achieved through high-growth assets or long-term compounding.
The formula $A = P(1 + r/n)^{nt}$ is the sophisticated version of our simple multiplication. Here, the “multipliers” are the interest rate and the frequency of compounding. For an investor, the quest for “120” often manifests in the search for “multi-baggers”—stocks or assets that return several times their original value. Finding a “10-bagger” (a 1000% return) is the ultimate goal, but even consistent, smaller multipliers, when applied to a growing base, can reach that 120 milestone through the sheer force of persistence.
The Power of Compounding as a Force Multiplier
Albert Einstein famously referred to compound interest as the eighth wonder of the world. In our context, compounding is the “hidden” multiplier. When you earn a return on your investment, and then earn a return on those returns, you are no longer adding; you are multiplying.
If you have $10,000 and you achieve a 12% annual return, you aren’t just adding $1,200 every year. By the second year, you are multiplying 12% against $11,200. This geometric progression is what allows small, consistent inputs to eventually equal massive outputs. The “what times what” in this scenario is your discipline multiplied by the passage of time.
Scaling to $120,000: The Strategic Revenue Formula
For entrepreneurs and side-hustlers, 120 is a “magic number.” An annual income of $120,000 breaks down to a clean $10,000 per month. This is often the threshold where a business moves from a “hobby” or a “job” to a scalable enterprise. Achieving this requires a clear understanding of your revenue multipliers.
High-Volume, Low-Margin vs. Low-Volume, High-Ticket
When trying to reach $120,000 in revenue, you have several mathematical paths. You must decide which “what times what” fits your business model:
- The Mass Market Model: 1,200 customers × $100 product = $120,000.
- The Mid-Tier Model: 120 clients × $1,000 service = $120,000.
- The High-Ticket Model: 12 clients × $10,000 premium consulting = $120,000.
- The Continuity Model: 1,000 subscribers × $10/month × 12 months = $120,000.
Each of these equations requires a different set of skills. The high-volume model requires a multiplier in the form of marketing reach and automated systems. The high-ticket model requires a multiplier in the form of deep expertise and high-touch sales strategies. Understanding which equation you are solving for is the first step in avoiding “entrepreneurial burnout,” where you try to apply high-touch effort to a low-price product, effectively killing your multiplier.
Breaking Down the Monthly Milestones
The psychological power of “120” lies in its divisibility. Because 120 is a highly composite number, it is easy to break down into manageable milestones. $10,000 a month is the primary target, but that further breaks down to approximately $333 per day.

In business finance, this allows for precise “unit economics.” If you know that every $1 spent on advertising results in $3 in sales, your multiplier is 3x. To reach your $120,000 goal, you simply need to find a way to scale your input (ad spend) while maintaining that 3x multiplier. This is where many businesses fail; they assume the multiplier is static, whereas, in reality, multipliers often diminish as volume increases.
The Rule of 120 in Modern Portfolio Theory
In the specific niche of asset allocation, “120” is a cornerstone of modern financial planning. For decades, the “Rule of 100” suggested that investors should subtract their age from 100 to determine the percentage of their portfolio that should be invested in equities (stocks), with the remainder in bonds. However, as life expectancies have increased and interest rates have fluctuated, many financial advisors have updated this to the Rule of 120.
Asset Allocation: The Age-Based Formula
The Rule of 120 is a calculation used to balance risk and reward over a lifetime. If you are 30 years old, the equation is $120 – 30 = 90$. This suggests that 90% of your portfolio should be in stocks to maximize growth, while 10% should be in safer assets like bonds or cash.
As you age, the “what times what” of your portfolio shifts. At age 60, the equation becomes $120 – 60 = 60$. You move toward a 60/40 split. This rule recognizes that in the modern economy, “inflation” is a negative multiplier. To combat the eroding power of inflation over a 30-year retirement, investors need the higher growth multipliers found in the equity markets for a longer period.
Risk Management and the Search for Multi-Baggers
Within that equity allocation, investors often look for the “120” factor in terms of total return. In a diversified portfolio, most assets will provide steady, linear growth. However, the overall performance of the portfolio is often driven by a few “outliers.”
This is the Pareto Principle (the 80/20 rule) applied to finance. Often, 20% of your investments will produce 80% of your returns. Identifying the “multipliers” in your portfolio—those companies with high moat, scalable software, or disruptive technology—is how you move the needle. When one “what” (your investment) meets the right “what” (market demand), the result is the 120% or 1200% return that secures financial independence.
Leveraging Operational Efficiency in Business Finance
In business finance, “what times what” often refers to the relationship between Input and Output. This is defined as Productivity or Return on Assets (ROA). If a business has $120,000 in assets, how efficiently is it multiplying those assets to create profit?
Input vs. Output: The ROI Equation
Return on Investment (ROI) is the ultimate multiplier. If you invest $40 into a process and it yields $120, you have a 3x multiplier (or a 200% ROI). In a corporate setting, financial officers look for ways to increase this multiplier without increasing the risk profile.
This can be achieved through:
- Operating Leverage: Using fixed costs to increase the impact of each additional sale. Once your overhead is covered, every additional dollar of revenue has a much higher multiplier on your net profit.
- Financial Leverage: Using borrowed capital (debt) to increase the potential return on equity. While dangerous if mismanaged, debt is a “force multiplier” that can turn a 10% return on an asset into a 50% return on the cash you personally invested.
Automation as a Scalability Multiplier
In the modern digital economy, the most potent multiplier is no longer just capital or labor; it is code and media. If you write an ebook or develop a software tool, the cost of replication is near zero.
The “what times what” here is your initial creative effort multiplied by an infinite number of digital transactions. This is how a single individual can generate $120,000 in profit with almost no overhead. By removing the “human” variable from the delivery equation, the multiplier becomes virtually limitless. This shift from linear income (trading hours for dollars) to exponential income (trading value for scaled returns) is the hallmark of modern wealth building.
Conclusion: Solving Your Own 120 Equation
Whether you are looking at the Rule of 120 for your retirement plan, aiming for a $120k side hustle, or seeking a 120% return on a high-growth investment, the lesson is clear: financial success is determined by the multipliers you choose to employ.
Math is an impartial judge. It tells us that to reach 120, we can work very hard for a long time (120 x 1), or we can find powerful levers that do the work for us (12 x 10). The most successful individuals in the world of money are those who stop focusing solely on the “addition” of their savings and start focusing on the “multiplication” of their assets. By identifying the right variables—time, compound interest, leverage, and scalability—you can solve the equation of “what times what” and secure your financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.