
When building a comprehensive personal or business financial plan, insurance stands as one of the most critical pillars of risk management. For those living in the Mid-Atlantic and Great Lakes regions, Erie Insurance often surfaces as a top-tier contender for asset protection. However, unlike national giants that blanket all fifty states, Erie Insurance operates with a deliberate, regional strategy. Understanding exactly where Erie operates and how their localized model impacts your financial bottom line is essential for any savvy consumer or business owner.
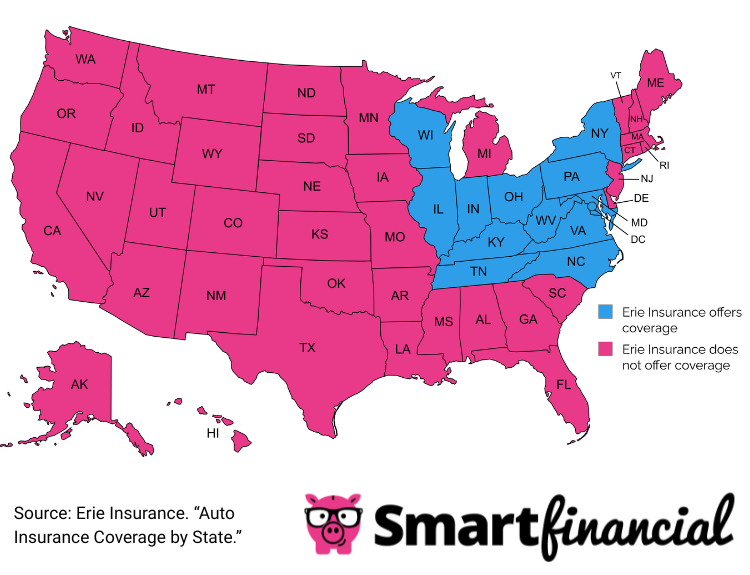
Currently, Erie Insurance provides coverage in 12 states and the District of Columbia. These include:
-
Illinois
-
Indiana
-
Kentucky
-
Maryland
-
New York
-
North Carolina
-
Ohio
-
Pennsylvania
-
Tennessee
-
Virginia
-
West Virginia
-
Wisconsin
-
District of Columbia
While this footprint may seem modest compared to companies with multi-billion dollar advertising budgets, Erie’s focused geographic presence is a calculated business strategy that influences its pricing, service quality, and financial stability.
The Strategic Logic of Regional Insurance Operations
From a personal finance perspective, the “why” behind Erie’s limited geographic reach is just as important as the “where.” Most national insurers must account for diverse high-risk environments—from California wildfires to Gulf Coast hurricanes. These massive risks often necessitate higher premiums across the board to maintain solvency.
By contrast, Erie Insurance focuses on a specific corridor of the United States where they possess deep historical data and localized expertise. This regional focus allows them to refine their underwriting processes, often resulting in more competitive premiums for low-risk policyholders in their coverage area.
Underwriting Precision and Premium Stability
In the world of finance, predictability is an asset. Erie’s regional concentration allows for a more granular understanding of local risks, such as winter weather patterns in Wisconsin or urban liability trends in the District of Columbia. Because they are not over-leveraged in disaster-prone regions like Florida or the Gulf, they can maintain a more stable pricing structure. For the policyholder, this means fewer “sticker shock” renewals and a more predictable monthly cash flow.
The Independent Agent Model
One of Erie’s defining characteristics is its reliance on independent agents. Unlike “captive” agents who work for only one brand, independent agents represent multiple carriers. In the states where Erie operates, they have cultivated a network of local professionals who understand the specific economic and legal nuances of their communities. For a business owner in North Carolina or a homeowner in Pennsylvania, this means getting financial advice tailored to local regulations and property values, rather than a generic national template.
Protecting Personal Wealth: Home, Auto, and Life Coverage
Insurance is essentially the “defense” of your financial game plan. You can spend years investing in the stock market or building home equity, but a single lawsuit or a total property loss can wipe out decades of progress. Erie Insurance structures its personal lines to address these specific threats within its coverage states.
Auto Insurance and the “Rate Lock” Feature
Perhaps the most famous financial tool in Erie’s arsenal is the “Erie Rate Lock” feature. In a period of high inflation, auto insurance premiums are often the first to rise as repair costs and medical expenses climb. The Rate Lock feature allows policyholders to keep the same premium year after year, even if they have a claim, until they make a significant change to the policy (like adding a driver or a new vehicle). This is a powerful tool for long-term budgeting, providing a level of cost certainty that few national competitors can match.
Comprehensive Home and Property Protection
For most individuals, their home is their largest financial asset. Erie’s coverage in states like New York and Virginia is designed to account for regional architectural styles and local rebuilding costs. Their policies often include “guaranteed replacement cost,” which ensures that if a home is destroyed, the insurer pays to rebuild it in its original condition, even if the cost exceeds the policy limits. In a volatile real estate market, this protection ensures that your net worth remains intact regardless of fluctuating construction material prices.
Life Insurance as a Wealth Transfer Tool
While many associate Erie primarily with property and casualty insurance, their life insurance offerings are a vital component of estate planning. By integrating life insurance into their regional ecosystem, they offer policyholders the ability to bundle coverage, often unlocking discounts on property premiums while simultaneously securing a tax-advantaged death benefit for heirs. This holistic approach to personal finance ensures that the policyholder’s family is protected from the financial fallout of an untimely death.
Business Finance: Commercial Coverage for Regional Growth
For entrepreneurs and small business owners in the Erie footprint, insurance is not just a regulatory requirement; it is a tool for scaling and risk mitigation. Erie Insurance offers a robust suite of commercial products that cater to the specific industries prevalent in the Mid-Atlantic and Midwest, such as manufacturing, professional services, and retail.
Liability and Asset Protection for Small Businesses
A business’s balance sheet is only as strong as its liability protection. Erie provides general liability, professional liability (errors and omissions), and umbrella coverage that acts as a safety net for business assets. In states like Ohio and Illinois, where legal climates can be complex, having a regional carrier that understands local litigation trends can be a significant advantage in defending against claims.
Workers’ Compensation and Employee Retention
In the competitive labor markets of the East Coast and Great Lakes, offering a safe work environment and reliable benefits is key to retention. Erie’s workers’ compensation programs help businesses navigate state-specific mandates while providing resources for workplace safety. Efficiently managed workers’ comp claims directly affect a business’s experience modifier (E-mod) rating, which in turn dictates future premiums. Proper management here is a direct lever for improving a company’s bottom line.
Protecting the Gig Economy and Small Side Hustles
As the nature of work changes, so do the financial risks. Erie has been a pioneer in offering coverage for “shared-use” activities, such as ridesharing or home-sharing. For individuals running side hustles in North Carolina or Maryland, standard personal policies often leave a massive “coverage gap” when the vehicle or home is being used for profit. Erie’s specific endorsements for these activities provide a low-cost way to protect personal assets from business-related liabilities.
Financial Strength and Reliability: The A.M. Best Perspective
When selecting a financial partner, the institution’s own stability is paramount. You are essentially buying a promise of future payment, and that promise is only as good as the company’s balance sheet. Erie Insurance is a Fortune 500 company and consistently earns high marks from credit rating agencies.
Credit Ratings and Solvency
Erie Family Life Insurance Company and Erie Insurance Property & Casualty have historically maintained “A” (Excellent) or higher ratings from A.M. Best, the leading authority on insurance company financial strength. These ratings indicate that Erie has a “superior” ability to meet its ongoing insurance obligations. For a policyholder, this means peace of mind that when a major claim is filed—whether due to a localized storm or a personal tragedy—the funds will be available.
Claims Efficiency and Financial Fairness
The true value of an insurance policy is realized at the moment of a claim. Erie has built a reputation for fairness in its claims process, which is a critical financial consideration. Slow or contested claims can force individuals to dip into emergency funds or take on debt to cover immediate repairs. Erie’s commitment to “The Golden Rule”—treating others as you would want to be treated—translates into a claims culture that prioritizes swift and fair resolution, minimizing the financial disruption to the policyholder.
Navigating Portability and Relocation
A common concern for mobile professionals is what happens when they move outside of Erie’s 12-state footprint. Because Erie is regional, a move to California, Texas, or Florida would necessitate a change in carriers.
The Financial Cost of Switching
Moving often triggers a “re-shopping” of insurance, which can be a double-edged sword. While it allows you to see what else is on the market, you may lose longevity discounts and the Rate Lock benefits you’ve accumulated with Erie. For those planning a move, it is wise to consult with an Erie agent to understand the timeline for transitioning coverage and to ensure there are no lapses in protection, which can lead to higher premiums with a new insurer.
Strategic Planning for Regional Investments
If you own rental properties or business interests in multiple states, you may find yourself in a hybrid situation. You might use Erie for your primary residence and business in Pennsylvania, while requiring a different carrier for a vacation home in South Carolina. Managing a multi-carrier portfolio requires a disciplined approach to financial organization, but it often allows you to leverage the “best of breed” carriers for each specific geographic risk.

Conclusion: Integrating Erie into Your Financial Strategy
For residents of the states Erie covers, the company represents a unique intersection of regional expertise and national financial strength. By choosing a carrier with a focused footprint, policyholders can often access more stable premiums, specialized coverage features like Rate Lock, and a network of agents who are deeply embedded in the local economy.
In the broader context of personal finance, insurance should never be viewed as a “set it and forget it” expense. It is a dynamic component of wealth preservation. Whether you are protecting a burgeoning small business in Virginia or insuring a first home in Wisconsin, understanding the geographic and financial nuances of Erie Insurance allows you to build a more resilient and predictable financial future. In the states where they operate, Erie remains a formidable guardian of their policyholders’ hard-earned assets.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.