
In the dynamic world of personal finance, investing, and business strategy, seemingly simple mathematical questions often hold the key to profound insights. The query, “what is 2/3 of 24,” might appear basic, a relic from school days. However, its implications extend far beyond the classroom, serving as a foundational building block for countless financial decisions we make daily. For anyone navigating the complexities of money, from budgeting household expenses to analyzing investment returns or structuring business deals, a firm grasp of fractions and basic arithmetic is not just useful—it’s indispensable. This article delves into the significance of such fundamental calculations within the realm of money, demonstrating how mastering these core concepts empowers individuals and businesses alike to make informed, strategic financial choices.

The immediate answer to “what is 2/3 of 24” is 16. This is derived by multiplying 24 by the numerator (2) and then dividing by the denominator (3), or by first dividing 24 by 3 (which is 8) and then multiplying by 2. While the calculation itself is straightforward, its power lies in its applicability across the entire financial spectrum, transforming abstract numbers into actionable intelligence.
The Foundation of Financial Literacy: Basic Arithmetic as a Cornerstone
Financial literacy is often lauded as a crucial skill in modern society, yet its bedrock often goes unacknowledged: fundamental arithmetic. Before one can grapple with sophisticated algorithms or complex financial models, an intuitive understanding of numbers, fractions, percentages, and ratios is essential. The seemingly simple operation of finding “2/3 of 24” is a perfect microcosm of this foundational necessity.
Deciphering “2/3 of 24”: More Than Just a Number
At its core, calculating “2/3 of 24” teaches us about proportionality and allocation. It’s about understanding how a whole (24) can be divided into parts, and how a specific fraction represents a segment of that whole. In finance, this translates directly into understanding how income is distributed, how assets are divided, or how liabilities are proportioned. For instance, if a company’s total profit is $24 million, and 2/3 of it is allocated to shareholder dividends, knowing this basic calculation immediately tells us that $16 million will be distributed, leaving $8 million for reinvestment or other purposes. Without this foundational understanding, even with a calculator, the meaning and implications of such an allocation could be lost.
Why Simple Calculations Matter More Than Ever
In an era saturated with financial apps, automated budgeting tools, and AI-driven investment platforms, one might argue that manual arithmetic is obsolete. However, relying solely on technology without comprehending the underlying mechanics creates a dangerous dependency. When you understand how to calculate 2/3 of 24, you’re not just getting an answer; you’re developing numerical intuition. This intuition allows you to critically evaluate the outputs of financial tools, spot potential errors, and most importantly, understand the why behind financial outcomes. It builds confidence and reduces the vulnerability to misinformation or algorithmic black boxes. Moreover, in rapid decision-making scenarios where a calculator might not be immediately available, an ingrained ability to perform mental arithmetic can be a significant advantage, whether negotiating a deal or quickly assessing a financial proposal.
Practical Applications in Personal Finance
For the average individual, the ability to perform calculations like “2/3 of 24” is directly applicable to managing everyday money. From budgeting to understanding consumer economics, these skills are continually put to the test.
Budgeting and Allocating Funds
One of the most common applications of fractions in personal finance is budgeting. Many financial advisors recommend allocating portions of income to different categories, such as savings, essential expenses, and discretionary spending. For example, the popular “50/30/20 rule” suggests 50% for needs, 30% for wants, and 20% for savings and debt repayment. If your take-home pay is $3,600, understanding fractions or percentages allows you to quickly determine that $1,800 (1/2 or 50%) goes to needs, $1,080 (3/10 or 30%) to wants, and $720 (1/5 or 20%) to savings. Similarly, if you decide to save 2/3 of any bonus you receive, and that bonus is $2,400, knowing how to calculate 2/3 of $2,400 ($1,600) instantly informs your savings plan. This clear numerical understanding is crucial for effective financial planning and achieving financial goals.
Understanding Discounts and Sales
Consumer spending is heavily influenced by discounts and sales, which are almost universally expressed as percentages or fractions. A “25% off” sale is a common example. To calculate the savings, you need to find 25% (or 1/4) of the original price. If an item costs $24, and it’s 25% off, you save $6. Understanding this empowers you to discern real savings from perceived ones, compare deals, and make smarter purchasing decisions. It prevents you from being swayed by marketing tactics that obscure the actual value proposition.
Loan Repayments and Interest
While interest calculations can become complex with compounding, the basic principles often involve fractions or percentages of a principal amount. Understanding how to calculate a fraction of a whole helps in grasping how much of each payment goes towards the principal versus interest, or how a specific portion of your income might be dedicated to debt repayment. For instance, if your total monthly debt obligations represent 1/3 of your income, and your income is $3,600, you know that $1,200 is committed to debt. This helps in assessing affordability and planning for debt reduction strategies.
Navigating Investments and Returns
The world of investing, often perceived as highly complex, is built upon a foundation of mathematical principles, where fractions and ratios play a crucial role in understanding returns, risk, and portfolio composition.
Fractional Ownership and Dividends
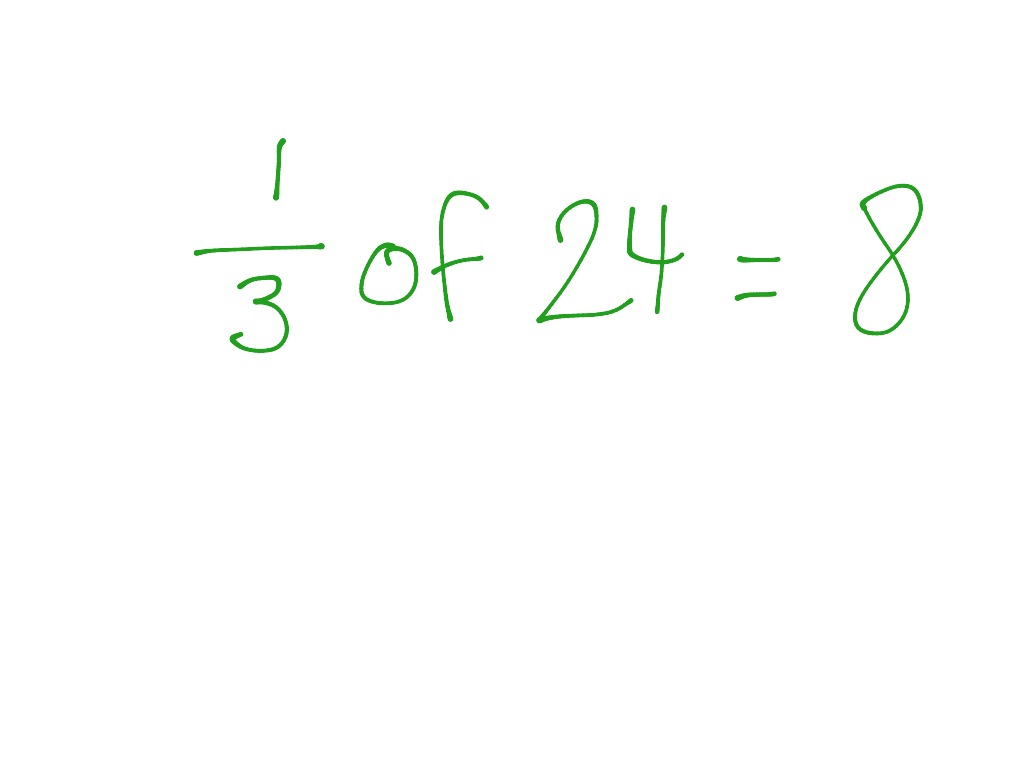
In modern investment, fractional shares allow investors to own a portion of a company’s stock, even if they can’t afford a full share. This is a direct application of fractions. Similarly, dividends are often paid out as a fraction of a company’s earnings per share or as a fixed amount per share. If a company announces a dividend of $1.50 per share, and you own 2/3 of a full share, understanding how to calculate 2/3 of $1.50 is vital to know your actual payout ($1.00). In private equity or small business investments, ownership stakes are almost always expressed as percentages or fractions, directly impacting profit sharing and voting rights.
Calculating Portfolio Growth and Losses
Assessing investment performance invariably involves calculating returns, which are typically expressed as percentages or fractions of the initial investment. If you invest $2,400 and your portfolio grows to $2,560, you’ve gained $160. To express this as a fraction or percentage, you calculate $160/$2,400, which simplifies to 1/15 or approximately 6.67%. Conversely, if your portfolio loses 2/3 of its value from an initial $24,000, you immediately understand you’ve lost $16,000, leaving you with $8,000. This immediate numerical comprehension is critical for evaluating investment strategies, understanding risk, and making timely adjustments. It helps distinguish between nominal and real returns, especially when factoring in inflation, which itself is often presented as a percentage.
The Power of Compound Interest
While compound interest often involves exponential growth, its fundamental calculation starts with simple interest, which is a fraction or percentage of the principal. Understanding how small fractions of interest accrue over time, and how they contribute to the principal for subsequent interest calculations, is crucial for appreciating the “eighth wonder of the world.” For example, knowing that even a modest 2% annual return means your initial investment grows by 2/100 each year helps to demystify the long-term wealth creation process and encourages consistent saving and investing.
Business Finance and Strategic Decision-Making
For businesses, from startups to multinational corporations, financial calculations are the bedrock of operational efficiency, profitability analysis, and strategic growth. Fractions and ratios are fundamental tools in these endeavors.
Profit Sharing and Revenue Allocation
Businesses frequently need to allocate profits, revenues, or resources based on pre-defined agreements, often expressed as fractions or percentages. Partners might agree to split profits 50/50, or an executive bonus pool might be 10% of quarterly net profit. If a startup generates $240,000 in revenue, and 2/3 of it is earmarked for operational costs, the ability to quickly calculate $160,000 provides immediate insight into the remaining funds for profit or investment. Similarly, understanding how to distribute 2/3 of a specific budget of $24,000 across two departments, perhaps proportionally, requires this basic numerical agility. These calculations are not just administrative tasks; they are strategic decisions that impact the health and future of the enterprise.
Inventory Management and Cost Analysis
Managing inventory efficiently often involves tracking ratios of goods sold to goods available, or understanding the fraction of defective units. If a production run yields 24,000 units, and 2/3 of them are sold in the first quarter, knowing that 16,000 units have moved allows for accurate forecasting, production planning, and resource allocation. Cost analysis also relies heavily on breaking down total costs into their constituent parts, often represented as fractions of the whole. For instance, determining that raw materials account for 2/3 of the total production cost informs procurement strategies and pricing decisions.
Understanding Financial Ratios
Beyond simple fractions, financial ratios are powerful tools used by businesses and investors to assess a company’s performance, liquidity, profitability, and solvency. Ratios like the debt-to-equity ratio, current ratio, or profit margin are essentially fractions that express the relationship between two financial figures. While these can become complex, the foundational understanding of what a fraction represents—a part of a whole, or a relationship between two numbers—is essential to interpret them correctly. A high debt-to-equity ratio (e.g., 2:1, or 2/1) immediately signals a company with more debt than equity, prompting further investigation.
From Calculation to Confident Financial Action
The journey from understanding “what is 2/3 of 24” to confidently navigating complex financial scenarios is a continuous one. It’s about building blocks, where each piece of knowledge empowers the next.
Overcoming Math Anxiety in Finance
Many individuals harbor a degree of math anxiety, which can unfortunately spill over into financial decision-making. By starting with simple, relatable problems like finding a fraction of a number, individuals can build confidence. Realizing that complex financial concepts are often just collections of simpler calculations can demystify finance and make it more accessible. The answer to “2/3 of 24” isn’t intimidating; it’s a stepping stone. Embracing this fundamental arithmetic as a skill, rather than a chore, is the first step towards financial empowerment.
Leveraging Tools, Not Replacing Understanding
Modern financial tools, from spreadsheets to sophisticated software, are invaluable for handling large datasets and complex calculations quickly and accurately. However, these tools are most effective when wielded by users who understand the underlying mathematics. A spreadsheet formula calculating 2/3 of a column of numbers is only as good as the user’s understanding of what that fraction represents and its implications. Relying solely on a tool without understanding the logic behind its output can lead to misinterpretations, erroneous conclusions, and ultimately, poor financial decisions. The human element of critical thinking, informed by numerical literacy, remains irreplaceable.
The Lifelong Journey of Financial Acumen
Financial literacy is not a destination but a lifelong journey. The ability to perform basic calculations, to understand proportions, and to interpret numbers within a financial context is a continually evolving skill. Just as physical fitness requires consistent effort, so too does financial acumen. Regularly engaging with financial information, practicing simple calculations, and seeking to understand the quantitative aspects of financial news and personal choices reinforces these fundamental skills. The seemingly small act of calculating “2/3 of 24” is a powerful reminder that mastery of the basics is the true gateway to financial confidence, control, and long-term success in the multifaceted world of money.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.