
The intersection of healthcare, demographics, and finance presents a complex landscape when examining the prevalence and management of Down syndrome. While the genetic occurrence of Trisomy 21 is a global phenomenon that transcends racial and ethnic boundaries, the economic realities associated with the condition vary significantly across different populations. Understanding “what race Down syndrome is most common in” requires more than a simple biological tally; it necessitates a deep dive into the socio-economic factors, the business of healthcare delivery, and the long-term financial planning required to support individuals with intellectual and developmental disabilities (IDD).

From a financial perspective, the prevalence of Down syndrome is a critical metric for insurance providers, public health agencies, and investment firms specializing in healthcare infrastructure. By analyzing how different demographics interact with the medical and financial systems, we can identify gaps in resource allocation and opportunities for more equitable investment in support services.
The Socio-Economic Metrics of Genetic Health
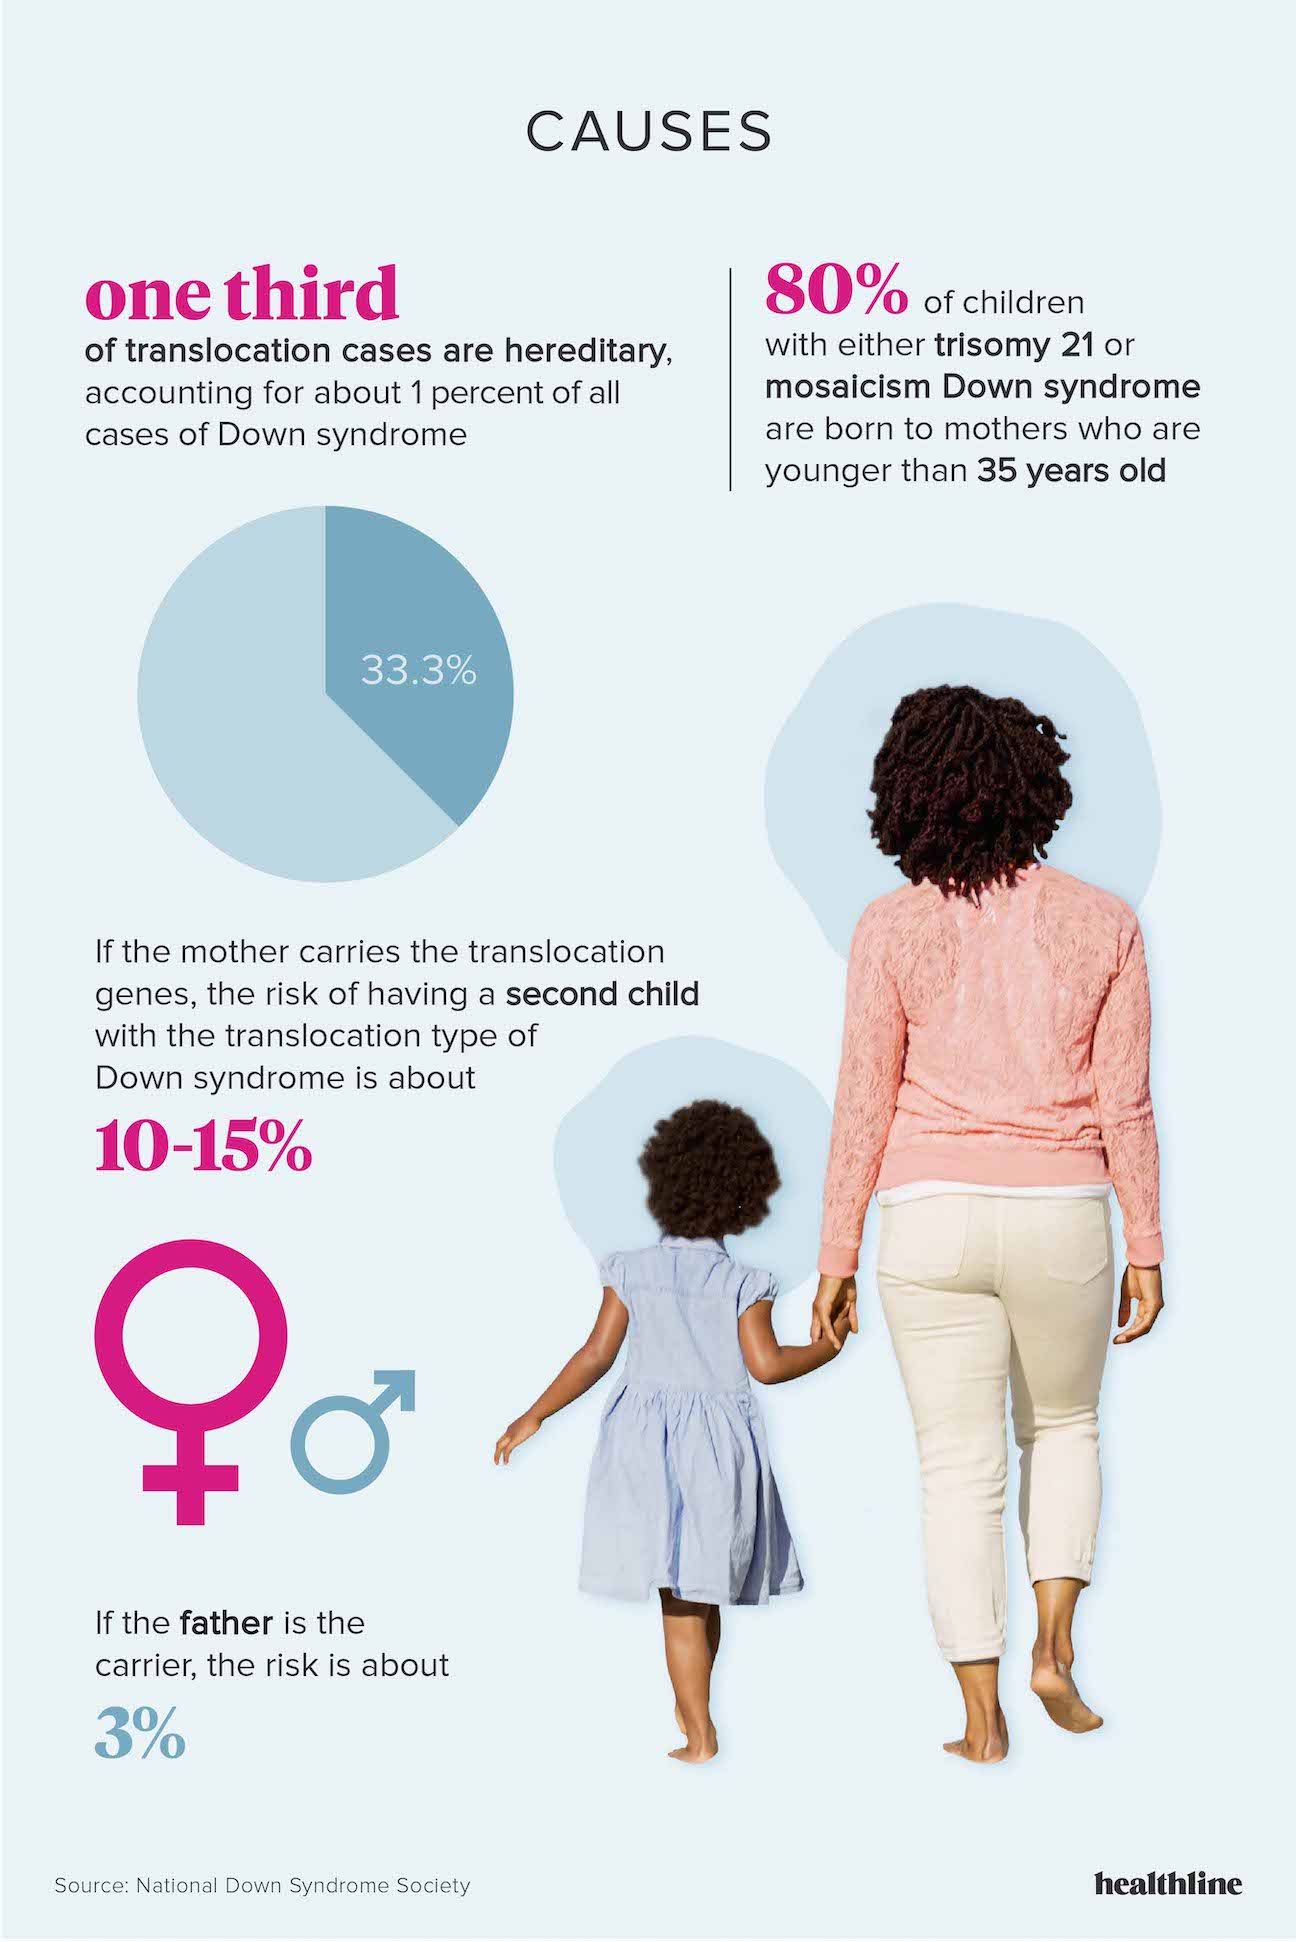
Statistically, Down syndrome occurs in approximately 1 out of every 700 births across the globe. Research consistently shows that the genetic mutation responsible for Down syndrome does not discriminate based on race or ethnicity. However, the recorded prevalence and the survival rates of individuals with the condition often show marked differences when viewed through an economic lens.
Statistical Consistency vs. Economic Variance
Medical data suggests that the biological frequency of Down syndrome is relatively uniform across racial groups. However, the “Money” aspect of this data comes into play when we look at birth rates and maternal age—a primary risk factor—which are often influenced by socio-economic status. In many developed economies, women with higher levels of education and higher household incomes tend to delay childbirth. Because the probability of having a child with Down syndrome increases with maternal age, these higher-income demographics often see a higher statistical incidence of the condition at birth.
Conversely, in lower-income demographics, where maternal age may be younger on average, the biological frequency might be lower, but the financial burden of care is often significantly higher due to a lack of preventative healthcare and prenatal screening. For the financial sector, this creates a paradox: the populations that might have a higher frequency of the condition often have more resources to manage it, while those with lower frequency face systemic financial barriers that compound the costs of care.
The Financial Cost of Late Diagnosis in Underserved Communities
Access to prenatal testing is a significant driver of demographic data. Non-invasive prenatal testing (NIPT) and other screening technologies are often more accessible to families with robust private insurance or higher disposable income. In many minority or lower-income communities, the financial barriers to these screenings result in fewer diagnoses during pregnancy.
From a business and insurance perspective, a late diagnosis or a diagnosis at birth rather than during pregnancy changes the financial trajectory of the family’s healthcare spending. Early intervention services, which are proven to reduce long-term care costs by improving developmental outcomes, are often more readily available in affluent areas. The economic impact of missing these early windows of intervention can lead to hundreds of thousands of dollars in additional lifetime care costs, disproportionately affecting minority families who may already be facing a wealth gap.
Resource Allocation and the Market for Support Services
The question of prevalence is inextricably linked to the geography of wealth. Where Down syndrome is most “visible” or “common” in the public record often aligns with where the most financial resources are being spent. The market for support services—including specialized education, occupational therapy, and speech pathology—is a multi-billion dollar industry that gravitates toward regions with high insurance reimbursement rates and private-pay capabilities.
The Geography of Wealth and Healthcare Infrastructure
Financial analysis of healthcare infrastructure reveals that specialized clinics and therapeutic centers are frequently concentrated in metropolitan areas with high property values. For families in rural or economically disadvantaged urban areas, the “cost” of Down syndrome includes not only direct medical bills but also the “opportunity cost” of travel time and lost wages to access quality care.
For investors looking at the healthcare and real estate sectors, there is a growing demand for “inclusive development.” This involves the creation of housing and care facilities that are subsidized through public-private partnerships, aiming to bring high-quality support to a broader range of racial and socio-economic demographics. Bridging this gap is not just a social imperative but a viable business strategy, as it taps into underserved markets and utilizes government incentives like the Low-Income Housing Tax Credit (LIHTC).
Investing in Inclusive Educational Technologies
The EdTech sector has seen a surge in investment directed toward inclusive learning tools. AI-driven apps and software designed for individuals with Trisomy 21 are becoming essential components of the educational landscape. However, the distribution of these technologies often mirrors the racial wealth gap.
Venture capital firms are increasingly focusing on the “accessibility” niche, recognizing that software which can be scaled across public school systems—regardless of the racial makeup of the student body—offers a more stable return on investment than high-end, niche products. By focusing on the economic democratization of these tools, the tech-finance sector can play a role in equalizing the developmental outcomes for children of all races with Down syndrome.
Long-Term Financial Planning: Bridging the Demographic Gap
The lifetime cost of supporting an individual with Down syndrome can exceed $1 million, excluding standard living expenses. This includes medical procedures, specialized equipment, lifelong therapy, and long-term residential care. For families across all racial backgrounds, the primary financial challenge is ensuring that their loved ones are provided for after the primary caregivers are gone.
The Role of ABLE Accounts in Wealth Preservation
The Achieving a Better Life Experience (ABLE) Act has been a game-changer in the world of personal finance for families dealing with disabilities. These tax-advantaged savings accounts allow individuals with Down syndrome and their families to save for disability-related expenses without losing eligibility for means-tested government benefits like Medicaid and Supplemental Security Income (SSI).
From a financial planning perspective, the adoption of ABLE accounts varies by demographic. Financial advisors are increasingly playing a role in outreach to minority communities to ensure they are aware of these vehicles for wealth preservation. Promoting these accounts is a critical step in narrowing the financial disparity between races, as it allows families to build a “financial safety net” that is protected from the asset limits typically imposed on social safety net programs.
Special Needs Trusts and Estate Planning Strategies
For high-net-worth individuals, Special Needs Trusts (SNTs) are a standard tool for estate planning. These legal arrangements allow for the transfer of significant assets to benefit an individual with a disability while maintaining their eligibility for public assistance.
However, the legal and administrative fees associated with setting up a professional SNT can be a barrier for middle- and lower-income families. The rise of “pooled trusts,” managed by non-profit organizations, has created a more affordable entry point for families who do not have the capital to establish a standalone private trust. For financial institutions, offering these products to a diverse client base is both a revenue-generating opportunity and a way to foster long-term brand loyalty among a demographic that is often overlooked.
The Corporate Responsibility and Business of Inclusion
As corporations move toward more robust Environmental, Social, and Governance (ESG) frameworks, the inclusion of individuals with Down syndrome in the workforce has become a focus of business strategy. The economic impact of employing individuals with disabilities is profound, reducing the reliance on government subsidies and increasing the tax base.
Corporate Social Responsibility (CSR) and Demographic Outreach
Many major corporations have recognized that their customer base is diverse and that their workforce should reflect that diversity—including neurodiversity. Companies that actively recruit individuals with Down syndrome from all racial backgrounds often see improved internal culture and enhanced brand reputation.
From a “Money” perspective, CSR initiatives that support the Down syndrome community often result in tangible financial benefits, such as tax credits (like the Work Opportunity Tax Credit in the U.S.) and increased loyalty from the “disability market,” which is estimated to control billions of dollars in discretionary spending.
The Economic Impact of Workplace Inclusion
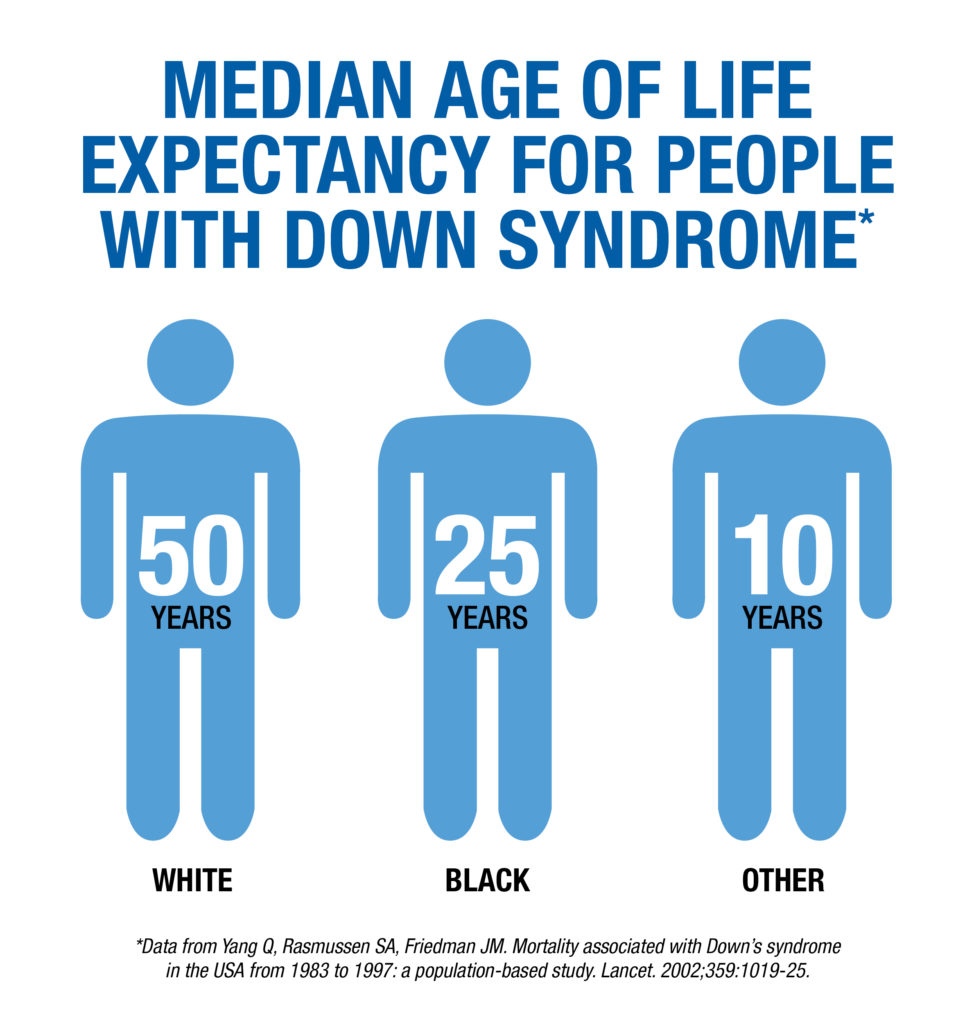
The business case for inclusion is backed by data showing that employees with Down syndrome often have higher retention rates and contribute to a more positive work environment, which reduces turnover costs. However, the opportunities for employment are not always distributed equally across races. Economic data shows that minority individuals with disabilities often face a “double disadvantage” in the labor market.
Businesses that prioritize the recruitment of minority individuals with Down syndrome are not only fulfilling a social goal but are also optimizing their human capital. By investing in job coaching and workplace accommodations, companies can tap into a loyal and hardworking demographic, driving productivity and fostering an inclusive economy that benefits everyone.
In conclusion, while the genetic prevalence of Down syndrome is consistent across all races, the financial experience of the condition is deeply influenced by socio-economic status and systemic economic factors. By focusing on equitable access to financial planning tools, healthcare infrastructure, and employment opportunities, the financial sector can help ensure that every individual with Down syndrome, regardless of race, has the resources necessary to lead a full and productive life. For the savvy investor or the professional financial planner, understanding these nuances is essential for navigating the evolving landscape of healthcare and social responsibility.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.