
The question “what meds to take for COVID” typically conjures images of clinical decisions, efficacy rates, and medical protocols. However, in an increasingly complex healthcare ecosystem, this inquiry also carries significant financial implications for individuals, families, and even national economies. Beyond the immediate health outcomes, the choice of treatment, its availability, and how it is funded can profoundly impact personal finances and long-term economic well-being. This article delves into the financial considerations that intertwine with the medical decisions surrounding COVID-19 treatments, offering insights for navigating the monetary landscape of pandemic-era healthcare.

The Evolving Financial Landscape of COVID-19 Treatments
The journey through the COVID-19 pandemic has been marked by a dynamic shift in treatment availability and, consequently, their financial profiles. From emergency measures to sophisticated antiviral therapies, understanding the cost structure is crucial for informed decision-making.
Initial Emergency Measures vs. Sustained Costs
In the early stages of the pandemic, many governments and healthcare systems absorbed the costs of testing, vaccines, and even certain treatments as an emergency public health measure. This initial phase, characterized by widespread government subsidies, created an environment where the financial burden on individuals was significantly minimized. However, as the pandemic transitioned into an endemic phase and emergency declarations waned, the financial models for COVID-19 care began to normalize, shifting costs back towards traditional insurance frameworks and out-of-pocket expenses. This transition often caught individuals unprepared, highlighting the importance of understanding the shift from collective funding to individual responsibility. What was once free or heavily subsidized might now be a significant expenditure, making the question of “what meds to take” inherently a financial one, even before clinical efficacy is considered.
The Price Tags of Prominent Antivirals and Therapies
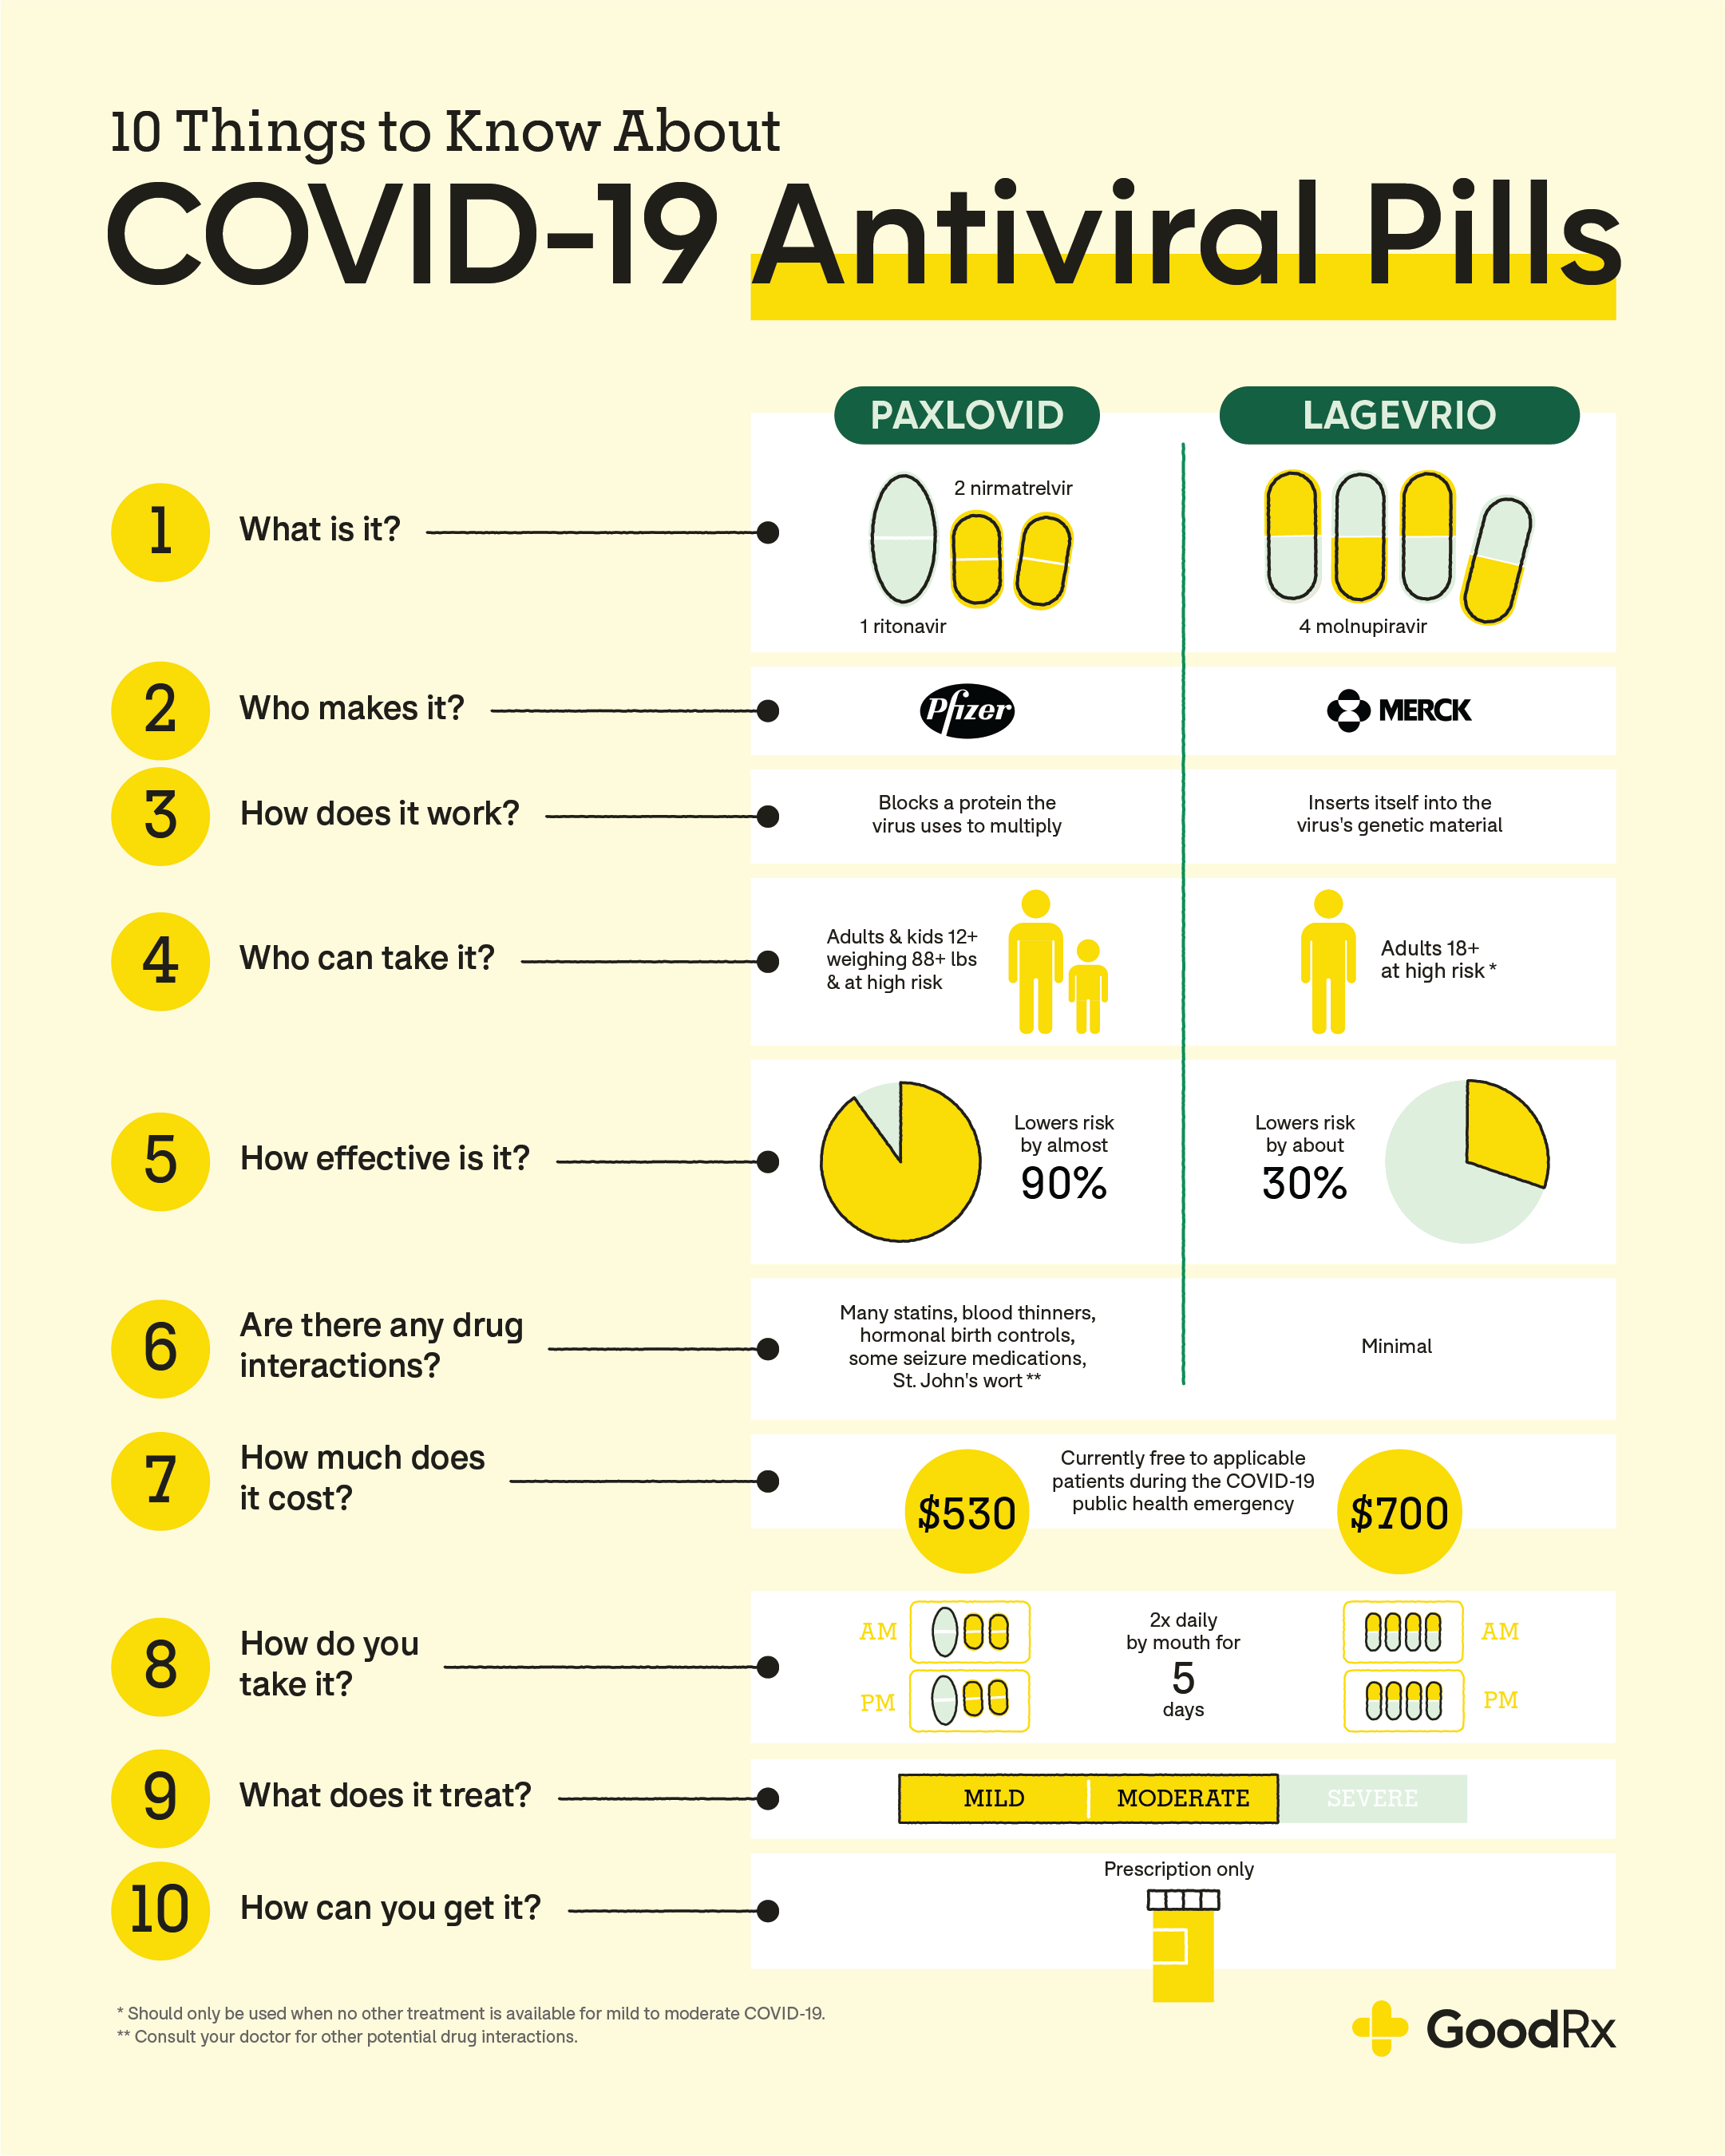
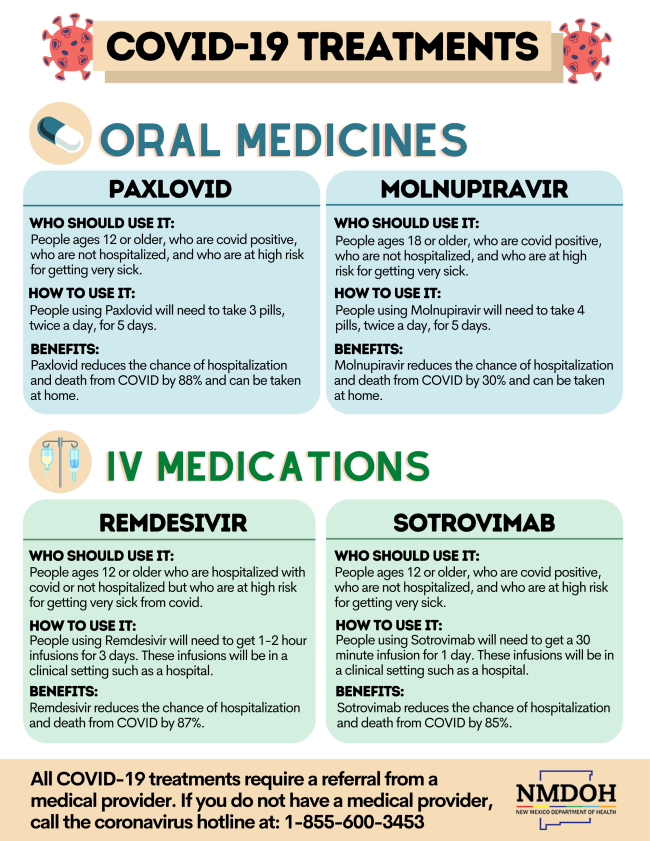
Today, a range of antiviral medications and monoclonal antibody treatments are available, each with its own development costs, manufacturing expenses, and ultimately, market price. Drugs like Paxlovid, Remdesivir, and various monoclonal antibodies, while highly effective in preventing severe illness, come with substantial price tags. These costs are influenced by research and development investments, the complexity of the manufacturing process, intellectual property rights, and the market strategies of pharmaceutical companies. For instance, a course of a leading antiviral treatment can range from hundreds to over a thousand dollars without insurance or government subsidy. These figures underscore why personal financial planning and understanding insurance coverage are paramount when considering treatment options. The choice isn’t just about effectiveness; it’s about affordability and access.
Generics and Biosimilars: A Future of Cost Reduction?
Looking ahead, the pharmaceutical industry often sees the introduction of generic versions of drugs once their patent protections expire. Similarly, for biologics, biosimilars offer a potentially more affordable alternative. The advent of generic COVID-19 medications and biosimilar monoclonal antibodies could dramatically alter the financial landscape of treatment. Lower-cost alternatives would improve access for a broader population, reduce the financial strain on healthcare systems, and lessen the out-of-pocket burden on patients. However, the timeline for such developments depends on patent expirations, regulatory approvals, and manufacturing capacities. Financial planners and individuals alike should keep an eye on these developments, as they represent a significant opportunity for future cost reductions in COVID-19 management.
Navigating Insurance, Coverage, and Personal Financial Burden
The actual cost an individual pays for COVID-19 medication is rarely the list price. It is heavily mediated by health insurance, government programs, and personal financial circumstances. Understanding these layers is critical for making financially sound health decisions.
Decoding Your Health Insurance Benefits for COVID-19
Your health insurance policy is the primary determinant of your out-of-pocket expenses for COVID-19 treatments. Policies vary widely in what they cover, the percentages they cover, and the specific stipulations for pandemic-related care. It is imperative to proactively review your plan’s Summary of Benefits and Coverage (SBC), pay particular attention to sections on prescription drug coverage, specialist visits, and emergency care. Some plans might cover certain antivirals fully, while others might require significant co-pays or be subject to deductibles. Calling your insurance provider directly or checking their website for up-to-date information on COVID-19 specific coverage is an essential step. Misunderstanding your benefits can lead to unexpected and substantial medical bills.
Understanding Co-pays, Deductibles, and Out-of-Pocket Maximums
Beyond just “coverage,” the specific mechanics of your insurance plan—deductibles, co-pays, and out-of-pocket maximums—play a crucial role. A deductible is the amount you must pay out of pocket before your insurance company starts to pay. If you haven’t met your deductible, even a covered COVID-19 medication might be entirely your responsibility. Co-pays are fixed amounts you pay for covered healthcare services, including prescriptions, after your deductible has been met. An out-of-pocket maximum is the most you will have to pay for covered services in a plan year. Once you reach this limit, your health plan pays 100% of the allowed amount for covered services. Being aware of where you stand with these figures can significantly influence your financial decision-making, particularly if you’re weighing the cost of treatment against potential hospitalization.
Government Programs and Financial Assistance for Treatment Access
Despite the phasing out of some emergency measures, various government programs and pharmaceutical patient assistance programs (PAPs) may still offer financial relief. These programs can help cover the cost of medications for individuals who are uninsured, underinsured, or meet certain income criteria. Websites of national health agencies or specific pharmaceutical companies often provide details on eligibility and application processes. Exploring these avenues can bridge significant financial gaps, ensuring that essential treatments are accessible regardless of an individual’s immediate ability to pay the full cost. Leveraging these resources is a smart financial move for individuals facing high treatment costs.
The Hidden Costs: Beyond Medication Prices
The financial burden of COVID-19 extends beyond the direct cost of medication. There are “hidden” costs that can quickly add up. These include transportation to medical appointments, lost wages due to illness or caregiving responsibilities, the cost of over-the-counter symptom relief, and potential long-term care for “Long COVID” symptoms. For individuals, these indirect costs can sometimes outweigh the direct medication expenses, emphasizing the broader economic impact of the disease. A holistic financial assessment should encompass these often-overlooked expenditures to fully understand the monetary implications of a COVID-19 diagnosis and treatment path.
The Economic Rationale for Timely Treatment Decisions
Making informed decisions about COVID-19 treatments isn’t just about immediate medical efficacy; it’s also about a proactive financial strategy. Early intervention can often prevent a cascade of more severe, and more costly, health outcomes.
Avoiding Escalating Costs of Severe Illness and Hospitalization
Perhaps the most compelling financial argument for taking effective COVID-19 medications early is the dramatic cost difference between outpatient treatment and hospitalization. A course of an antiviral might cost a few hundred to a thousand dollars. In stark contrast, a single day in an intensive care unit (ICU) can cost several thousand dollars, with a full hospitalization easily running into tens of thousands or even hundreds of thousands of dollars, depending on the severity and duration of care required. From a pure financial risk management perspective, investing in an early, effective treatment that significantly reduces the likelihood of severe illness and hospitalization is an overwhelmingly prudent decision. It’s an economic hedge against catastrophic medical debt.
Productivity Losses and Impact on Income
Beyond direct medical costs, severe illness from COVID-19 leads to significant productivity losses. For individuals, this translates to lost income from missed workdays. For self-employed individuals or small business owners, this can be even more devastating, potentially halting operations and severely impacting revenue. Even for those with paid sick leave, prolonged illness can exhaust benefits, leading to unpaid time off. By reducing the severity and duration of illness, effective medications can help individuals return to work sooner, minimizing the financial impact on their earnings and overall economic stability. The “cost” of illness is often far greater than just the medical bills; it includes the loss of earning potential.
The Cost-Benefit Analysis of Prevention and Early Intervention
When viewed through a financial lens, prevention, and early intervention become clear priorities. Vaccines, though not a treatment for active infection, dramatically reduce the risk of severe disease, offering an unparalleled cost-benefit ratio by averting hospitalizations and long-term complications. Similarly, if infected, accessing and utilizing effective antiviral treatments early in the disease course is a financially sound decision. The relatively modest investment in these interventions pales in comparison to the potential financial burden of advanced medical care, rehabilitation, and long-term health issues associated with severe COVID-19. This proactive approach aligns both health and financial objectives.
Investment Horizons: The Pharmaceutical Sector and Pandemic Preparedness
The COVID-19 pandemic not only reshaped individual financial decisions but also highlighted the immense economic power and investment opportunities within the pharmaceutical and biotechnology sectors.
Identifying Key Players in COVID-19 Therapeutics Development
For investors, the companies at the forefront of COVID-19 therapeutic development became significant players. Pharmaceutical giants and innovative biotech firms that successfully developed vaccines, antiviral drugs, and other treatments saw substantial increases in market valuation. Identifying these key players requires understanding the science behind the treatments, regulatory pathways, manufacturing capabilities, and global distribution networks. Savvy investors followed companies like Pfizer, Merck, Gilead Sciences, and others closely, recognizing the potential for both short-term gains and long-term growth driven by ongoing global health needs.
Biotech Innovation and Market Valuation
The pandemic accelerated innovation in the biotechnology sector, leading to breakthroughs in mRNA technology, rapid drug discovery, and efficient vaccine production. This surge in innovation has a direct impact on market valuation, as companies demonstrating cutting-edge research and development capabilities become attractive investment targets. The ability to quickly respond to health crises with effective solutions has proven to be an invaluable asset, driving investor confidence and capital flow into these areas. For those looking to invest in resilience and future-proof industries, the biotech sector, especially those focused on infectious diseases, presents a compelling case.
Ethical Investing vs. Profit Generation in Health Crises
The substantial profits generated by pharmaceutical companies during the pandemic sparked debates around ethical investing. While investors seek returns, the context of a global health crisis raises questions about fair pricing, equitable access, and the balance between shareholder value and public health imperatives. For individuals considering investments in this sector, integrating environmental, social, and governance (ESG) criteria can be a way to align financial goals with ethical considerations. It encourages investment in companies that not only deliver financial returns but also demonstrate a commitment to social responsibility, transparency, and accessible healthcare solutions, even amidst a crisis.
Building Financial Resilience for Future Health Challenges
The experience of COVID-19 has served as a powerful reminder of the unpredictable nature of health crises and the critical importance of financial preparedness. Proactive steps can significantly cushion the blow of future medical emergencies.
Emergency Funds and Health Savings Accounts (HSAs)
A robust emergency fund, typically covering 3-6 months of living expenses, is a foundational element of financial resilience. For health-related emergencies, this fund can be crucial. Additionally, Health Savings Accounts (HSAs) offer a tax-advantaged way to save for future medical expenses. Contributions are tax-deductible, funds grow tax-free, and withdrawals for qualified medical expenses are also tax-free. For individuals with high-deductible health plans, an HSA is an invaluable tool for covering deductibles, co-pays, and other out-of-pocket costs for medications and treatments, including those for conditions like COVID-19. Maximizing contributions to an HSA can provide a significant financial buffer during health challenges.
Comprehensive Health Insurance Review
Regularly reviewing and updating health insurance coverage is a critical aspect of financial planning for health. As personal circumstances change (e.g., family size, income, health status) or as healthcare policies evolve, your insurance needs may shift. It’s important to understand different plan types (HMO, PPO, EPO), network restrictions, prescription drug formularies, and overall cost-sharing structures. Opting for a plan with robust prescription coverage or a lower out-of-pocket maximum, even if premiums are slightly higher, can prove to be a financially superior choice if you anticipate significant medical needs or wish to mitigate risk during unforeseen health crises.
Strategic Financial Planning for Unexpected Medical Expenses
Beyond emergency funds and insurance, incorporating a strategy for unexpected medical expenses into your broader financial plan is wise. This might involve setting aside a specific portion of savings for healthcare, exploring critical illness insurance, or having a clear understanding of assets that could be liquidated in an emergency. The goal is to avoid situations where medical necessity is constrained by financial inability. The COVID-19 pandemic underscored that health crises can strike anyone, regardless of age or previous health status, making strategic financial planning for such events not just prudent, but essential for long-term financial security and peace of mind.
In conclusion, the decision of “what meds to take for COVID” is far more than a clinical one; it’s deeply interwoven with personal finance, insurance dynamics, and broader economic considerations. By understanding the costs, leveraging available financial tools, and planning proactively, individuals can navigate health crises more effectively, safeguarding both their health and their financial well-being.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.