
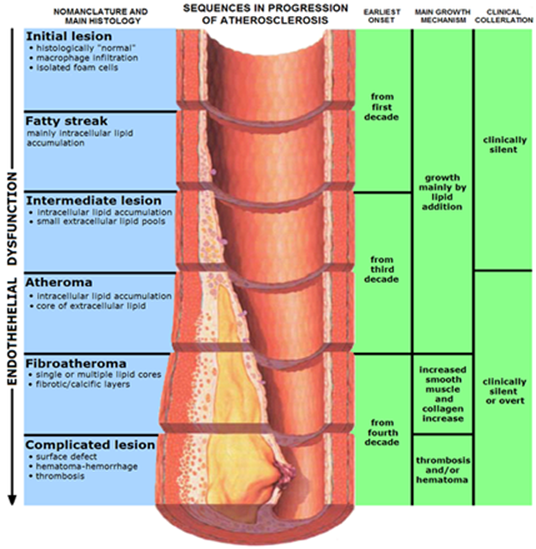
In the lexicon of biological health, the “hardening of the arteries”—clinically known as atherosclerosis—is a silent killer. It occurs when life-sustaining vessels lose their elasticity and become clogged with plaque, eventually restricting the flow of oxygen-rich blood to vital organs. In the world of personal and corporate finance, a strikingly similar phenomenon occurs. Financial hardening is the process by which a portfolio, a business, or an entire economy loses its agility, becomes burdened by “plaque” in the form of debt and illiquid assets, and eventually suffers from a catastrophic lack of cash flow.
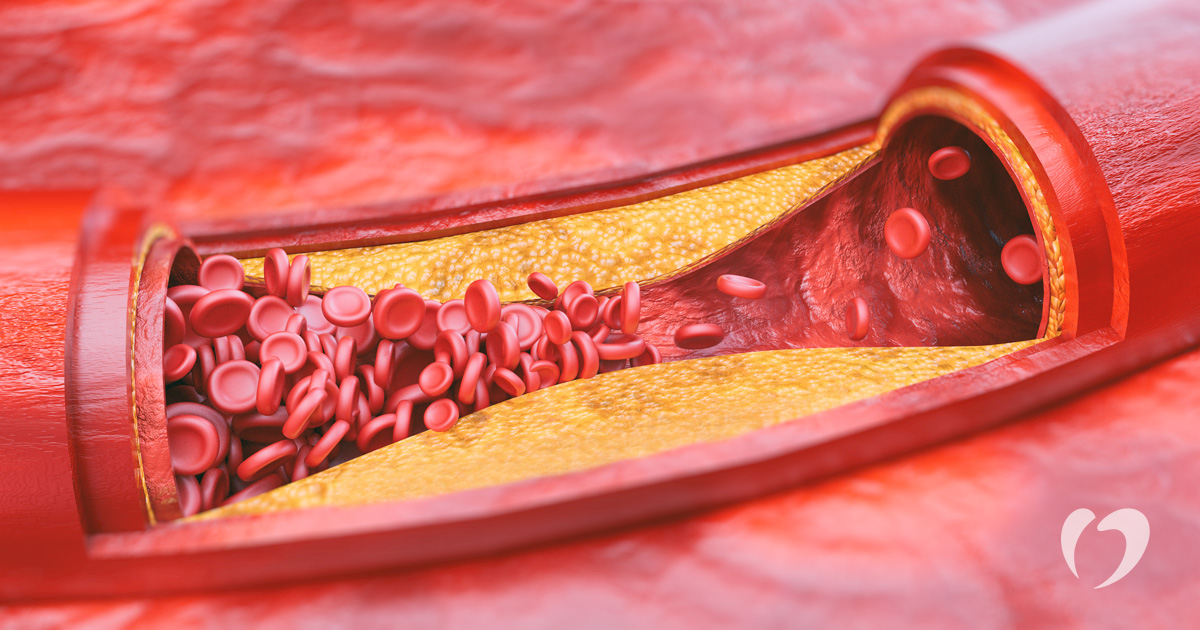
When we ask “what is the hardening of arteries” through a financial lens, we are examining the structural rigidity that prevents capital from moving where it is needed most. For the investor, the entrepreneur, or the wealth manager, identifying the early signs of this financial stagnation is essential to maintaining long-term solvency and growth.
The Biological Metaphor: Cash Flow as the Lifeblood of Wealth
To understand how financial systems “harden,” one must first accept that cash flow is the lifeblood of any economic entity. Without the movement of capital, assets are merely static numbers on a balance sheet. The health of a financial system is not measured solely by its size, but by its “capital velocity”—the speed and efficiency with which money circulates.
Defining Financial Atherosclerosis
In a healthy financial state, capital is fluid. It can be redirected from underperforming assets to high-growth opportunities with minimal friction. However, as an entity matures, it often begins to accumulate “plaque.” This plaque takes many forms: excessive leverage, bloated operational costs, and investments in assets that are difficult to divest. As these elements build up, the financial “vessels” narrow. The entity can no longer react to market shocks or capitalize on sudden opportunities. This is the essence of financial hardening: the transition from an agile, liquid state to a rigid, vulnerable one.
The Vitality of Capital Velocity
Capital velocity is the heartbeat of a thriving portfolio. When an investor’s money is trapped in low-yield, long-term vehicles during a period of high inflation, the “arteries” are effectively constricted. The money is there, but it isn’t “working” or moving. High capital velocity allows for compounding interest to work its magic and for the investor to pivot during economic shifts. When hardening occurs, this velocity drops to zero, and the risk of a “financial heart attack”—a total liquidity crisis—increases exponentially.
The Primary Causes of Financial Rigidity
Just as a poor diet and lack of exercise contribute to medical arterial hardening, specific poor financial habits and structural decisions lead to economic rigidity. Identifying these causes is the first step in a diagnostic process intended to restore financial health.
The Build-up of Toxic Debt Plaque
Debt is perhaps the most significant contributor to financial hardening. While strategic leverage can act as a catalyst for growth, excessive debt acts as a physical obstruction in the cash flow cycle. Every dollar committed to servicing high-interest debt is a dollar that cannot be used for reinvestment or emergency liquidity. Over time, as debt-to-income ratios climb, the financial system becomes brittle. A minor increase in interest rates or a slight dip in revenue can cause the entire structure to fracture because there is no “give” left in the system.
Legacy Costs and Operational Friction
For businesses, the hardening of arteries often manifests as “legacy costs.” These are outdated processes, bloated middle management, and technological debt that have accumulated over decades. Much like calcium deposits in a human artery, these costs are difficult to remove and restrict the company’s ability to innovate. When a company spends 80% of its budget just maintaining the status quo, it has effectively “hardened.” It can no longer pump resources into the R&D “organs” that drive future life.
Regulatory Sclerosis and Market Friction
On a broader scale, the environment in which we operate can contribute to hardening. High transaction costs, complex tax codes, and regulatory “red tape” act as friction points. For the individual investor, this might look like high exit fees on an insurance product or the “lock-up” periods associated with certain private equity funds. While these instruments have their place, an over-concentration in them leads to a hardened portfolio where the cost of moving money exceeds the benefit of the move itself.
Diagnostic Signs of a Hardened Portfolio
Recognizing the symptoms of financial hardening before a crisis occurs is the hallmark of a sophisticated wealth strategy. These signs are often subtle, appearing as a gradual slowdown rather than a sudden halt.
The Liquidity Trap: When Assets Turn to Stone
The most common symptom of financial hardening is being “asset rich but cash poor.” This is the classic liquidity trap. An individual may own millions of dollars in real estate or restricted stock, but if they cannot access $50,000 in cash within 48 hours to cover an emergency or a time-sensitive investment, their financial arteries are dangerously narrow. The “hardness” of an asset is directly proportional to the time and cost required to convert it into usable currency.
Decreasing Returns on Innovation
In a corporate or personal business context, hardening is evident when the “return on effort” begins to diminish. When you find that you are working harder and spending more, yet your net worth or profit margins are stagnant, it is likely that “clogging” has occurred. This stagnation is often caused by an accumulation of small, inefficient expenses and a lack of fresh capital injection into new, high-velocity income streams.
Macro-Economic Hardening: When Whole Markets Lose Their Agility
The phenomenon of hardening is not limited to individuals or companies; entire national economies can suffer from this condition. When an economy hardens, growth slows to a crawl, and the system becomes prone to systemic failure during periods of stress.
The Impact of Interest Rate Volatility
In an era of fluctuating interest rates, a “hardened” economy is one that is over-leveraged on low-cost debt. When the “pulse” of the market (the interest rate) rises, the hardened arteries of the economy cannot expand to accommodate the new costs. This leads to a surge in “zombie companies”—entities that generate just enough cash to service their debt but not enough to grow or innovate. These companies act as a massive blockage in the economic system, preventing capital from flowing to more productive, younger enterprises.
Demographic Shifts and the Slowing of Consumption
Demographics also play a role in the hardening of an economy’s arteries. An aging population tends to move capital into more conservative, “harder” assets like bonds and gold, rather than “fluid” investments like startups and venture capital. This natural shift can lead to a systemic slowdown in capital velocity. Understanding this macro trend is vital for investors looking to position themselves in markets that still retain their youthful elasticity and growth potential.
Financial Angioplasty: Strategies for Restoring Economic Flow
Once financial hardening has been diagnosed, the next step is intervention. Just as medical professionals use angioplasty to clear blocked arteries, financial professionals use specific strategies to restore liquidity and agility.
Deleveraging and Debt Restructuring
The most direct “treatment” for financial plaque is deleveraging. This involves the aggressive pay-down of high-interest debt to free up cash flow. In some cases, it may involve debt restructuring—negotiating better terms to reduce the “pressure” on the system. By thinning out the debt obligations, an individual or business can restore the elasticity of their budget, allowing them to breathe again and react to market changes with confidence.
Embracing Digital Transformation and Fintech
Modern financial tools act as a “vasodilator” for the modern economy. Fintech apps, automated cash-flow management software, and high-yield liquid savings accounts allow for the frictionless movement of money. By automating the “cleaning” of one’s financial vessels—ensuring that idle cash is always being swept into productive vehicles—investors can prevent the build-up of stagnant capital. Digital transformation in business serves the same purpose, cutting through the “calcium” of old-fashioned bureaucracy to allow for faster decision-making and resource allocation.
Maintaining the “Dry Powder” Principle
The ultimate preventative measure against the hardening of financial arteries is the maintenance of “dry powder.” This is the practice of keeping a significant portion of one’s net worth in highly liquid, cash-equivalent assets. While the “opportunity cost” of holding cash is often criticized, its value as a lubricant for the financial system cannot be overstated. Dry powder provides the flexibility to act when others are frozen. It ensures that no matter how narrow the market’s arteries become, your own financial flow remains strong, steady, and ready to capitalize on the next great opportunity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.