
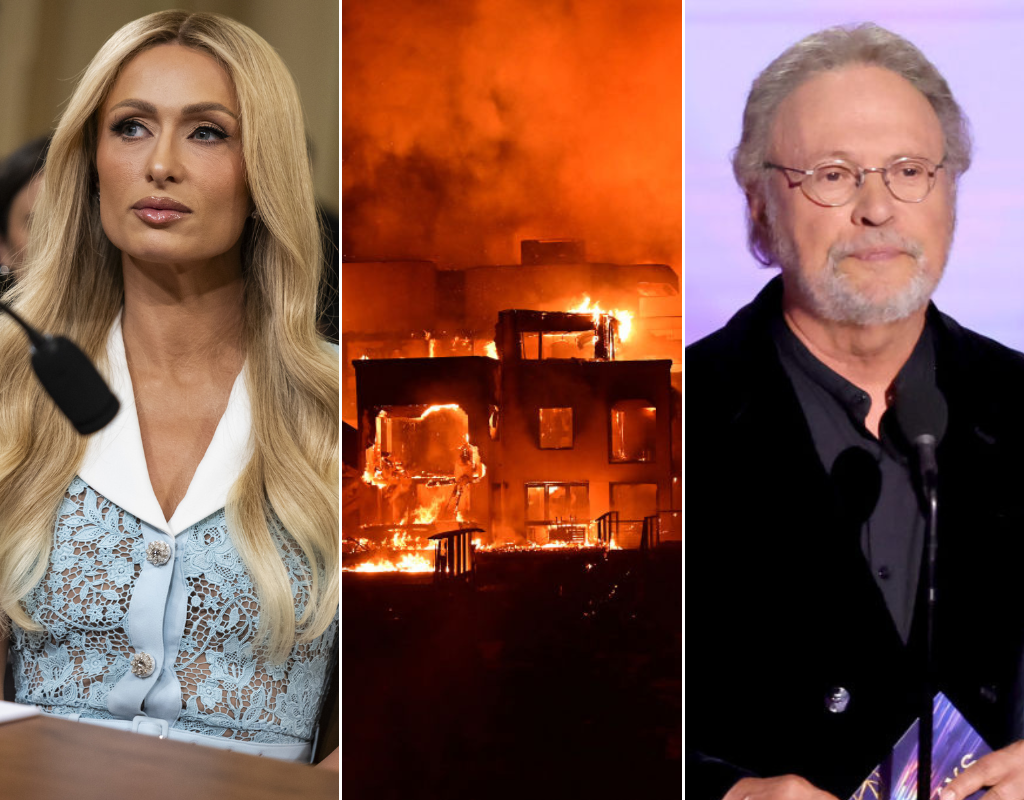
The devastating wildfires that have swept through Southern California over the last decade—most notably the Woolsey, Hill, and Thomas fires—did more than just alter the physical landscape of the region; they fundamentally shifted the financial calculus of luxury real estate. For the world’s most famous individuals, a home in Malibu or the Hollywood Hills is rarely just a residence. It is a significant asset within a diversified portfolio, often representing tens of millions of dollars in equity. When the flames reached the canyons, the losses sustained by celebrities like Gerard Butler, Miley Cyrus, and Neil Young became a high-profile case study in risk management, insurance complexity, and the volatile nature of investing in high-risk environmental zones.

The Economic Magnitude of Celebrity Property Loss
The Woolsey Fire of 2018 serves as the most prominent example of the financial vulnerability of high-net-worth individuals (HNWIs) in the face of climate-driven disasters. This single event destroyed over 1,500 structures and caused billions of dollars in property damage. For celebrities, the losses were staggering not just in sentiment, but in raw capital.
High-Profile Casualties of the Woolsey Fire
Among those who suffered total losses was actor Gerard Butler, who famously shared a photograph of the charred remains of his Malibu home. From an investment perspective, Butler’s loss represented the evaporation of a multi-million dollar physical asset. Similarly, Miley Cyrus and Liam Hemsworth lost their $2.5 million Malibu estate. While $2.5 million may seem modest compared to some mega-mansions, the loss of land value and the cost of “soft costs”—architectural fees, permitting, and environmental assessments—can often exceed the original purchase price during a rebuild.
Other notable figures who lost homes or suffered significant structural damage include Robin Thicke, Camille Grammer, and Neil Young. For Young, this was the second time he had lost a home to a California wildfire, highlighting a recurring risk that many investors are now forced to weigh against the prestige of the zip code.
The Hidden Costs of Total Loss
When a celebrity loses a home, the financial impact extends far beyond the structure itself. Luxury properties are often outfitted with high-end custom finishes, smart home technology, and priceless art collections. For instance, the destruction of specialized recording studios or home theaters involves the loss of depreciable business assets. In the case of musicians like Neil Young or Robin Thicke, the loss of equipment and archives represents a hit to their professional infrastructure, necessitating a complex interplay between personal property insurance and business interruption claims.
Insurance Complexities for Luxury Estates in High-Risk Zones
The loss of celebrity homes has brought the “hard market” of the California insurance industry into the spotlight. For the average homeowner, insurance is a straightforward monthly premium. For those with estates in the Malibu canyons or the hills of Calabasas, insurance is a sophisticated financial instrument that is becoming increasingly difficult to obtain and maintain.
The Rise of Surplus Lines and Private Carriers
Traditional insurers like State Farm and Allstate have significantly pulled back from writing new policies in California’s high-risk fire zones. This has forced celebrities and HNWIs to turn to the “surplus lines” market—non-admitted insurers like Lloyd’s of London or specialized firms like AIG’s Private Client Group and Chubb.
These policies are tailored to the ultra-wealthy, offering “replacement cost” coverage that goes beyond the policy limit to ensure a home can be rebuilt to its original standard, regardless of the current cost of materials. However, the premiums for these policies have skyrocketed, often reaching six figures annually. For an investor, this increased carrying cost significantly reduces the net internal rate of return (IRR) on the property as a real estate investment.
Private Firefighting Crews as Risk Mitigation
A unique financial trend that emerged during the recent LA fires was the deployment of private firefighting crews. High-profile figures, most notably Kim Kardashian and Kanye West during the Woolsey Fire, utilized private firefighters to protect their $60 million Hidden Hills estate.
From a wealth management perspective, the cost of hiring a private crew—often tens of thousands of dollars per day—is viewed as an essential insurance premium. By saving the structure, the owners avoided a years-long insurance settlement process and the potential loss of tens of millions in property value. This “private protection” model is now a standard line item in the security and maintenance budgets for many celebrity estates.

Portfolio Diversification and Asset Recovery
For a celebrity, a home is a liquid asset in a crisis. The financial recovery process following a wildfire is a grueling exercise in accounting and tax strategy. How these individuals handle the aftermath determines whether the fire is a temporary setback or a permanent blow to their net worth.
The 1033 Exchange: A Tax Lifeline
The IRS provides a specific mechanism for those who lose property in a federally declared disaster area: the Section 1033 exchange. Unlike the more common 1031 exchange used in real estate investing, Section 1033 allows a homeowner to defer capital gains taxes on insurance proceeds if those funds are reinvested in “similar or related in service or use” property.
For celebrities who lost homes in the LA fires, this tax code is vital. If an individual receives a $10 million insurance settlement for a home they bought years ago for $2 million, they would normally owe capital gains on the $8 million difference. Section 1033 allows them to roll that entire $10 million into a new property or a massive rebuild without immediate tax friction, preserving their capital for asset replacement.
The “Build Back Better” Financial Trap
Many celebrities choose to rebuild on their original lots, but this is rarely a break-even endeavor. The cost of construction in Southern California has inflated significantly due to labor shortages and new, stringent fire-resistant building codes (Chapter 7A of the California Building Code). A celebrity who lost a home built in the 1990s may find that rebuilding the same square footage today costs 50% to 100% more due to modern requirements for non-combustible materials, specialized ember-resistant venting, and updated landscaping mandates. This “rebuild premium” often requires an infusion of new capital beyond the insurance settlement.
The Impact on the California Luxury Real Estate Market
The recurring nature of these fires has created a “disaster discount” in certain segments of the LA luxury market. While the allure of the coast remains, the financial community is seeing a shift in how these properties are appraised and financed.
Shifting Buyer Sentiment and the “Safe Zone” Premium
In the years following the 2018 fires, real estate data showed a temporary cooling in the Malibu and Topanga markets. Investors and celebrity buyers began looking toward “safer” enclaves that offered similar privacy but lower fire risk, such as certain pockets of Beverly Hills or modernized areas of the Westside.
This has led to a bifurcation in the market:
- Hardened Assets: Properties that have been retrofitted with exterior sprinkler systems, “defensible space” landscaping, and fire-resistant shells command a premium.
- Vulnerable Assets: Older estates that have not been modernized are seeing longer days on market and price reductions, as savvy buyers factor in the high cost of insurance and the potential for total loss.
The Business of Disaster Recovery
Interestingly, the loss of celebrity homes has fueled a niche economy in Los Angeles: disaster consulting. Professional firms now specialize in representing high-net-worth clients in insurance negotiations, ensuring that every custom fixture and piece of high-end crown molding is accounted for in the claim. The financial recovery is no longer just about a check from an agent; it is a full-scale business operation involving forensic accountants, public adjusters, and specialized legal counsel.
Conclusion: The New Price of Prestige
The list of celebrities who lost their homes in the LA fires—from the legendary Neil Young to modern icons like Miley Cyrus—serves as a stark reminder that even the most exclusive real estate is subject to the volatility of the natural world. From a financial standpoint, these events have redefined what it means to own property in Southern California.
The “celebrity home” is no longer a passive investment that simply appreciates over time. It is a high-maintenance asset that requires sophisticated insurance layering, proactive risk mitigation, and a complex tax strategy to survive the inevitable cycle of the California wildfire. As the climate continues to impact the region, the financial wisdom of “buying the view” is increasingly weighed against the escalating costs of protecting it. For the celebrity investor, the fire is not just a physical threat; it is a fundamental challenge to the stability of their physical wealth.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.