
For millions of service members, veterans, Department of Defense civilians, and their families, Navy Federal Credit Union (NFCU) stands as a beacon of financial support. With a mission rooted in serving those who serve our country, NFCU offers a wide array of financial products, including various types of loans designed to meet diverse needs. Navigating the world of personal finance, especially when it involves accessing capital, can seem daunting. This guide will meticulously break down the process of securing a loan from Navy Federal, empowering you with the knowledge to make informed financial decisions and achieve your goals, whether it’s purchasing a home, buying a car, consolidating debt, or funding a personal project.
Understanding Navy Federal Membership and Eligibility
Before you can even consider applying for a loan with Navy Federal, the fundamental requirement is membership. Unlike traditional banks open to the general public, Navy Federal is a credit union, meaning it’s a member-owned financial cooperative. This structure often translates to better rates, fewer fees, and a more personalized service approach, all of which are crucial aspects of smart personal finance.
Who Can Join Navy Federal?
Navy Federal’s membership eligibility is specific, focusing primarily on the military community and their extended families. This includes:
-
Active Duty, Retired, and Veterans: All branches of the U.S. Armed Forces are eligible. This encompasses Army, Marine Corps, Navy, Air Force, Coast Guard, Space Force, and National Guard.
-
Department of Defense (DoD) Civilians: Individuals employed by the DoD, including federal government employees, contractors, and reservists (even if not active duty), are eligible.
-
Family Members: A wide range of family members can join, including spouses, parents, grandparents, siblings, children, grandchildren, and even household members. This expansive definition ensures that the financial benefits extend beyond direct service members.
Understanding these criteria is the very first step in your journey toward obtaining a Navy Federal loan. If you or a family member falls into one of these categories, you’re on the right track. If not, unfortunately, you won’t be able to proceed with a loan application directly with NFCU.
The Importance of Membership Before Applying
The “member-owner” philosophy is central to Navy Federal. You must establish your membership before you can apply for any of their financial products, including loans. This isn’t just a bureaucratic hurdle; it’s how credit unions operate. Your membership signifies your stake in the cooperative, granting you access to its full suite of services and benefits. Attempting to apply for a loan without existing membership will result in an immediate disqualification of your application, highlighting the critical sequence of financial engagement with NFCU.
The Membership Application Process
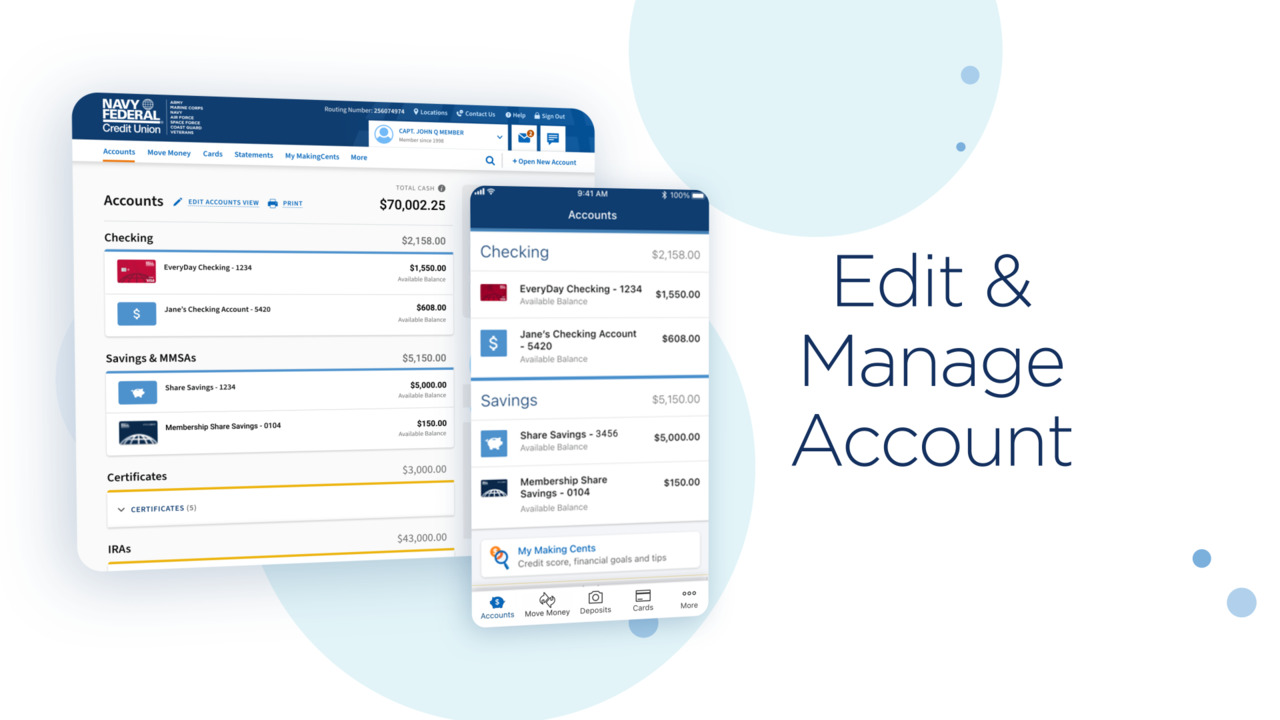
Joining Navy Federal is a straightforward process, typically completed online in minutes. You’ll need to provide some basic personal information, including your Social Security number, a valid government-issued ID (like a driver’s license), and details related to your military or DoD affiliation. You’ll also be required to open a savings account with a minimum deposit, usually just $5, which establishes your share in the credit union. Once your membership is confirmed, you gain access to their online banking platform, customer service, and, most importantly, the ability to apply for loans. This initial investment in membership is a foundational step in leveraging NFCU as a powerful financial tool.
Types of Loans Offered by Navy Federal
Navy Federal offers a comprehensive portfolio of loan products, each designed to address specific financial needs. Understanding these options is key to selecting the right financial solution for your situation, aligning with sound personal finance principles.
Personal Loans
Navy Federal personal loans are versatile financial instruments that can be used for almost any purpose, from debt consolidation to unexpected emergencies, home improvements, or even funding a significant life event. They typically come with fixed interest rates and predictable monthly payments, making them an excellent tool for budgeting and financial planning. Eligibility is often based on your creditworthiness, income, and debt-to-income ratio, all critical factors in assessing your financial health.
Auto Loans
Whether you’re in the market for a new or used vehicle, or looking to refinance an existing auto loan to potentially lower your interest rate, Navy Federal offers competitive auto loan solutions. They often provide pre-approval options, allowing you to shop for a car with confidence, knowing exactly how much you can afford. Their rates are frequently among the most competitive in the market, providing significant savings over the life of the loan. This is a prime example of how leveraging the right financial tool can impact your long-term wealth.
Mortgage Loans
One of the most significant financial commitments an individual makes is purchasing a home. Navy Federal supports its members through various mortgage options, including conventional, VA (Veterans Affairs) loans, FHA (Federal Housing Administration) loans, and even refinance options. VA loans, in particular, are a hallmark of NFCU’s service, offering eligible veterans and service members the opportunity to purchase a home with no down payment and no private mortgage insurance (PMI). Understanding the nuances of these mortgage products is vital for effective long-term financial planning and asset acquisition. They also offer Home Equity Lines of Credit (HELOCs) and Home Equity Loans, allowing members to tap into their home’s equity for various needs.
Student Loans and Other Specialty Loans
Beyond the major categories, Navy Federal also provides solutions for specific financial needs. This includes private student loans to help finance higher education, as well as specialized loans for things like recreational vehicles (RVs), motorcycles, and even boats. These niche products demonstrate Navy Federal’s commitment to being a comprehensive financial partner, offering tailored financial tools for almost every stage of life and desire. While their primary focus remains on consumer loans, their breadth covers most members’ significant financial needs.
The Loan Application Process: Step-by-Step
Once you’re a Navy Federal member and have identified the type of loan that best suits your needs, the next step is the application itself. A structured approach to this process can significantly streamline your experience and improve your chances of approval.
Preparing Your Finances
Before even beginning the application, take time to review and strengthen your financial standing. Lenders, including Navy Federal, assess several key factors:
-
Credit Score: A strong credit score (generally 670 and above, with excellent scores being 750+) indicates a history of responsible borrowing and repayment. Check your credit report for inaccuracies and address any issues.
-
Debt-to-Income (DTI) Ratio: This ratio compares your total monthly debt payments to your gross monthly income. A lower DTI (ideally below 36%, though some lenders go higher for specific loans) signals that you have enough disposable income to comfortably manage new debt.
-
Income Stability: Lenders want to see a consistent and reliable source of income. This demonstrates your ability to make regular payments.
-
Savings and Assets: While not always a direct requirement for all loans, demonstrating a healthy savings cushion can reassure lenders of your financial prudence and ability to weather unexpected expenses.
Gathering Necessary Documentation
Being prepared with the right paperwork can significantly speed up the application process. While specific requirements vary by loan type, generally you’ll need:
-
Proof of Identity: Valid government-issued ID (driver’s license, passport).
-
Proof of Income: Pay stubs (for the last 30-60 days), W-2 forms, tax returns (if self-employed or for mortgage applications), bank statements.
-
Proof of Residence: Utility bills, lease agreement, or mortgage statement.
-
Loan-Specific Documents: For auto loans, details of the vehicle; for mortgages, property information, purchase agreements, etc.
-
Bank Account Information: For setting up direct deposit of funds and/or automatic loan payments.
Online, Phone, or Branch Application
Navy Federal offers flexibility in how you apply for a loan:
-
Online: This is often the quickest and most convenient method. Their secure online portal allows you to complete the application, upload documents, and track its status from anywhere.
-
Phone: You can speak directly with a loan officer by calling their member service line. This is beneficial if you have specific questions or prefer a more guided approach.
-
Branch: Visiting a physical Navy Federal branch allows for face-to-face interaction with a loan officer, which can be helpful for complex applications or if you prefer in-person assistance.
Choose the method that best suits your comfort level and the complexity of your financial situation. Each method is supported by their robust customer service.
What to Expect After Applying
Once your application is submitted, Navy Federal will review your financial information, credit history, and documentation.
-
Initial Decision: For simpler loans like personal or auto loans, you might receive an immediate or rapid conditional approval. Mortgages and more complex loans will naturally take longer.
-
Additional Information Requests: It’s common for lenders to request supplementary documents or clarification on certain details. Respond promptly to these requests to avoid delays.
-
Approval: If approved, you’ll receive a loan offer outlining the terms, interest rate, repayment schedule, and any associated fees. Review this carefully before accepting.
-
Denial: If denied, Navy Federal is required to provide a reason for the denial. This feedback is invaluable, as it highlights areas where you need to improve your financial profile (e.g., credit score, DTI) before reapplying in the future. This is a critical learning opportunity for your financial journey.
Maximizing Your Chances of Loan Approval
Securing a loan is not just about meeting minimum requirements; it’s about presenting yourself as the most creditworthy applicant possible. Strategic financial management can significantly enhance your approval odds with Navy Federal.
Improving Your Credit Score
Your credit score is arguably the most influential factor in loan approval and the interest rate you’ll receive. To improve it:
-
Pay Bills on Time: Payment history accounts for a large portion of your score. Set up automatic payments to avoid missing due dates.
-
Reduce Credit Card Balances: Keep your credit utilization ratio (amount of credit used vs. available) low, ideally below 30%.
-
Avoid Opening Too Many New Accounts: Each new credit application can cause a temporary dip in your score.
-
Check Your Credit Report Regularly: Dispute any errors that could be negatively impacting your score.
-
Maintain a Mix of Credit: A healthy mix of credit (e.g., credit cards, installment loans) shows responsible management of different types of debt.
Managing Your Debt-to-Income Ratio
A high DTI ratio signals to lenders that you may be overextended financially. To lower it:
-
Increase Your Income: Seek opportunities for raises, bonuses, or take on a side hustle.
-
Pay Down Existing Debts: Focus on reducing credit card balances or other high-interest loans before applying for new credit.
-
Avoid Taking on New Debt: Refrain from major purchases on credit leading up to your loan application.
Building a Strong Relationship with Navy Federal
As a credit union, NFCU values its member relationships. Demonstrating loyalty and responsible financial behavior within the institution can indirectly bolster your loan application.
-
Maintain Active Accounts: Regularly use your checking and savings accounts.
-
Set Up Direct Deposit: Having your income directly deposited into your NFCU account provides a clear picture of your financial stability.
-
Utilize Other NFCU Products: Using their credit cards responsibly, for example, builds a positive internal history.
While not a guaranteed path to approval, a strong existing relationship can certainly paint a favorable picture of you as a reliable and engaged member.
Understanding Loan Terms and Conditions
Before signing any loan agreement, meticulously review all terms and conditions. This includes:
-
Interest Rate (APR): Understand if it’s fixed or variable and how it impacts your total repayment.
-
Repayment Schedule: Know your monthly payment amount and the duration of the loan.
-
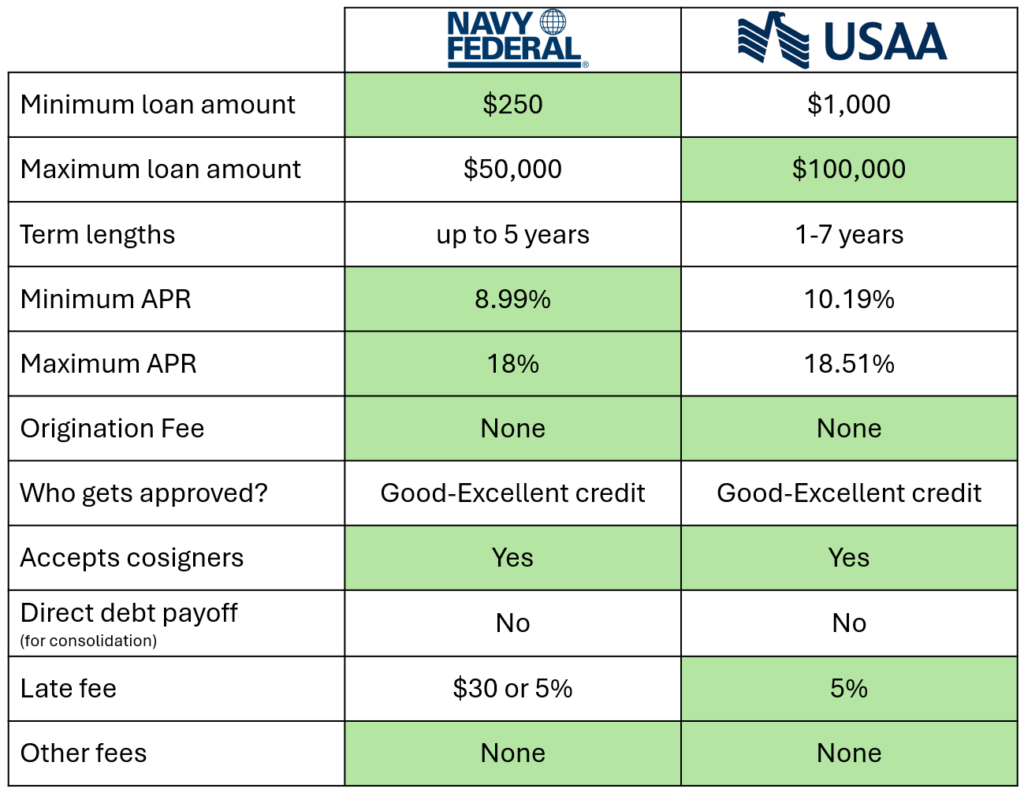
Fees: Be aware of any origination fees, late payment fees, or prepayment penalties (though Navy Federal is known for fewer fees).
-
Collateral: For secured loans (like auto or mortgage), understand what asset is being used as collateral.
This due diligence is a cornerstone of responsible financial management, ensuring you enter into an agreement fully informed and prepared.
Responsible Borrowing and Financial Wellness
Obtaining a loan from Navy Federal is not just about the approval; it’s about responsibly managing that debt and integrating it into your broader financial plan. This commitment to financial wellness is what truly sets members up for long-term success.
Budgeting for Loan Repayments
The moment you take on a loan, its repayment must become an integral part of your monthly budget. Create a detailed budget that accounts for your loan payments alongside all other expenses and income.
-
Automate Payments: Set up automatic transfers from your Navy Federal checking account to ensure payments are always on time. This also often comes with a slight interest rate reduction for some loans.
-
Create a Buffer: Aim to have a small emergency fund that can cover a few months of loan payments in case of unexpected financial setbacks.
-
Track Progress: Regularly review your budget and loan statements to monitor your repayment progress and ensure you’re on track.
Avoiding Common Pitfalls
Even with the best intentions, borrowers can stumble. Be vigilant to avoid common pitfalls:
-
Over-borrowing: Only borrow what you genuinely need and can comfortably afford to repay. Don’t be tempted by the maximum amount offered if it strains your budget.
-
Missing Payments: Late payments incur fees and, more importantly, severely damage your credit score, making future borrowing more difficult and expensive.
-
Ignoring Financial Changes: If your income or expenses change significantly, don’t ignore the impact on your loan. Proactively contact Navy Federal to discuss options if you anticipate repayment difficulties. They often have programs to assist members facing hardship.

Utilizing Navy Federal’s Financial Education Resources
Navy Federal is committed to empowering its members through financial literacy. They offer a wealth of resources, often free of charge, including:
-
Online Articles and Calculators: Tools to help you budget, save, and plan for major life events.
-
Webinars and Workshops: Educational sessions on topics ranging from credit management to home buying.
-
Financial Counselors: Access to experts who can provide personalized guidance and advice.
Leveraging these resources can help you build a stronger financial foundation, not just for managing your current loan, but for lifelong financial wellness and independence.
Securing a loan from Navy Federal Credit Union is a structured process that begins with membership and continues through diligent application and responsible repayment. By understanding eligibility, preparing your finances, choosing the right loan product, and committing to sound financial practices, you can effectively leverage Navy Federal’s offerings as powerful tools to achieve your personal and family financial goals. Remember, financial access is a privilege, and responsible management is the key to maximizing its benefits.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.