
At first glance, the question “how many 1/4 equal 3/4” appears to be a simple arithmetic problem, a relic from early schooling. The answer, of course, is three. Yet, beneath this seemingly straightforward mathematical query lies a profound principle that underpins nearly every aspect of personal finance, investing, business strategy, and wealth creation. It’s a fundamental concept of proportionality, allocation, and understanding parts of a whole – skills absolutely critical for anyone navigating the complexities of the financial world.
In finance, we are constantly dealing with fractions: a quarter of your income for housing, a third of your portfolio in growth stocks, a fifth of your business profit earmarked for reinvestment. Grasping the essence of how many smaller units combine to form a larger whole is not just an academic exercise; it’s a foundational pillar for making informed financial decisions, optimizing resource allocation, and strategically building wealth. This article will delve into how mastering this fractional thinking can transform your financial journey, from managing daily expenses to building a substantial legacy.
The Foundational Math of Financial Literacy: Deconstructing the Whole
Understanding that three quarters make three-quarters of a whole is more than just basic math; it’s the genesis of financial literacy. It’s about comprehending how individual components contribute to a larger sum, a principle that resonates deeply across budgeting, saving, and investing. Without this intuitive grasp, financial planning becomes a series of disjointed numbers rather than a coherent strategy.
From Quarters to Quadrants: Visualizing Financial Proportions
Imagine your total income as a pie. How do you divide it? Many financial experts recommend the 50/30/20 rule: 50% for needs, 30% for wants, and 20% for savings and debt repayment. Each of these percentages is, in essence, a fraction of your whole income. If we convert these to fractions, we are dealing with halves, tenths, and fifths. The “how many 1/4 equal 3/4” question serves as a mental model for breaking down larger financial goals or resources into manageable, understandable segments.
For instance, if your ultimate goal is to save $12,000 in a year, you can visualize this as a whole. Breaking it down, you might ask, “How many quarters ($3,000 segments) do I need to save?” The answer—four—immediately gives you a clear, actionable target for quarterly savings. This approach transforms an intimidating annual goal into a series of achievable milestones, making the path to financial success far less daunting. Visualizing these proportions helps in assessing whether current allocations are optimal or if adjustments are needed to meet specific targets. It’s about seeing your finances not as a singular, overwhelming sum, but as a mosaic of contributing parts.
The Hidden Power of Simple Fractions in Everyday Finance
The seemingly simple arithmetic of fractions plays a crucial, often underestimated, role in everyday finance. From understanding sales discounts (e.g., 1/4 off) to calculating interest rates (e.g., 1/4% monthly), fractions are ubiquitous. For someone managing a side hustle, understanding that 1/4 of their earnings needs to be set aside for taxes, or that 3/4 of their revenue covers operational costs, is critical for sustainable growth.
Even in more complex scenarios like understanding stock splits or dividend yields, the underlying principle remains the same. A stock split of 2-for-1 means each share now represents half the original value, but you own twice as many “halves.” A dividend yield might be presented as a percentage, but at its core, it’s a fraction of the stock price returned to shareholders annually. Recognizing these fractional relationships allows for quicker, more accurate mental calculations and a deeper intuitive understanding of financial products and transactions, empowering individuals to make smarter, more confident choices without always needing a calculator.
Strategic Allocation: Dividing Your Financial Pie
The ability to effectively divide and allocate resources is arguably the most critical skill in personal and business finance. Just as we determine how many 1/4 make up 3/4, we must decide how many “quarters” of our income, investments, or profits are designated for specific purposes. This strategic division is the backbone of sound financial management, ensuring resources are optimally utilized to achieve diverse goals.
Budgeting by Fractions: Ensuring Every Quarter Counts
Budgeting is, at its heart, an exercise in fractional allocation. It’s about consciously deciding how much of your total income (the whole) goes into various categories. Using the simple “1/4 equal 3/4” framework, you might think of your financial life in terms of four major “quarters” or even smaller fractions. For example:
-
One “quarter” for essential living expenses: Rent/mortgage, utilities, groceries.
-
Another “quarter” for discretionary spending: Entertainment, dining out, hobbies.
-
A third “quarter” for savings and investments: Building an emergency fund, retirement contributions.
-
The final “quarter” for debt repayment or specific financial goals: Student loans, a down payment for a house.
While these might not be exact 1/4 allocations, the mindset of dividing your income into defined portions ensures that every dollar has a job. If you find that 3/4 of your income is going towards needs and wants, leaving only 1/4 for savings and debt, this fractional insight immediately highlights an imbalance. It prompts you to ask: “Can I reduce my ‘wants’ quarter to increase my ‘savings’ quarter?” This systematic approach prevents overspending, encourages disciplined saving, and provides a clear roadmap for financial stability and growth.
Investment Portfolios: Balancing Your Financial Quarters
In the world of investing, allocation is paramount to managing risk and maximizing returns. A diversified investment portfolio is essentially a collection of different asset classes, each representing a fraction of your total investment capital. An investor might allocate:
-
1/4 to stable, low-risk assets: Bonds or money market funds.
-
1/4 to blue-chip stocks: Established, less volatile companies.
-
1/4 to growth stocks: Higher-risk, higher-potential return companies.
-
1/4 to alternative investments: Real estate, commodities, or even crypto.
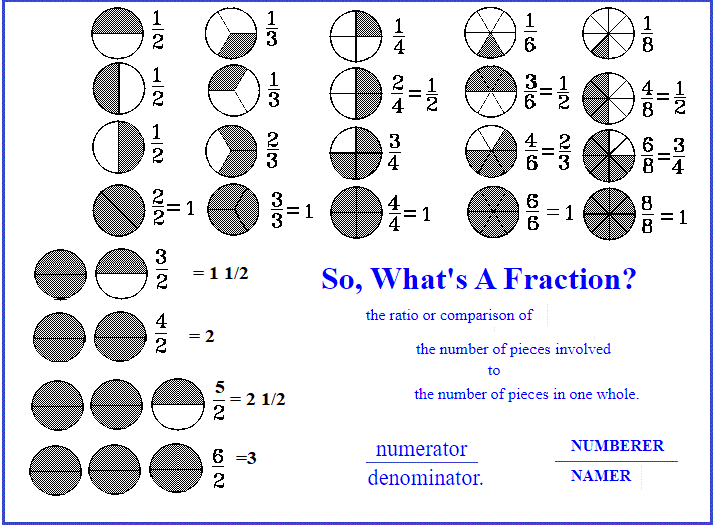
The answer to “how many 1/4 equal 3/4” becomes crucial here. If 3/4 of your portfolio is in high-risk growth stocks, you’ve essentially committed three of your four “quarters” to a volatile segment. While potentially rewarding, this concentration significantly increases your exposure to market downturns. Understanding these fractional representations allows investors to assess their risk profile accurately and adjust their allocations to align with their financial goals and comfort level. A balanced portfolio ensures that a downturn in one “quarter” does not decimate the entire “pie,” allowing other segments to potentially offset losses or continue growth.
Scaling Your Wealth: From Small Shares to Significant Stacks
The power of fractional thinking extends beyond mere allocation; it’s fundamental to understanding how wealth accumulates over time. Just as three 1/4s combine to form 3/4 of a whole, consistent small financial actions, when compounded, can lead to substantial wealth. This concept is vital for long-term financial planning, from retirement savings to building generational wealth.
The Compounding Effect: How Your “1/4s” Multiply Over Time
Compounding interest is often hailed as the “eighth wonder of the world,” and at its core, it’s about fractions multiplying themselves. When you invest 1/4 of your paycheck each month, and that investment earns a return, that return also starts earning returns. It’s like adding another “1/4” to your principal, which then grows, and then adds another, and so on. The cumulative effect of these seemingly small, consistent fractions is exponential.
Consider starting to save early. Even if you only save 1/4 of what someone else starts saving later, the extended period of compounding means your smaller, earlier “quarters” will likely grow into a larger sum. This illustrates that time and consistent fractional contributions are often more powerful than sporadic large investments. The consistent discipline of setting aside that “1/4” and allowing it to compound is the secret sauce to turning modest contributions into significant wealth over decades. It’s the practical application of understanding how individual units, consistently added and allowed to grow, eventually form a much larger whole than the sum of their initial parts.
Incremental Progress: Building Financial Freedom One Fraction at a Time
Financial freedom rarely happens overnight. It’s the result of incremental progress, of consistently putting one “quarter” after another towards your goals. Whether it’s paying down debt, building an emergency fund, or saving for a down payment, each small step is a fraction of the larger journey. Understanding that “how many 1/4 equal 3/4” applies here means recognizing that consistent, even small, actions accrue to substantial progress.
If you have a large debt, paying an extra 1/4 of your regular payment each month might seem insignificant, but over time, these additional “quarters” dramatically reduce the principal and interest paid, bringing you closer to debt-free status much faster. Similarly, if your goal is to generate online income, starting with a side hustle that earns you an extra 1/4 of your monthly expenses can be the first step towards financial independence. The journey involves continually adding those financial “quarters” until the sum reaches your desired “whole” – be it an emergency fund, a retirement nest egg, or a passive income stream.
Beyond the Basics: Advanced Fractional Thinking in Business and Investing
The principles of fractional thinking, derived from understanding how many 1/4 equal 3/4, scale up to sophisticated financial strategies in business and advanced investing. From dividing equity to managing complex risk, the core concept of proportionality and allocation remains critical.
Equity Stakes and Profit Sharing: The Business of Fractions
In business, particularly for startups and partnerships, understanding equity and profit sharing is a direct application of fractional thinking. When multiple founders or investors are involved, determining who owns what percentage of the company is literally dividing the “whole” company into fractions. One partner might own 1/2, another 1/4, and an early investor the remaining 1/4.
Similarly, profit sharing plans involve distributing a fraction of the company’s profits among employees or partners. If a company decides to share 3/4 of its annual profits, and you are entitled to 1/12 of that share, you’re looking at a multi-layered fractional calculation. These scenarios demand a clear understanding of how fractions are assigned, combined, and distributed to ensure fairness, transparency, and proper incentives within a business structure. Mismanaging these fractional allocations can lead to significant disputes and business failure.
Risk Management: Diversifying Your Financial “Quarters”
Advanced risk management in finance is fundamentally about diversifying your exposure across different assets, geographies, and strategies—essentially, distributing your financial “quarters” to mitigate potential losses. A sophisticated investor might not just diversify across asset classes but also within them. For instance, rather than putting 3/4 of their stock allocation into a single industry, they might divide it: 1/4 in tech, 1/4 in healthcare, 1/4 in consumer goods.
Even hedging strategies involve fractional offsetting—using a small fraction of your portfolio to protect a larger fraction from adverse movements. Understanding how various fractions of your overall wealth are exposed to different risks allows for the construction of resilient portfolios that can weather economic storms. It’s about building a financial structure where a loss in one “quarter” does not cripple the entire financial house, ensuring stability and long-term sustainability.
In conclusion, the seemingly elementary question “how many 1/4 equal 3/4” unlocks a powerful mindset crucial for financial mastery. It teaches us to break down complex financial landscapes into manageable parts, to allocate resources strategically, to appreciate the cumulative power of incremental progress, and to manage risk with precision. From personal budgets to intricate investment portfolios and business ventures, the ability to think in fractions is not merely a mathematical skill but a fundamental pillar of financial intelligence, guiding us toward greater control, stability, and prosperity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.