
In the contemporary financial landscape, the reliability of a digital banking platform is as critical as the solvency of the institution itself. For millions of Bank of America customers, the sudden inability to access account balances, transfer funds, or utilize mobile payment features is more than a minor inconvenience—it is a disruption to their financial equilibrium. When a major institution like Bank of America experiences technical difficulties, it triggers a cascade of questions regarding security, liquidity, and the stability of our digital-first monetary system.
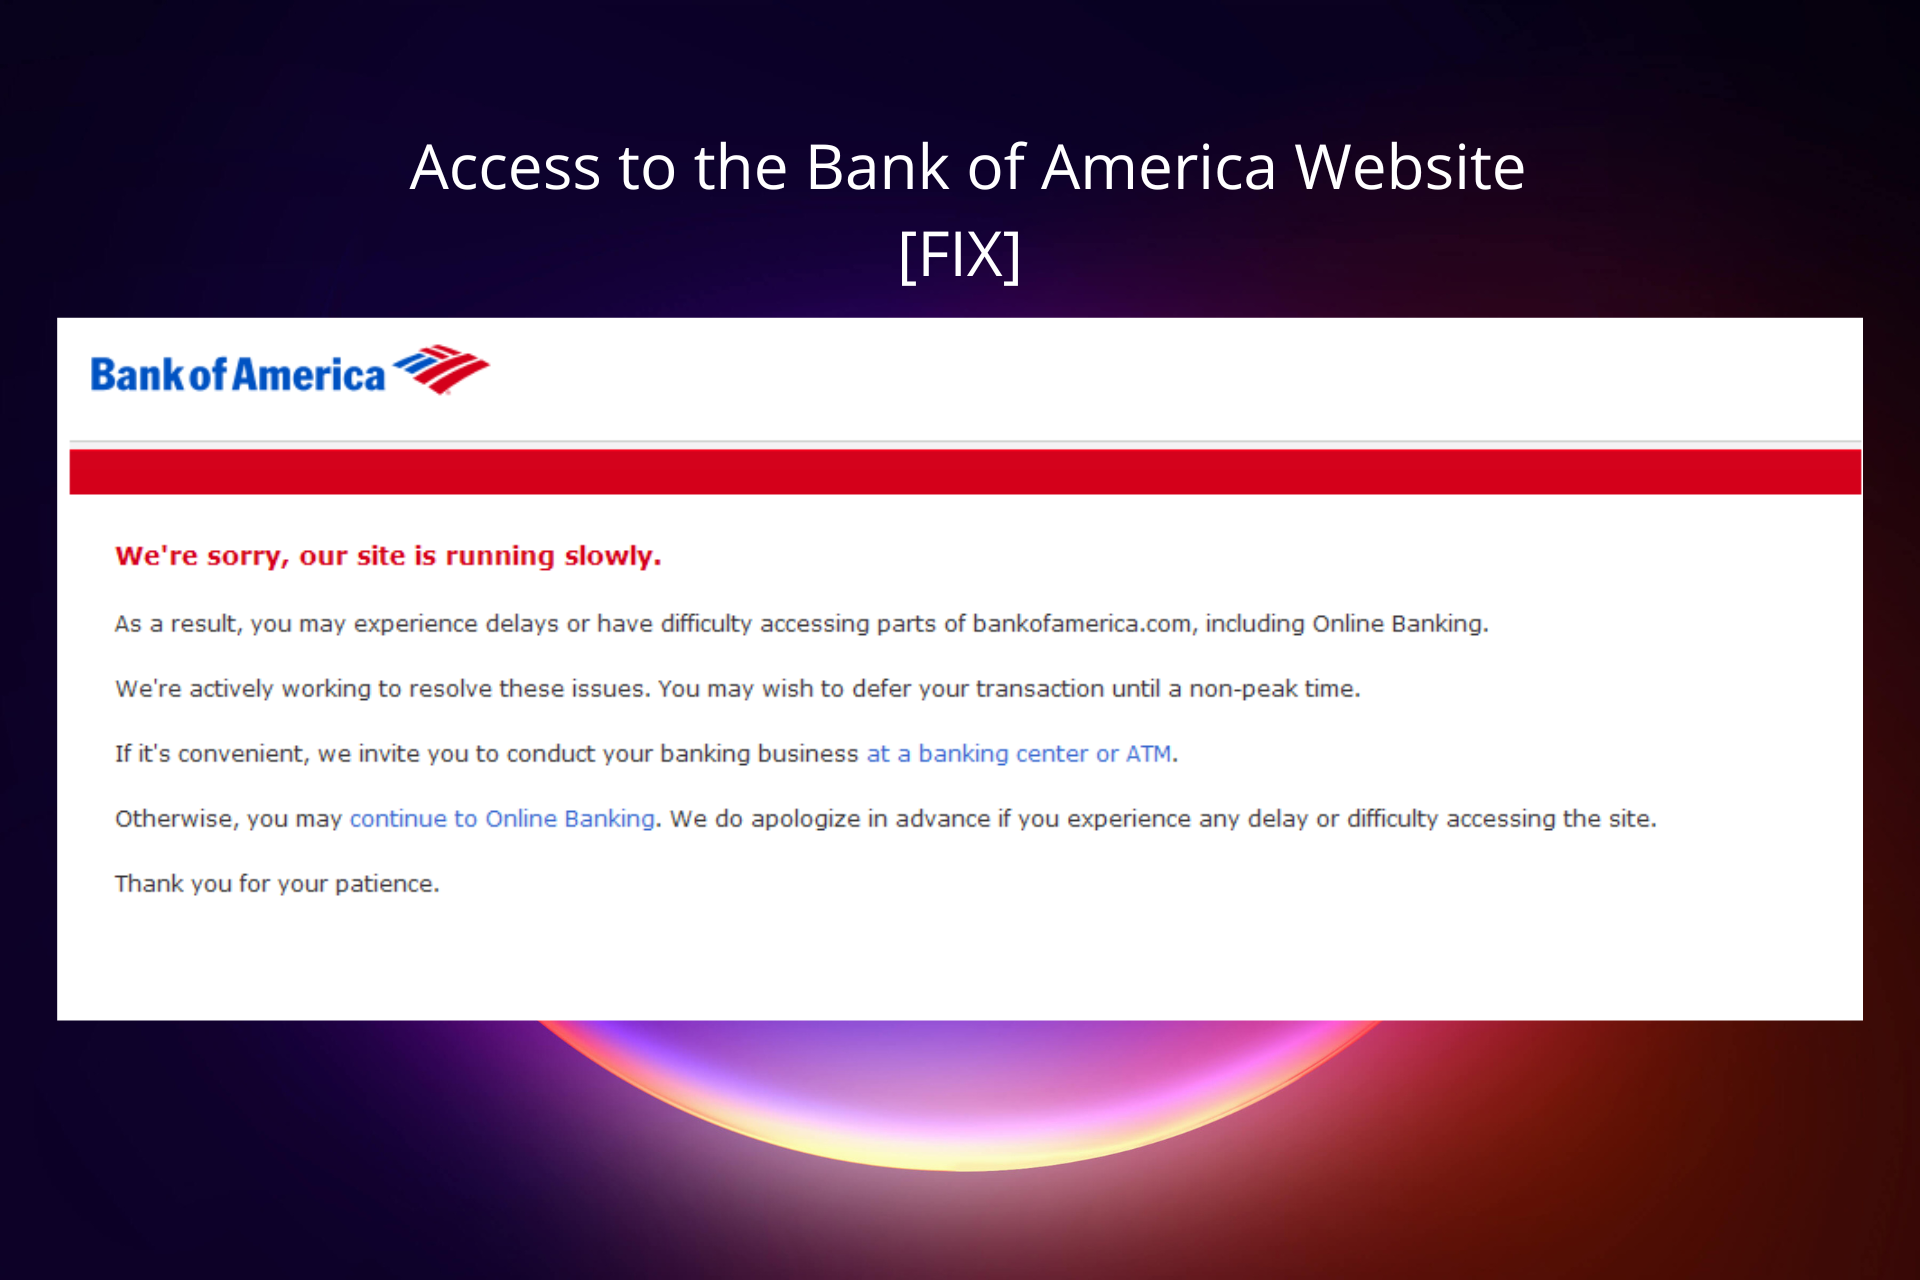
Understanding why these outages occur requires a look into the complex intersection of legacy infrastructure, high-frequency digital traffic, and the rigorous security protocols that protect trillions of dollars in assets. More importantly, for the individual consumer, it necessitates a strategic approach to personal finance that ensures a single technical glitch does not lead to a full-scale financial crisis.
The Mechanics of Modern Banking Outages: Why Even Giants Falter
Bank of America manages one of the largest retail banking footprints in the world. Its digital infrastructure must process millions of transactions per second while simultaneously defending against sophisticated cyber threats. When the platform stops working, the root cause usually falls into one of three financial-technical categories: scheduled maintenance, traffic surges, or systemic infrastructure updates.
The Legacy System Hurdle
One of the primary reasons major financial institutions face downtime is the sheer complexity of their “back-end” architecture. Many global banks still operate on core systems built decades ago using languages like COBOL. While these systems are incredibly robust for ledger management, they were not originally designed for the 24/7, high-velocity demands of mobile app interactions. When Bank of America attempts to integrate modern front-end features—such as real-time Zelle payments or AI-driven budgeting tools—into these legacy frameworks, the friction can cause “timeouts” or complete server failures.
Peak Transaction Windows
Financial activity is not distributed evenly throughout the month. Bank of America often sees significant traffic spikes on the 1st and 15th of the month, corresponding with standard payroll cycles. On these days, millions of users log in simultaneously to verify direct deposits, pay bills, and transfer funds to savings. If the bank’s server capacity is not dynamically scaled to meet this surge, the system may throttle connections, leading to the familiar “internal server error” messages.
Security Protocols and False Alarms
In some instances, what appears to be an outage is actually a proactive security measure. If the bank’s monitoring systems detect a coordinated distributed denial-of-service (DDoS) attack or an unusual pattern of login attempts, they may temporarily shut down specific gateways to protect customer data. In the world of high-finance, a temporary loss of access is always preferred over a catastrophic data breach.
The Financial Ripple Effects: What Happens to Your Money During Downtime
The concern during a Bank of America outage is rarely about whether the money is “gone”—the FDIC and internal ledgers ensure that balances remain accurate—but rather about the loss of liquidity. For the modern consumer, time is money, and the inability to move capital can have real-world financial consequences.
Impact on Scheduled Payments and Bill Pay
Most users rely on automated “Bill Pay” systems to manage utilities, mortgages, and credit card payments. If an outage occurs on a day when a high-value payment is scheduled to be processed, there is a risk that the transaction may be delayed. While banks generally honor the “effective date” of a payment if the delay was caused by their own internal systems, the consumer may still face anxiety regarding late fees or impacts on their credit score.
The Zelle and Peer-to-Peer Problem
Bank of America is a co-owner of Zelle, a service integrated directly into its mobile app. When the app is down, peer-to-peer liquidity evaporates. For small business owners or freelancers who utilize these services for immediate payment, an outage can halt operations, delay the purchase of inventory, or disrupt the payment of subcontractors. The reliance on integrated fintech means that a bank outage is no longer just about checking a balance; it’s about the total stoppage of commerce.

Liquidity Crunches and Emergency Access
The most immediate danger of a banking outage is the inability to access emergency cash. If the mobile app and website are both offline, users may also find that their debit cards face intermittent issues at the Point of Sale (POS) or that ATMs are unable to communicate with the central server to authorize withdrawals. This highlights a critical vulnerability in the move toward a cashless society: the total dependence on a functioning digital bridge between the consumer and their capital.
Navigating an Active Outage: Tactical Steps for the Account Holder
When you realize Bank of America is not working, your immediate priority should be maintaining financial continuity. Rather than waiting for the system to restore, proactive steps can mitigate the risk of missed payments or lost access to funds.
Verification of the Outage
Before assuming your account has been compromised, check third-party monitoring sites and social media. If thousands of users are reporting similar issues, the problem is systemic rather than specific to your credentials. This avoids the frustration of attempting to reset passwords or contact fraud departments during a time when phone lines are likely overwhelmed by thousands of other callers.
Alternative Transaction Channels
Often, when a mobile app is down, the browser-based online banking portal may still be functional, or vice-versa. Additionally, telephone banking—a largely forgotten relic of the pre-smartphone era—often operates on a separate system. Dialing the bank’s automated customer service line can allow you to check balances, confirm that a deposit has posted, or even initiate transfers when the digital interface is unresponsive.
Utilizing Secondary Liquidity
This is where the importance of a multi-bank strategy becomes apparent. If your primary debit card is declined due to a Bank of America outage, having a secondary credit card from a different issuer (such as Chase, American Express, or a local credit union) ensures that you can still complete essential purchases. In the world of personal finance, “redundancy” is a form of insurance.
Building a Resilient Financial Infrastructure: Beyond the Single-Bank Strategy
The recurring nature of digital disruptions at major institutions serves as a wake-up call for personal financial management. Relying on a single institution for all your financial needs—checking, savings, mortgage, and credit—creates a “single point of failure” in your life.
The Three-Institution Framework
To ensure maximum financial resilience, experts recommend a three-institution framework:
-
The Primary Operating Bank: A large national bank like Bank of America for everyday checking and broad ATM access.
-
The High-Yield Reserve: An online-only bank (like Ally or Marcus) for emergency savings. These institutions often have different server architectures and are less likely to go down at the same time as a major retail bank.
-
The Local Credit Union: A local institution that provides a physical fallback and personalized service. If a national digital network fails, a local credit union may still be able to provide manual cash withdrawals or over-the-counter services.
Decoupling Payments from Banking
Another strategy to mitigate the impact of an outage is to decouple your recurring payments from your primary checking account. By using a credit card from a different issuer to pay for monthly subscriptions and utilities—and then paying that credit card bill once a month—you create a buffer. If Bank of America is down on the day your electric bill is due, the credit card processes the payment regardless, and you can settle the balance with the bank once the system is back online.

The Importance of Hard Documentation
While we live in a digital age, maintaining a “paper trail” or its digital equivalent is vital. Regularly downloading your transaction history and monthly statements to a secure offline drive or a secondary cloud service ensures that if a major outage leads to a data discrepancy, you have the evidence required to rectify the situation with the bank’s ombudsman or the Consumer Financial Protection Bureau (CFPB).
In conclusion, while Bank of America outages are usually temporary and resolved within hours, they expose the fragility of our interconnected financial systems. By understanding the technical reasons behind these failures and implementing a strategy of financial redundancy, consumers can ensure that their personal economy remains functional even when the giants of the banking world stumble. A robust financial plan is not just about how much money you earn, but how reliably you can access and deploy that money when it matters most.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.