
Discovering that your bank branch is closed when you urgently need access to services can be a frustrating experience. Whether it’s to deposit a check, discuss a loan, or resolve an account issue, an unexpected closure can throw a wrench into your financial plans. For customers of one of the largest financial institutions in the United States, Bank of America, understanding the reasons behind a closure and knowing how to navigate such situations is crucial for maintaining seamless financial management.
Bank of America, like all major financial institutions, operates within a complex framework of federal regulations, standard business practices, and occasional unforeseen circumstances. While most closures are predictable and publicly communicated, others can be sudden and localized. This article delves into the various reasons why a Bank of America branch might be closed, outlines the financial implications for customers, and provides practical strategies for managing your finances effectively, even when brick-and-mortar services are temporarily unavailable. From national holidays to localized emergencies and technical disruptions, we’ll explore the full spectrum of possibilities and equip you with the knowledge to maintain control over your financial life, regardless of branch accessibility.
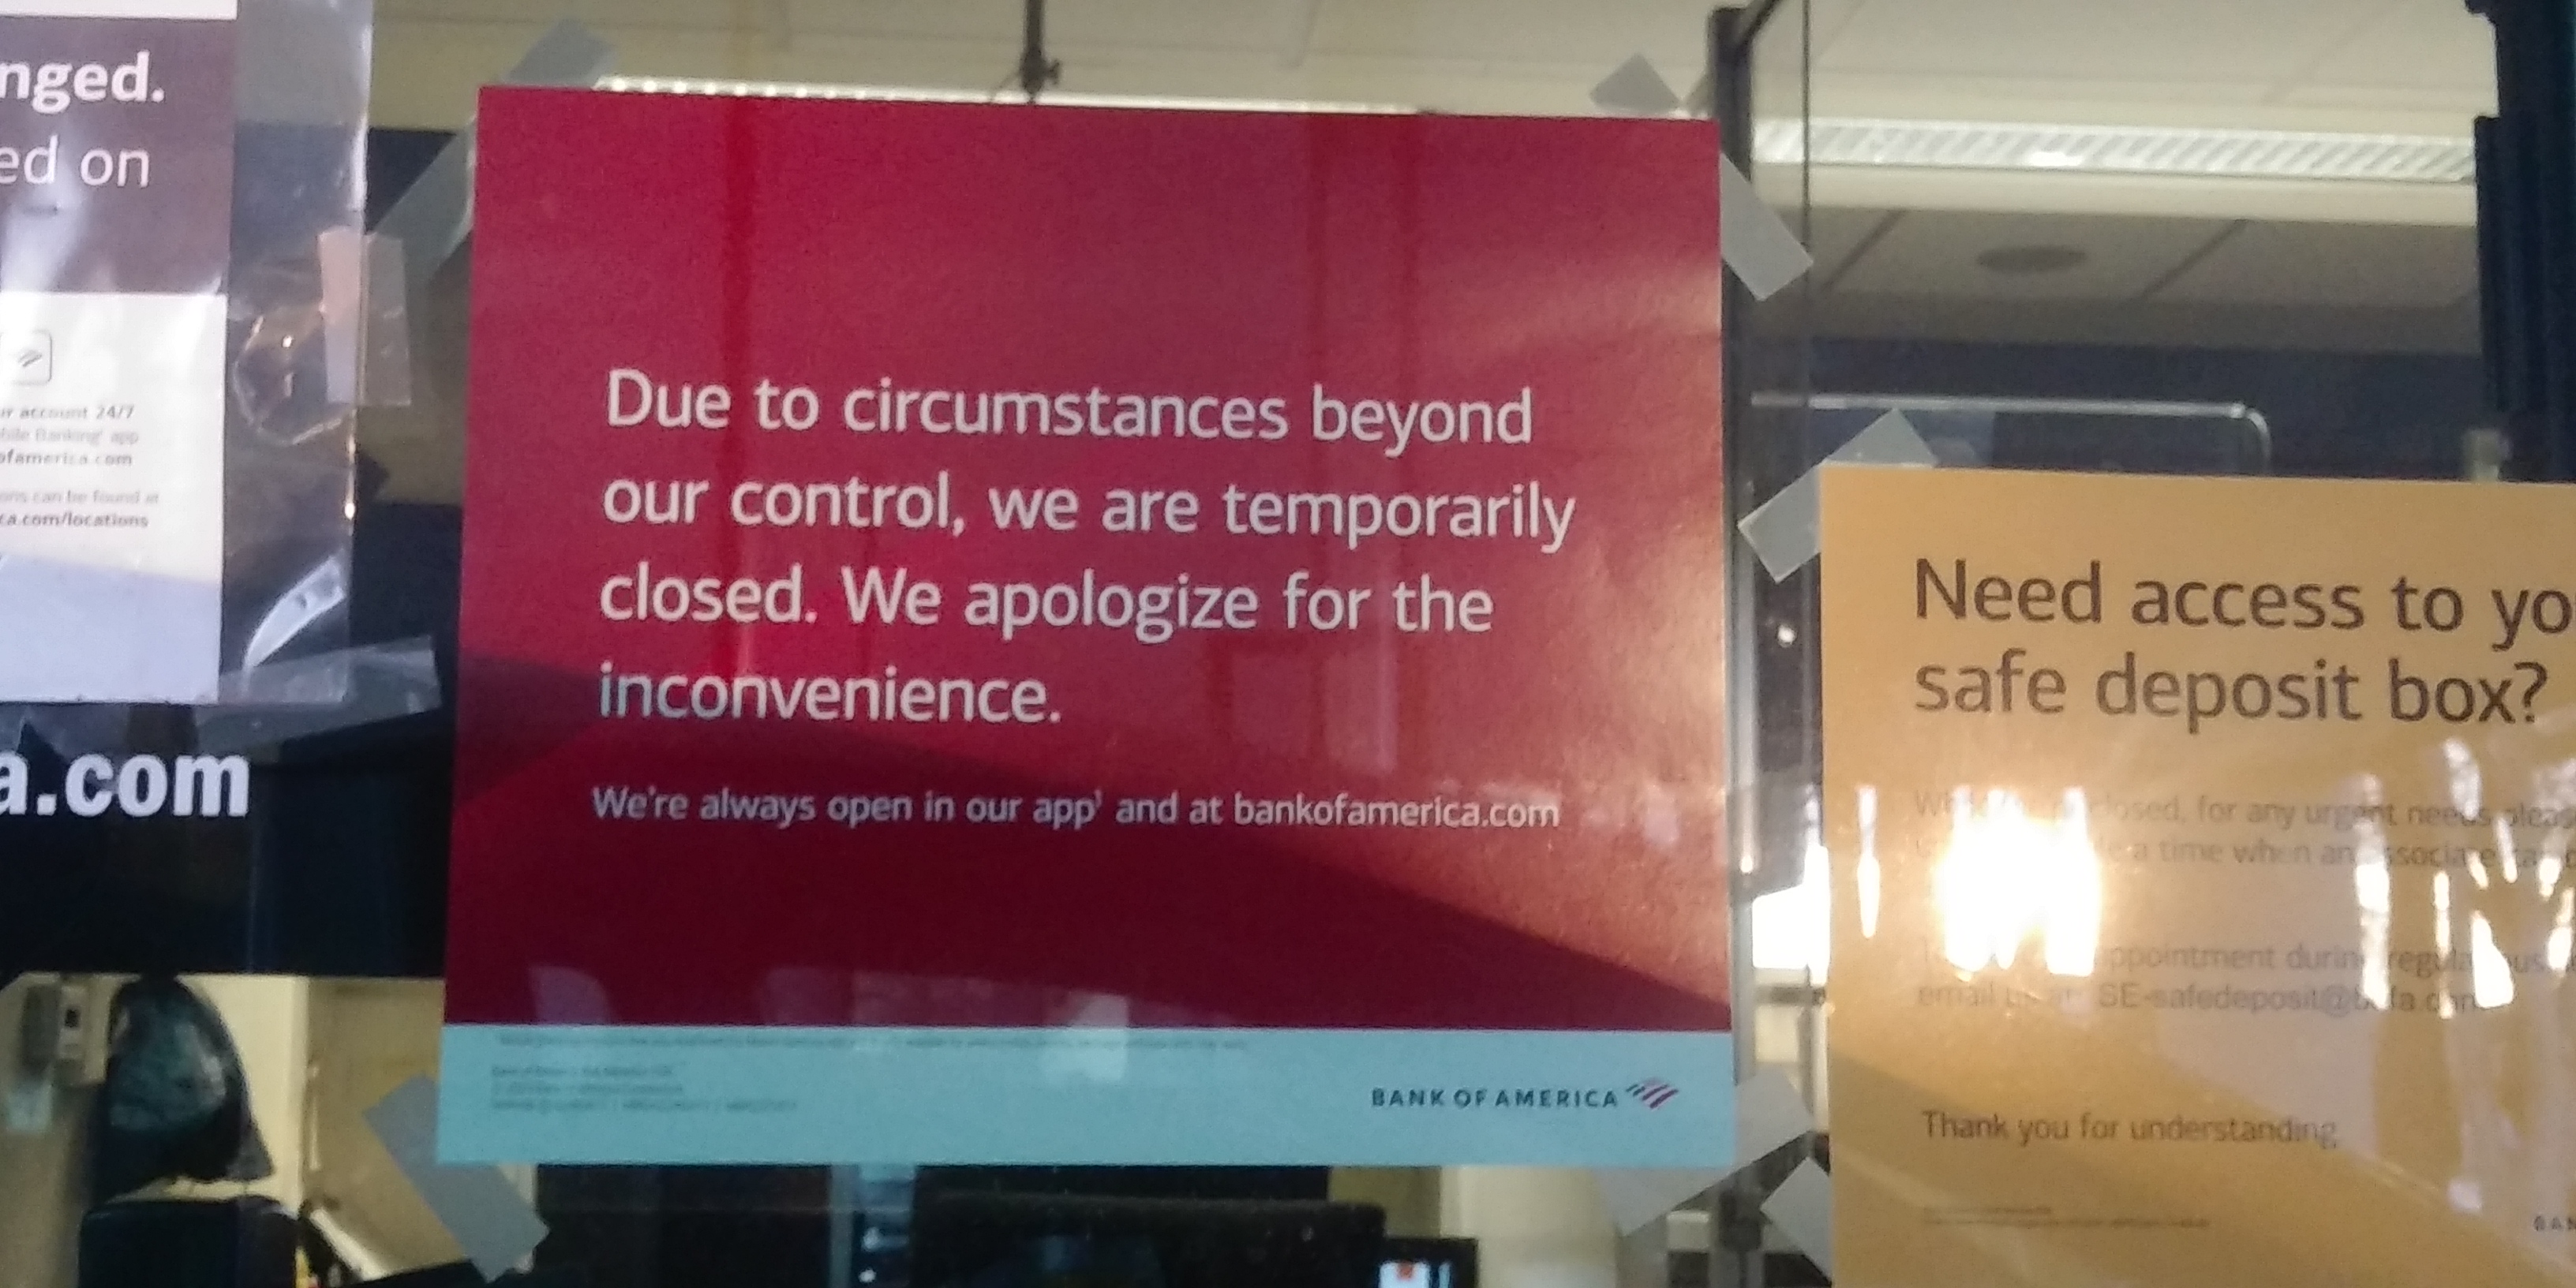
Understanding Standard Banking Closures and Operating Hours
The most common reasons for a Bank of America branch closure are typically predictable and aligned with established schedules that govern most financial institutions. These planned closures are designed to provide staff with well-deserved breaks and to standardize banking operations across the nation. Understanding these routine patterns is the first step in avoiding unexpected inconveniences.
Federal Holidays and Their Impact
The primary reason for a widespread Bank of America closure is often a federal holiday. The Federal Reserve System, which oversees the nation’s banking infrastructure, observes ten federal holidays annually. On these days, most banks, including Bank of America, close their branches, and certain financial transactions, such as check clearing and wire transfers, may be delayed. Holidays like New Year’s Day, Martin Luther King, Jr. Day, Presidents’ Day, Memorial Day, Juneteenth, Independence Day, Labor Day, Columbus Day, Veterans Day, Thanksgiving Day, and Christmas Day all typically result in branch closures. While the physical branches are closed, digital banking platforms and ATMs usually remain operational, providing essential services. However, it’s vital to remember that any transactions initiated on a federal holiday will often not be processed until the next business day, which can impact payment due dates or critical fund transfers. This adherence to the federal holiday schedule ensures uniformity across the financial sector and allows banking employees to participate in national observances. For customers, proactive planning around these dates is essential, especially for time-sensitive financial activities.
Weekend Closures and Standard Operating Days
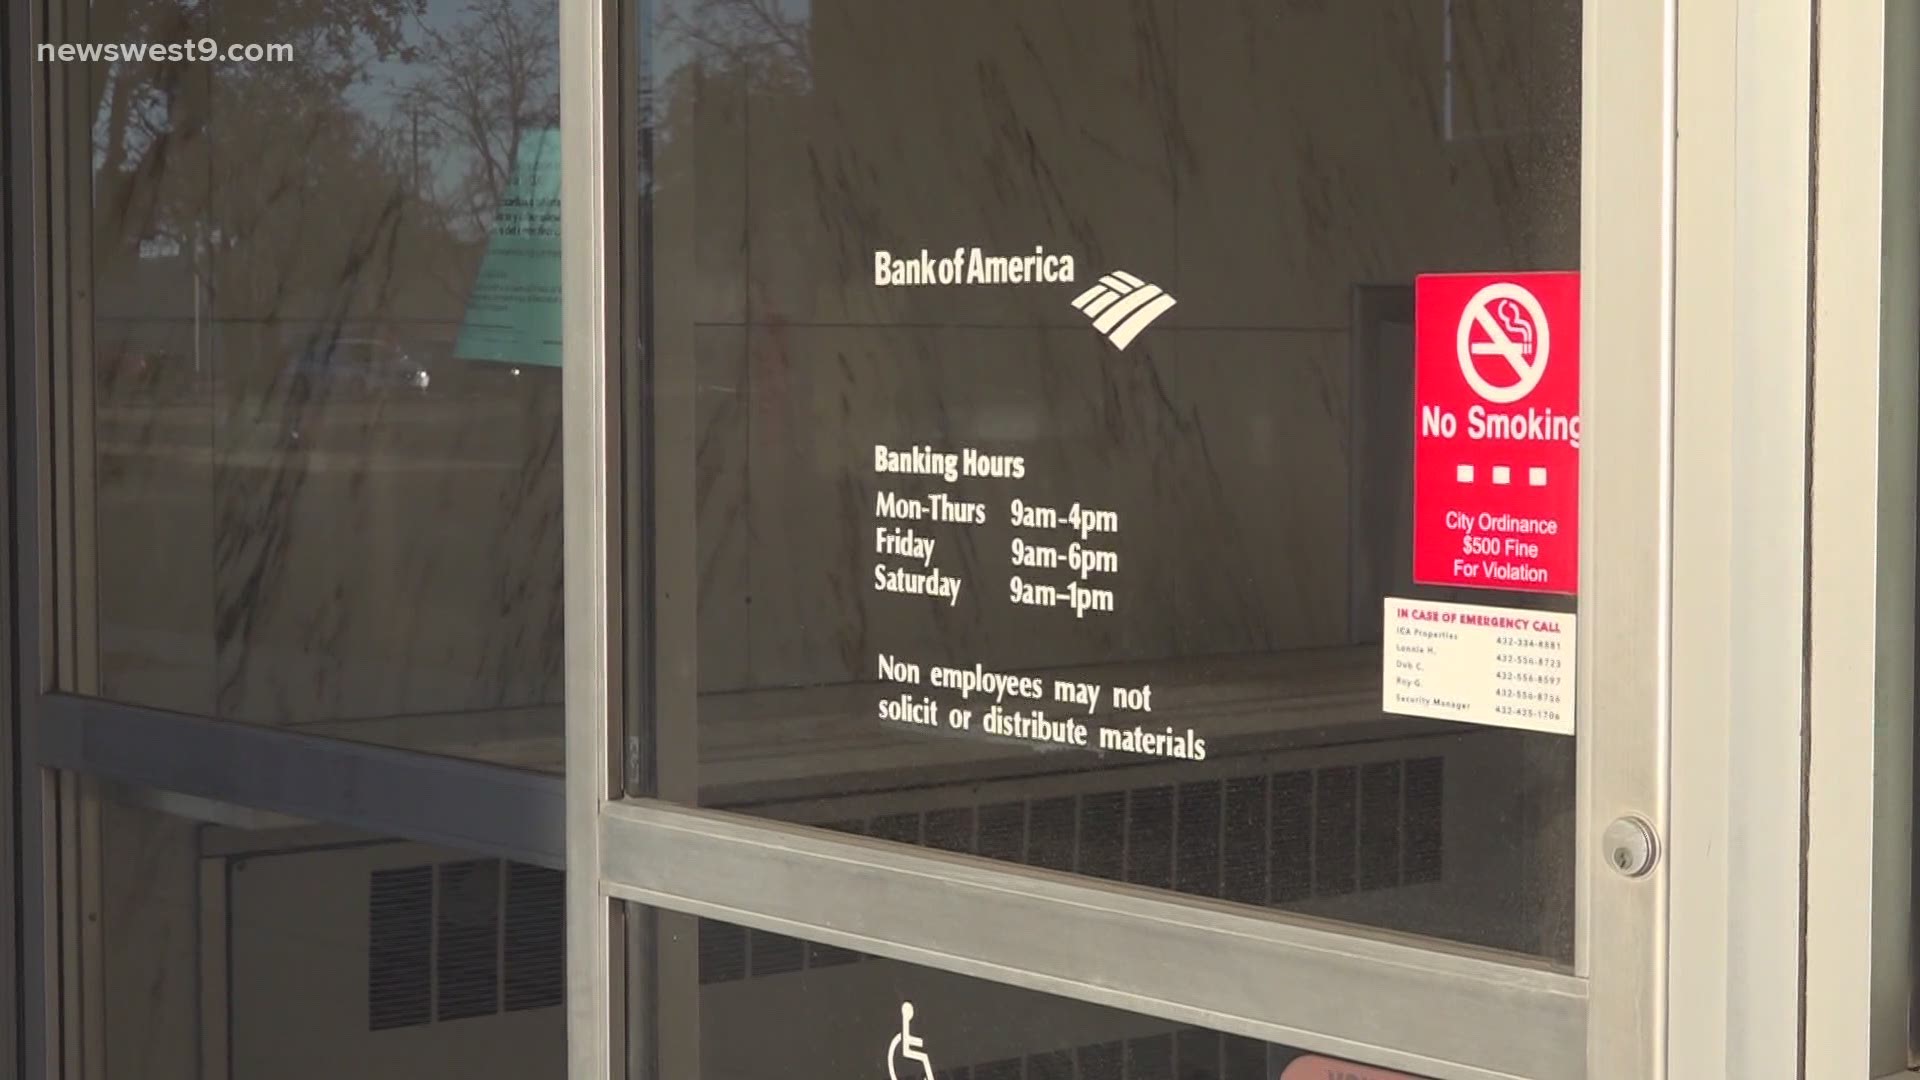
Beyond federal holidays, the standard operating model for Bank of America, like most banks, includes weekend closures. Branches are typically open Monday through Friday, with specific hours that can vary by location. Saturdays often see reduced hours, and Sundays are almost universally non-operating days for branch lobbies. These weekend closures are part of the conventional banking schedule, allowing for operational maintenance, staff rest, and alignment with general business practices. While branches are closed, the expectation is that customers will utilize the vast array of digital and automated services available. Online banking portals, mobile apps, and automated telephone banking systems provide 24/7 access to account information, balance checks, bill payments, and transfers. ATMs are also readily available for cash withdrawals and deposits. It’s crucial for customers to be aware of their specific branch’s operating hours, as these can sometimes differ based on location, population density, and local demand. Planning your in-person banking activities for weekdays is always advisable to ensure access to full-service support.
Branch-Specific vs. System-Wide Closures
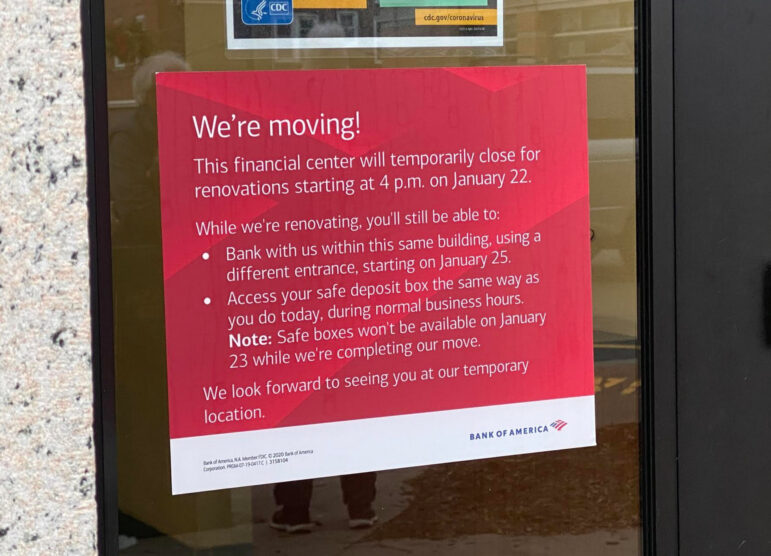
It’s also important to distinguish between a branch-specific closure and a system-wide shutdown. While federal holidays trigger system-wide closures, other reasons might only affect a single branch or a limited number of locations. A particular Bank of America branch might close for localized reasons such as renovations, severe local weather events, unexpected staffing shortages, or even temporary security concerns. These localized closures are often communicated via local signage, updates on the bank’s website branch locator, or through local news channels if the event is significant. In contrast, a system-wide closure implies that all Bank of America branches across a region or the entire country are affected, which is far less common and typically reserved for federal holidays or extremely rare, widespread emergencies or technical outages. Understanding this distinction helps customers determine the scope of the closure and assess alternative options. If only one branch is closed, another nearby branch might be open, whereas a system-wide closure necessitates reliance on digital or ATM services across the board.
Unforeseen Circumstances: When Banks Close Unexpectedly
Beyond the routine schedule of federal holidays and weekends, banks can occasionally close due to unexpected and often unavoidable circumstances. These closures, while less common, can be more disruptive precisely because they are unpredictable. They range from natural phenomena to technical glitches, each presenting its own set of challenges for customers.
Technical Glitches and System Downtime
In our increasingly digital world, technical issues can lead to temporary bank closures or service interruptions. A major system outage at Bank of America, affecting its internal networks or customer-facing platforms, could necessitate a temporary shutdown of physical branches to prevent further complications or to allow technicians to address the issue without customer interference. These types of closures are often the result of hardware failures, software bugs, cyber-security incidents, or network connectivity problems. While banks invest heavily in robust IT infrastructure and redundancy, no system is entirely immune to downtime. During such events, not only might branches be closed, but online banking, mobile apps, and even ATMs could also be affected. The bank’s priority during a technical glitch is to restore services safely and efficiently, often communicating updates through its official website, social media channels, and customer service lines. For customers, the inability to access funds or execute transactions electronically during such a period can be highly inconvenient, underscoring the importance of having some emergency cash on hand and understanding alternative payment methods.
Natural Disasters and Emergency Situations
Natural disasters represent another significant cause for unexpected bank closures. Hurricanes, blizzards, floods, wildfires, or even severe local thunderstorms can render a branch inaccessible or unsafe for both employees and customers. In such scenarios, Bank of America prioritizes the safety of its staff and the community. Closures might be mandated by local authorities, or the bank might choose to close branches preemptively or reactively to ensure safety, assess damage, or facilitate recovery efforts. For instance, during a major hurricane threat, branches in the projected path might close days in advance. Emergency situations, such as local civil unrest, power outages, or public health crises (like the early days of the COVID-19 pandemic), can also trigger temporary closures. In these cases, the closures are often localized and depend entirely on the specific nature and severity of the event. Bank of America typically works closely with local authorities and provides updates on its website regarding affected branch locations and expected reopening times.
Staffing Issues or Branch-Specific Circumstances
Occasionally, a particular Bank of America branch might experience a temporary closure due to unforeseen internal challenges. This could include sudden staffing shortages due to illness, local emergencies affecting employees, or scheduled but unannounced maintenance that requires the branch to be empty. While less common for an entire business day, short-term closures or reduced hours can occur without extensive prior public notice. Similarly, a branch might close temporarily for security reasons, such as during a police investigation in the vicinity or if there’s a perceived threat that necessitates immediate action to protect assets and personnel. These closures are usually highly localized and temporary, with the bank aiming to resume normal operations as quickly as possible. In such instances, customers might find a sign on the door, or they may need to check the bank’s website or contact customer service for information on alternative nearby branches or the estimated reopening time. Such circumstances, though rare, highlight the dynamic nature of managing large-scale operations.
Navigating Bank Closures: Financial Strategies and Alternatives
When a Bank of America branch is closed, whether expectedly or unexpectedly, it doesn’t mean your financial world comes to a halt. In today’s interconnected banking landscape, numerous alternatives and strategies exist to help you manage your money effectively and avoid disruptions. Proactive planning and an understanding of available tools are key.
Digital Banking: Your 24/7 Access
The most powerful tool in your arsenal against branch closures is Bank of America’s digital banking platform. Both the online banking portal and the mobile app offer a comprehensive suite of services accessible 24 hours a day, 7 days a week, from virtually anywhere. Through these platforms, you can check account balances, review transaction history, pay bills, transfer funds between accounts, send money to others via Zelle, and even deposit checks remotely using your smartphone’s camera. Many other services, such as setting up alerts, managing recurring payments, and accessing statements, are also available digitally. For most routine transactions that previously required a trip to a physical branch, digital banking provides a convenient and efficient solution. Familiarizing yourself with these tools is not just a backup plan for closures; it’s a fundamental aspect of modern personal finance management, offering unparalleled flexibility and control over your accounts.
ATM Services and Cash Access
When digital solutions aren’t sufficient, Bank of America’s extensive network of ATMs provides crucial physical access to funds and basic banking services. ATMs allow you to withdraw cash, deposit checks and cash, transfer funds between linked accounts, and check balances. This is particularly vital during closures when you need immediate access to physical currency or need to make a deposit that cannot wait for digital processing. Bank of America has thousands of ATMs strategically located across the country, often outside branch locations, at retail stores, and in other accessible areas. It’s always a good idea to know the location of several ATMs near your home and workplace. For urgent cash needs, even if a Bank of America ATM isn’t immediately available, you can often withdraw cash from your Bank of America debit card at other bank ATMs (though network fees may apply from the other bank, and potentially from Bank of America depending on your account type).
Planning Ahead for Financial Needs
The best defense against the inconvenience of bank closures is proactive financial planning. If you know a federal holiday is approaching, anticipate any urgent banking needs you might have during that period. Process critical payments, make necessary deposits, or withdraw cash in advance. For recurring payments, consider setting up automated bill pay through your online banking portal to ensure they are always processed on time, regardless of branch status. For larger financial decisions or complex transactions that typically require in-person consultation, schedule appointments well in advance, keeping an eye on the bank’s holiday schedule. Maintaining a small emergency fund in an easily accessible form (e.g., a modest amount of cash or funds in a separate checking account with a different institution) can also provide a crucial buffer during unexpected service interruptions, ensuring you’re not left stranded without immediate financial liquidity.
Contacting Customer Support
If you encounter an unexpected closure or have urgent questions that cannot be resolved through digital channels or ATMs, Bank of America’s customer support remains a vital resource. While branches may be closed, customer service lines typically operate with extended hours, if not 24/7, even on holidays. You can reach out via phone to inquire about branch reopening times, seek assistance with specific transactions, or get information on alternative banking solutions. The bank’s official website also often provides real-time updates on branch closures due to emergencies or technical issues. In addition, Bank of America’s social media channels can be a source of information and a way to reach out for general guidance, though account-specific issues should always be handled through secure, direct channels like phone or secure messaging within your online banking portal. Knowing how to quickly connect with customer support can provide peace of mind and help resolve urgent issues when physical access is unavailable.
The Financial Impact of Bank Closures on Customers
While bank closures might seem like a mere inconvenience, they can have tangible financial implications for individuals and businesses, especially if not anticipated or managed effectively. Understanding these potential impacts allows for better preparation and mitigation strategies.
Managing Urgent Transactions and Payments
The most immediate impact of a bank closure is the inability to perform urgent transactions. Imagine needing to make a critical loan payment on its due date, deposit a large check to cover an impending expense, or initiate a wire transfer for a real estate closing. If the branch is closed and digital limits or capabilities are insufficient, these time-sensitive financial obligations can be jeopardized. Missed payments can lead to late fees, damage to credit scores, or even more severe penalties. For businesses, the inability to process payroll, receive payments from clients, or disburse funds to suppliers can disrupt operations and strain relationships. While digital banking and ATMs mitigate some of these issues, certain complex transactions or those exceeding daily limits often still require teller assistance. This highlights the importance of understanding your bank’s digital capabilities and limits before an urgent need arises during a closure.
Business Finance Implications
For small and medium-sized businesses, bank closures can present significant operational challenges. Businesses often rely on daily cash deposits, access to business accounts for large transactions, and in-person consultations for lines of credit or other financial services. If a branch is closed, a business might face delays in depositing cash receipts, impacting cash flow, or be unable to process critical transactions necessary for daily operations. This can lead to difficulties in paying employees, suppliers, or managing inventory. Businesses that handle large volumes of cash, such as retail stores or restaurants, can find themselves holding significant amounts of cash outside the security of a bank vault, posing a security risk. Furthermore, for businesses with complex financial needs or those requiring specific documents or approvals from a bank officer, a closure can halt progress on important initiatives, potentially resulting in lost revenue or missed opportunities.
Direct Deposit and Payment Processing Delays
Even if a physical branch closure doesn’t directly affect your ability to access your funds via digital channels, it can still lead to delays in payment processing. While most direct deposits (like paychecks) are scheduled and processed electronically regardless of branch status, the final availability of funds can sometimes be tied to banking business days. If a payment is scheduled to clear on a federal holiday, for example, the funds might not become fully available until the next business day. Similarly, checks deposited on a holiday or weekend might experience an additional day’s hold before clearing. This can be problematic for individuals who live paycheck-to-paycheck or for businesses relying on immediate access to deposited funds. Understanding the nuances of “business days” for various transaction types is crucial. While a closure might not directly prevent the initiation of a digital payment, it can certainly impact the settlement and availability of funds, requiring careful attention to payment schedules and cutoff times.
Looking Ahead: Preparing for Future Banking Accessibility
The world of banking is constantly evolving, with digital transformation playing a pivotal role in how customers interact with their financial institutions. Preparing for future accessibility means embracing these changes and adopting proactive strategies to ensure your financial needs are always met, regardless of branch operational status.
Embracing Digital Financial Tools
The future of banking is undeniably digital, and the best way to prepare for potential branch closures is to fully embrace Bank of America’s online and mobile banking platforms. Regularly using these tools helps you become proficient in managing your accounts, making payments, and conducting transfers without needing to visit a physical location. Explore features like mobile check deposit, Zelle for instant money transfers, online bill pay, and digital budgeting tools. Many banks are also incorporating AI-powered chatbots and virtual assistants to provide immediate support and answer common queries, further reducing the reliance on in-person interactions. By becoming comfortable and adept with digital banking, you empower yourself with 24/7 access to your finances, significantly mitigating the impact of any branch closure, whether planned or unexpected. This shift isn’t just about convenience; it’s about building resilience into your personal financial management strategy.
Diversifying Banking Relationships and Payment Methods
While Bank of America offers a vast array of services, considering a diversified approach to your financial relationships can add an extra layer of security and accessibility. Having accounts with more than one financial institution – perhaps a primary checking account with Bank of America and a secondary savings or checking account with a credit union or a fully online bank – can provide backup options during outages or localized closures. If one bank’s systems are down or its branches are closed, you might still have access to funds or services through another. Similarly, diversifying your payment methods beyond traditional banking channels, such as utilizing peer-to-peer payment apps, digital wallets, or even having a credit card as an emergency backup, ensures you have multiple avenues for transactions. While Bank of America is a robust institution, having alternative financial pathways can be a prudent strategy, especially for critical transactions or urgent cash needs.
Staying Informed and Utilizing Bank Communication Channels
Finally, staying informed is paramount. Bank of America, like all responsible financial institutions, makes efforts to communicate closures and service interruptions through various channels. Regularly checking the bank’s official website for holiday schedules and service alerts, subscribing to email notifications, or following their official social media accounts can provide timely updates. Utilizing the branch locator tool on the Bank of America website or mobile app to check the real-time status and operating hours of nearby branches is also highly recommended before making a trip. In the event of an emergency or widespread technical issue, news media outlets will often report on significant banking disruptions. Proactive engagement with these communication channels ensures that you are always aware of your bank’s accessibility and can plan your financial activities accordingly, minimizing disruption and maintaining control over your money.
In conclusion, while a “closed today” sign on your Bank of America branch can be frustrating, understanding the underlying reasons and leveraging the array of modern banking tools available can transform a potential inconvenience into a manageable situation. From knowing holiday schedules to embracing digital banking and planning ahead, staying financially agile is key to navigating the occasional unreachability of a physical branch.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.