
The seemingly simple mathematical query, “which fraction is equal to 4,” might at first appear elementary, a question perhaps best suited for a basic math class. Yet, beneath its unassuming surface lies a foundational concept that profoundly underpins nearly every aspect of personal finance, investing, and business management. Understanding the equivalence of fractions, decimals, and whole numbers is not merely an academic exercise; it is an essential skill for decoding financial information, making informed decisions, and ultimately building wealth. In the world of money, perceiving that 8/2, 12/3, 16/4, or even 400/100 all resolve to the same value—4—is a powerful lesson in seeing beyond the immediate representation to grasp the true magnitude and relationship of figures.
The Unseen Math in Everyday Finance
Our financial lives are constantly shaped by numbers, many of which are fractions in disguise. From the interest rate on a loan to the percentage allocation in a budget, these fractional relationships dictate our financial health and potential.
From Basic Fractions to Complex Financial Decisions
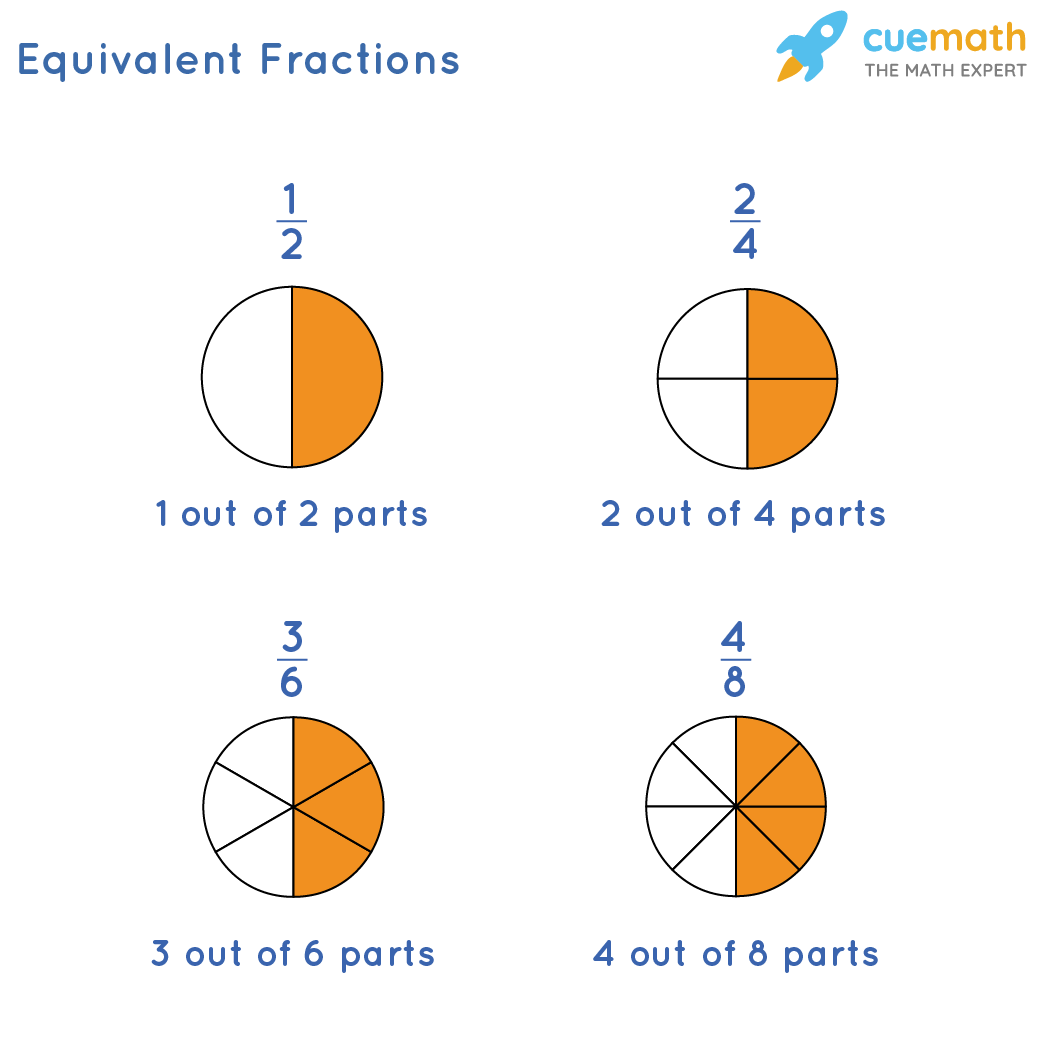
The ability to identify various fractions that equal a whole number like 4 is an intuitive demonstration of equivalence. This principle is not confined to textbooks; it’s a bedrock concept in finance. Consider a common financial goal: doubling your money. This isn’t just about reaching “2 times” your initial investment; it’s about understanding that your original capital now represents 1/2 of your new total, or that your growth represents 1/1 of your original. Similarly, aiming for your investment to be “equal to 4” times its original value means targeting a 300% return, transforming your initial sum into four equivalent parts. This perception allows for a nuanced understanding of growth, risk, and target setting.
Financial literacy demands that we look beyond the surface of a number. A stock price isn’t just a whole dollar amount; it’s a fraction of the company’s total valuation. Your monthly income isn’t just a single figure; it’s a collection of fractions allocated to various expenses, savings, and investments. The strength of this foundational understanding allows individuals to confidently navigate complex financial statements, interpret investment reports, and accurately manage their personal budgets. Without this basic grasp of fractional relationships, financial data can appear opaque and overwhelming, hindering effective decision-making.
Understanding Value: More Than Just Whole Numbers
In personal finance, recognizing that value can be expressed in various forms is crucial. A single dollar, for instance, can be thought of as four quarters, ten dimes, or one hundred pennies. Each denomination represents a fraction of the whole, yet they all carry the same inherent value. This understanding translates directly to managing assets, debts, and income.
When you allocate half your income to housing, you are dealing with the fraction 1/2. When a quarter of your investment portfolio is in bonds, you are working with 1/4. These aren’t just arbitrary divisions; they are precise fractional components that define your financial structure. This fractional perspective enables a more granular and precise approach to financial planning. It allows for the segmentation of financial resources, understanding how each part contributes to the overall financial picture, and identifying areas for adjustment. Whether it’s carving out a specific percentage for savings or diversifying an investment portfolio, the ability to conceptualize parts of a whole is indispensable.
Decoding Financial Ratios and Proportions
Financial ratios are the language of business and investment analysis, and they are inherently fractional. These ratios provide critical insights into a company’s health, an individual’s financial stability, or an investment’s potential.
Investment Returns and Growth Rates
Investment returns are almost universally expressed as percentages, which are direct derivatives of fractions. A 5% annual return means your investment grew by 5/100 of its value over the year. Understanding compound interest—the process where your earnings also begin to earn—is a prime example of how even small fractional gains, consistently applied over time, can lead to substantial “whole number” growth. The formula for Return on Investment (ROI) is a classic fractional calculation: (Gain from Investment – Cost of Investment) / Cost of Investment. If your goal is for an investment to reach a value “equal to 4” times its original size, you’re targeting a 300% return—a significant fractional increase that requires strategic planning and a keen understanding of compounding.
Debt Management and Loan Structures
Fractions play a critical role in understanding and managing debt. Lenders use debt-to-income (DTI) ratios, which are simple fractions, to assess your ability to manage monthly payments and repay borrowed money. For example, a DTI of 36% means that 36/100 of your gross monthly income is committed to debt payments. Understanding interest rates as a fraction of the principal borrowed (e.g., 6% interest means 6/100 of the principal is charged annually) is fundamental to comprehending the true cost of borrowing.
For larger loans like mortgages, each payment you make is divided into two fractions: one portion goes towards interest, and the other towards reducing the principal. Early in a loan term, a larger fraction of your payment often covers interest, while a smaller fraction reduces the principal. As the loan matures, these fractions shift, with a larger portion going towards principal repayment. Recognizing these fractional allocations is key to understanding the trajectory of your debt and making informed decisions about accelerated payments or refinancing.
Budgeting for the Real World
Budgeting is, at its core, an exercise in fractional allocation. Popular budgeting rules, such as the 50/30/20 rule (50% for needs, 30% for wants, 20% for savings and debt repayment), are perfect illustrations of fractional thinking applied to personal finance. Each percentage represents a specific fraction of your total income that should be directed towards different categories.
Understanding these fractions allows you to allocate your income purposefully, ensuring that essential needs are met, desired expenses are accounted for, and financial goals like savings and investments are prioritized. Whether it’s dedicating a “fraction” of every paycheck to an emergency fund or setting aside a specific percentage for discretionary spending, this structured approach to money management empowers individuals to maintain control over their finances and work towards their objectives effectively.
The Power of Equivalence in Financial Planning
The ability to recognize and convert between fractions, decimals, and percentages is a powerful tool in financial planning, enabling quick analysis and clear decision-making.
Converting Percentages to Actionable Insights
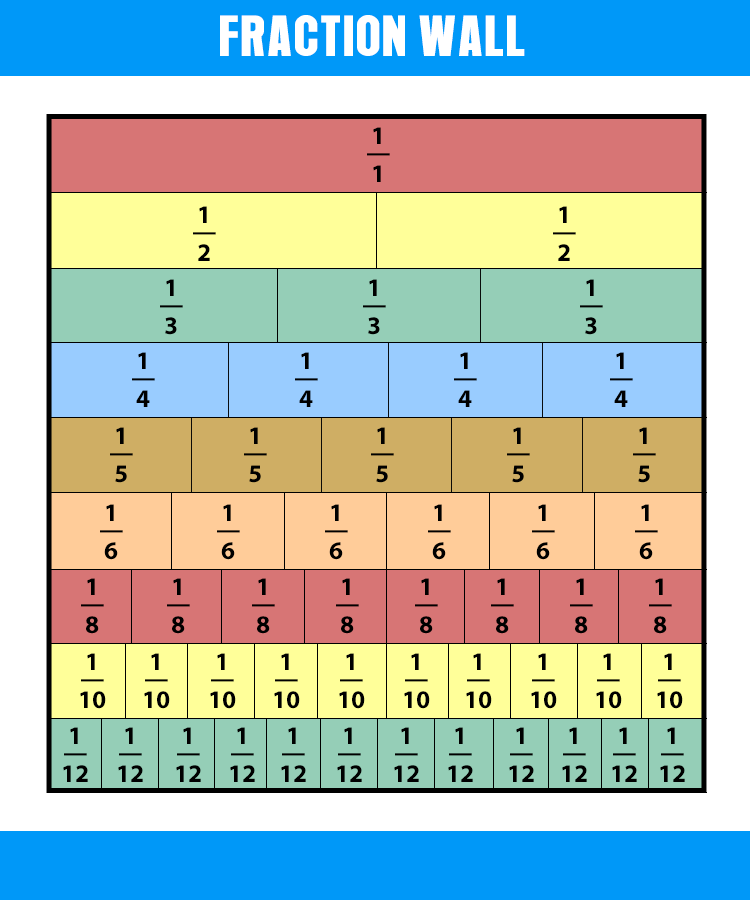
For a financially literate individual, understanding that 25% is precisely equivalent to 1/4 (just as 4/16 is equal to 1/4) is more than just a mathematical conversion; it’s a cognitive shortcut that allows for rapid assessment of financial situations. For example, knowing that a “25% discount” immediately means you save “one-quarter” of the price provides an immediate, tangible understanding of the value proposition. Similarly, a “20% down payment” on a house instantly translates to paying “one-fifth” of the total purchase price upfront. This quick conversion capability is invaluable for on-the-spot financial calculations and decisions, whether you’re evaluating a sale item, assessing a loan offer, or reviewing an investment prospectus.
The “Fraction of Your Income” Rule
Many widely accepted financial planning guidelines are rooted in fractional principles. For instance:
-
Retirement Savings: Financial advisors often recommend saving 10-15% of your gross income for retirement – a clear fractional commitment to your future.
-
Housing Costs: A common rule suggests that housing expenses should not exceed 30% of your gross monthly income, ensuring you have enough left for other necessities and savings.
-
Emergency Fund: The advice to save 3-6 months’ worth of living expenses is another fractional guideline, determining a necessary reserve based on a portion of your annual spending.
These fractional rules of thumb provide a structured, easily understandable framework for individuals to manage their money effectively and build financial resilience. They transform abstract financial goals into concrete, actionable steps.
Evaluating Financial Instruments
The concept of fractions extends to the evaluation of various financial instruments:
-
Stocks: When you buy a stock, you are purchasing a fractional ownership in a company. Stock splits (e.g., a 2-for-1 split) illustrate this beautifully: while the number of shares you own doubles, and the price per share halves, your overall fractional ownership of the company remains the same.
-
Bonds: The yield on a bond is typically calculated as the annual interest payment (a fraction of the bond’s face value) divided by its current market price.
-
Mutual Funds/ETFs: Understanding expense ratios, often expressed as small percentages (e.g., 0.50%), is crucial. This seemingly small fraction represents the annual fee you pay as a portion of your total investment. Over time, even small fractional fees can significantly impact overall returns.
-
Real Estate: Fractional ownership models are emerging, and calculating rental yields or capital appreciation involves understanding returns as a fraction of the property’s value.
Building a Solid Financial Foundation with Foundational Math
Ultimately, the ability to grasp that distinct fractions like 8/2, 12/3, or 16/4 all lead back to the same whole number, 4, is more than just a mathematical trick; it’s a powerful metaphor for achieving financial goals. Different pathways, varied investments, and diverse income streams can all converge on the same target if understood and managed correctly.
Practical Applications for Savvy Savers
Embracing the simplicity of “which fraction is equal to 4” as a gateway to more sophisticated financial understanding is a vital step for anyone seeking to improve their financial literacy. Savvy savers and investors routinely practice converting between fractions, decimals, and percentages, not in an academic setting, but in real-world scenarios. They apply these skills to meticulously analyze bank statements, critically assess investment reports, and thoughtfully construct their personal budgets. Mastering these basic mathematical relationships reduces financial anxiety, demystifies complex financial jargon, and grants individuals a heightened sense of control over their money. It empowers them to ask the right questions, identify potential pitfalls, and seize opportunities.

Empowering Your Financial Future
Financial independence and robust financial planning are not reserved for those with advanced degrees in economics or finance. They are attainable for anyone willing to cultivate a firm grasp of foundational mathematical principles, especially the concept of fractions and their equivalence. The insights gained from understanding that different numerical expressions can represent the same underlying value is profoundly empowering. It allows individuals to intelligently compare different financial products, accurately forecast outcomes, and make strategic decisions that align with their long-term objectives. By internalizing these fundamental concepts, individuals can move beyond simply reacting to financial circumstances and proactively shape their financial future with confidence, clarity, and control.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.