
Navigating the landscape of specialized credit products requires a keen understanding of where a card’s utility begins and ends. The Synchrony HOME Credit Card occupies a unique niche in the personal finance world. Unlike a standard store card that is tethered to a single retailer, or a general-purpose Visa or Mastercard that can be used anywhere, the Synchrony HOME card is a private-label credit card that operates within a massive, curated network.
For homeowners and renters looking to manage the high costs of renovation, furnishing, and maintenance, this card serves as a dedicated financial tool. By understanding the breadth of the Synchrony HOME network and the strategic financial implications of its use, consumers can leverage promotional financing to upgrade their living spaces without compromising their immediate liquidity.
The Scope of the Synchrony HOME Network
The most common question regarding the Synchrony HOME card is whether it functions as a “general” credit card. It does not. Instead, it is accepted at over a million locations nationwide that fall under the umbrella of home-related goods and services. This network includes some of the most recognizable national brands, as well as thousands of independent local retailers.
National Furniture and Decor Retailers
One of the primary strengths of the Synchrony HOME card is its deep integration with the furniture industry. High-quality furniture represents a significant capital expenditure, and the card is designed to mitigate the upfront cost through deferred interest offers. Major retailers where the card is typically accepted include:
-
Ashley Store: As one of the largest furniture retailers in the world, Ashley often offers exclusive financing windows for Synchrony HOME cardholders.
-
La-Z-Boy: Known for premium seating and upholstery, this retailer allows cardholders to finance major living room overhauls.
-
West Elm and Pottery Barn: Many Williams-Sonoma brands participate in the Synchrony ecosystem, allowing for more design-forward purchases.
-
Raymour & Flanigan: A staple in the Northeastern United States, providing access to a wide variety of bedroom, dining, and outdoor furniture.
Appliances, Electronics, and Home Tech
Beyond aesthetics, the Synchrony HOME card is a vital tool for functional home upgrades. When a refrigerator fails or an HVAC system needs replacement, the financial burden is often sudden and heavy.
-
Best Buy: While Best Buy has its own branded credit cards, the Synchrony HOME card is frequently accepted for major appliance and home theater purchases, providing an alternative path to financing.
-
PC Richard & Son: A major player in appliances and electronics, particularly on the East Coast.
-
Local Appliance Centers: Many independent dealers use Synchrony as their primary financing partner, meaning your local “mom and pop” appliance store is likely within the network.
Flooring, Mattresses, and Specialized Home Goods
The card’s utility extends into the “bones” of the home. This includes flooring, roofing, and bedding—industries where ticket prices are high and financing is standard.
-
Lumber Liquidators (LL Flooring) and Floor & Decor: Essential stops for those undertaking DIY or professional flooring renovations.
-
Mattress Firm and Serta: Given that a quality mattress can cost several thousand dollars, these retailers are core members of the Synchrony HOME network.
-
The Container Store: For organization and closet systems that require professional installation and high material costs.
Identifying Participating Merchants and Locations
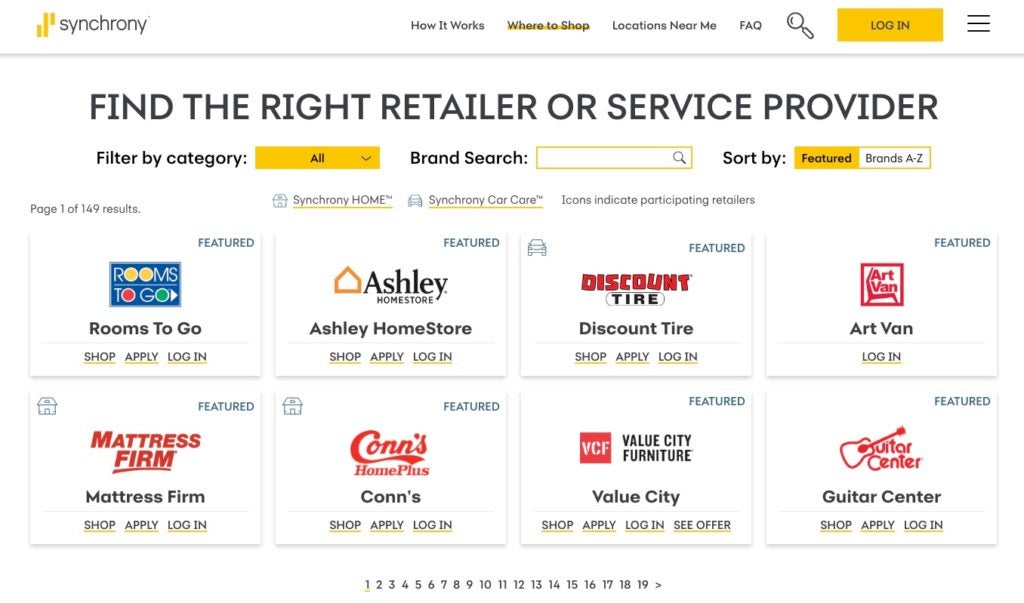
Because the Synchrony HOME card uses a specific merchant category code (MCC) filtering system, identifying where you can shop requires a bit of due diligence. The card is generally accepted at any merchant that displays the “Synchrony HOME” logo, but the network is broader than just those with visible signage.
Using the Synchrony Online Locator
The most reliable way to determine if a store accepts the card is through the Synchrony HOME mobile app or their official online store locator. By entering a zip code and selecting a category (such as “Flooring” or “Electronics”), cardholders can see a map of every local business—both large and small—that is authorized to process the card.
The “Preferred Partner” Distinction
It is important to distinguish between standard merchants and “Preferred Partners.” While the Synchrony HOME card is accepted at a wide variety of stores, Preferred Partners often offer more aggressive promotional financing terms. For example, a standard merchant might offer 6 months of deferred interest on a $299 purchase, whereas a Preferred Partner might offer 12, 18, or even 60 months of specialized financing on larger purchases.
Online vs. In-Store Usage
The Synchrony HOME card is primarily optimized for in-store purchases where a sales associate can assist with the financing transaction. However, many national retailers now allow for the card to be used at checkout on their websites. When shopping online, look for “Synchrony” or “Financing” options in the payment section rather than entering the card number into a standard “Credit Card” field, as the systems often require specific processing to trigger promotional interest rates.
Strategic Financial Benefits of Using the Card
From a wealth management perspective, the Synchrony HOME card is less about “spending” and more about “cash flow management.” Utilizing the card effectively requires an understanding of how promotional financing impacts your overall financial health.
The Power of Deferred Interest
The flagship feature of the Synchrony HOME card is its promotional financing. For purchases over a certain threshold (typically $299), cardholders are often granted a 6-month window where no interest is charged, provided the balance is paid in full by the end of the period.
This is a powerful tool for maintaining liquidity. Instead of withdrawing $3,000 from a high-yield savings account or an investment portfolio to buy a new HVAC unit, a cardholder can keep their cash earning interest elsewhere and pay down the balance over six months at 0% APR.
Extended Financing for Major Renovations
For significant projects—like a kitchen remodel or a whole-home flooring replacement—Synchrony often partners with merchants to provide “Equal Payment” plans. These can extend from 12 to 60 months. Unlike deferred interest (where interest is backdated if you miss the deadline), equal payment plans often function more like a traditional installment loan with a fixed 0% or low-interest APR, making them much safer for long-term debt management.
Credit Mix and Utilization
Using a dedicated “Home” card can help protect your general-purpose credit cards from high utilization. If you put a $5,000 furniture purchase on a standard Visa card with a $10,000 limit, your credit score might drop due to a 50% utilization rate on that specific card. By shifting that “big-ticket” debt to a Synchrony HOME card specifically designed for large balances, you keep your everyday credit cards “clean” for daily expenses and emergency liquidity.
Navigating the Risks: The “Interest Bomb”
While the Synchrony HOME card is a sophisticated financial tool, it carries a specific risk known as “Deferred Interest.” This is the most critical aspect of the card’s terms and conditions that every user must master to avoid a financial setback.
How Deferred Interest Works
If a cardholder makes a $1,000 purchase with a 6-month deferred interest promotion, the interest is still being calculated behind the scenes at a relatively high APR (often 29.99% or higher). If the cardholder pays off the full $1,000 within the 6 months, the interest is waived.
However, if even $1 of that balance remains after the 6-month period ends, the “interest bomb” explodes. The cardholder is charged the full interest accumulated on the original $1,000 from the date of purchase. This can result in hundreds of dollars in unexpected charges added to the bill instantly.
Best Practices for Repayment
To use the Synchrony HOME card effectively, financial experts recommend the following:
-
Divide and Conquer: Take the total purchase price and divide it by the number of months in the promotional period minus one. If you have a 6-month window, aim to pay it off in 5 months to provide a safety buffer.
-
Autopay is Essential: Set up automated payments that exceed the “Minimum Payment Due.” The minimum payment on the statement is often calculated to not pay off the balance before the promotion expires.
-
Monitor Multiple Promotions: If you use the card for a mattress in January and a sofa in March, you will have two different expiration dates for deferred interest. You must track these separately to ensure the oldest balances are cleared first.

Conclusion: A Specialized Tool for a Specific Purpose
The Synchrony HOME card is not a replacement for a primary rewards credit card or a cash-back card. Its value lies in its role as a dedicated “Home Improvement Fund” that offers interest-free leverage. By using the card at participating furniture, appliance, and flooring retailers, consumers can preserve their cash and manage large expenses through structured, short-term financing.
When used strategically—with a firm commitment to paying off balances within the promotional window—the Synchrony HOME card becomes an invaluable asset for home maintenance and improvement. It allows for the immediate enhancement of one’s living environment while providing the flexibility to pay for those enhancements over time, aligning one’s lifestyle goals with responsible financial management.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.