
Venmo, once the quintessential peer-to-peer (P2P) payment app, has undeniably evolved far beyond its initial premise. What began as a quirky, socially-oriented way to split dinner bills or pay rent has matured into a multifaceted digital platform striving to remain relevant and competitive in a rapidly accelerating fintech landscape. From significant feature rollouts to continuous enhancements in its underlying technology and formidable digital security challenges, a lot is indeed “going on” with Venmo. This exploration delves into the technological shifts and developments that are shaping Venmo’s present and future, examining how the app is refining its software, bolstering its security, and integrating itself deeper into our digital lives.
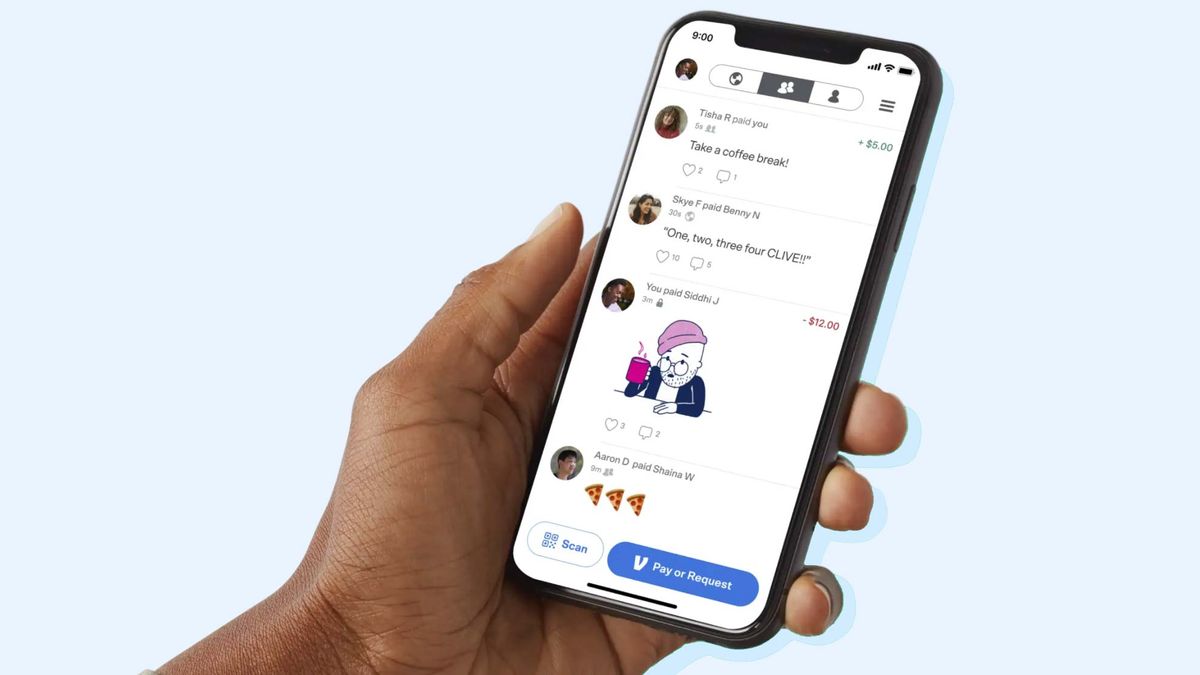
Venmo’s Expanding Digital Toolkit: Beyond P2P Payments
Venmo’s journey from a niche P2P tool to a more comprehensive digital wallet has been marked by a series of strategic technological expansions. These additions reflect a broader trend in app development: to become indispensable by offering a wider array of services within a single, familiar interface. This evolution demands robust software development, seamless integration of new features, and the scalability to handle increased complexity without compromising performance.
The Rise of Business Profiles
One of Venmo’s most significant software advancements has been the introduction and subsequent refinement of business profiles. This feature transformed Venmo from a purely personal transaction facilitator into a viable micro-commerce platform. Technologically, this involved building a separate layer of functionality atop the existing P2P architecture, requiring new payment processing logic, reporting tools, and merchant-specific user interfaces. Businesses can now accept payments, manage transactions, and even promote their services directly within the app, leveraging Venmo’s vast user base. This expansion necessitated sophisticated backend development to differentiate business accounts from personal ones, manage associated fees, and comply with varied financial regulations, all while maintaining the app’s characteristic ease of use for the end consumer.
Instant Transfers and Debit Cards
The demand for immediate access to funds has driven Venmo to enhance its core transfer technology. While standard transfers could take days, the introduction of instant transfers (for a small fee) represented a significant technological upgrade. This capability relies on real-time payment processing systems and intricate bank integrations, ensuring that funds are moved and settled almost instantaneously. Complementing this, the Venmo Debit Card and Credit Card integrations further embed the platform into daily financial transactions. These aren’t just physical cards; they are direct extensions of the Venmo app, requiring advanced API integrations with banking partners and payment networks (like Mastercard or Visa). The technological challenge lies in ensuring real-time balance updates, fraud monitoring, and seamless transactional data flow between the card networks, banking institutions, and the Venmo app itself, providing users with a fluid and interconnected digital banking experience.
Exploring Crypto Integration
Perhaps one of Venmo’s most ambitious technological ventures has been its foray into cryptocurrency. Allowing users to buy, sell, and hold popular cryptocurrencies like Bitcoin and Ethereum directly within the app is a testament to its commitment to embracing emerging digital asset trends. This feature presented immense software development hurdles, including integrating with cryptocurrency exchanges, building secure digital wallets (or partnering with custodians), ensuring regulatory compliance for digital assets, and providing a user-friendly interface for inherently complex transactions. The backend infrastructure for crypto trading is distinct from traditional fiat currency transfers, requiring specialized security protocols, market data feeds, and transaction validation mechanisms, all seamlessly integrated into the existing Venmo app environment. This move showcases Venmo’s adaptive technological strategy, aiming to keep pace with broader digital financial innovation.
Navigating the User Experience: Simplicity Meets Scale
At its heart, Venmo’s initial success was largely attributable to its intuitive and engaging user experience (UX). As the app grows in complexity and feature set, maintaining this design philosophy becomes a significant technological and design challenge. The goal is to scale functionality without sacrificing the clean, accessible interface that users have come to expect.
Maintaining Intuitive Design
The transition from a simple P2P app to a multi-feature digital wallet can easily lead to “feature creep” and a cluttered interface. Venmo’s design teams continuously grapple with how to introduce new functionalities—like business profiles, crypto trading, or budgeting tools—without overwhelming the user. This involves sophisticated UI/UX research, A/B testing, and iterative design cycles. The technological implementation requires a modular approach to the app’s architecture, allowing new features to be layered in without disrupting core functionalities. This also means optimizing performance, ensuring swift load times, and responsive interactions, even as the codebase grows larger and more complex, critical factors for user retention in a competitive app market.
Personalization and Notifications
As Venmo collects more user data through its expanded services, the potential for personalization grows. Technologically, this means leveraging advanced algorithms and machine learning to offer tailored experiences, such as suggesting relevant businesses, highlighting spending patterns, or providing personalized security alerts. The notification system, once primarily for transaction alerts, has evolved into a more sophisticated communication channel, requiring robust backend services to deliver timely and relevant updates. This includes filtering social feed activity, transactional summaries, and promotional content, all managed by intelligent notification engines designed to enhance engagement without becoming intrusive. The development here lies in optimizing the delivery and relevance of these personalized elements without compromising user privacy.
The Balance of Social and Private

Venmo famously incorporated a social feed into its P2P transactions, a feature that distinguished it from traditional banking apps. However, as the app scales and matures, balancing this public aspect with the growing demand for privacy has become a key UX challenge. Technologically, this involves offering granular privacy controls for each transaction, allowing users to easily choose between public, friends-only, or private settings. It also means clearly communicating the default privacy settings and offering accessible options for users to manage their data visibility. The underlying software must reliably enforce these preferences across all user interactions, ensuring that data sharing aligns precisely with user expectations, reflecting a mature approach to privacy in app design.
Bolstering the Digital Fort Knox: Security, Privacy, and Trust
For any application dealing with financial transactions, digital security and privacy are not just features; they are foundational pillars. “What’s going on with Venmo” from a tech perspective is heavily intertwined with its ongoing efforts to fortify its defenses against an increasingly sophisticated landscape of cyber threats.
Advanced Fraud Detection
Venmo invests heavily in state-of-the-art fraud detection technologies. This includes machine learning algorithms that analyze transaction patterns in real-time to identify suspicious activity, such as unusual spending habits, new device logins, or rapid transfers to unknown accounts. These AI-driven systems are continuously trained on vast datasets of transactional information to improve their accuracy and adapt to new fraud vectors. Technologically, this involves processing massive amounts of data with minimal latency, allowing for immediate flagging and potential blocking of fraudulent transactions before they complete. The integration of biometric authentication (fingerprint, facial recognition) further strengthens login security, providing an additional layer of protection beyond traditional passwords.
Data Encryption and User Control
User data privacy is paramount, especially for a financial app. Venmo employs robust encryption protocols, both in transit (when data is moving between the user’s device and Venmo’s servers) and at rest (when data is stored on servers). This means sensitive information like bank details, credit card numbers, and personal identifiers are rendered unreadable to unauthorized parties. From a technological standpoint, implementing and maintaining these encryption standards requires continuous updates and adherence to industry best practices (e.g., TLS 1.2+, AES-256). Furthermore, Venmo provides users with comprehensive controls over their personal data, including the ability to manage connected devices, review account activity, and adjust privacy settings, ensuring transparency and empowering users to manage their digital footprint within the app.
Best Practices for Digital Safety
Beyond internal technological safeguards, Venmo actively educates its users on best practices for digital safety. This includes encouraging strong, unique passwords, promoting two-factor authentication (2FA) for all accounts, and warning against phishing scams and unsolicited requests for money. While these are user-side actions, the app’s design plays a crucial role in enabling and reinforcing these behaviors. For example, the seamless integration of 2FA options, clear warnings for suspicious links, and easy-to-access security settings within the app itself are all critical technological components that empower users to protect themselves, thereby strengthening the overall security posture of the Venmo ecosystem.
Venmo’s Place in the Fintech Landscape: Innovation and Interoperability
Venmo does not operate in a vacuum. Its technological trajectory is heavily influenced by the broader fintech ecosystem, characterized by rapid innovation, intense competition, and an increasing demand for seamless interoperability between various digital financial services.
Competing with Digital Wallets
The digital wallet space is crowded, with competitors ranging from tech giants like Apple Pay and Google Pay to established banks’ own payment apps and emerging fintech startups. Venmo’s technological strategy involves differentiating itself through its unique social elements and continually expanding its feature set to match or exceed competitors. This includes enhancing its NFC capabilities for in-store payments, developing more sophisticated loyalty programs, and exploring integrations with other consumer services, all powered by a robust and flexible backend infrastructure that can adapt quickly to market demands and technological shifts. The race is to offer the most comprehensive and technologically advanced digital payment experience.
API Integrations and Third-Party Connectivity
The future of fintech lies in interconnectedness. Venmo’s technological growth also hinges on its ability to integrate smoothly with third-party applications and services. This involves developing robust Application Programming Interfaces (APIs) that allow businesses and developers to securely connect their platforms with Venmo’s payment processing capabilities. Examples include enabling Venmo as a checkout option on e-commerce sites or allowing developers to build new financial tools that leverage Venmo’s data (with user consent). These API integrations require stringent security protocols, clear documentation, and efficient rate limiting to ensure stability and protect user data while fostering a broader ecosystem of digital innovation around Venmo.

The Future of Mobile Payments Technology
Looking ahead, Venmo is poised to continue integrating cutting-edge technologies. This could include further exploration of blockchain for enhanced security and transparency, deeper integration of AI for predictive analytics in spending habits, or leveraging augmented reality (AR) for novel payment experiences. The underlying technological infrastructure must be flexible enough to support these future innovations, requiring a commitment to scalable cloud computing, microservices architecture, and continuous research and development. “What’s going on with Venmo” is a continuous story of technological adaptation, striving to stay at the forefront of mobile payments and digital finance.
In conclusion, Venmo is far from static. Its journey is a vibrant illustration of a software application constantly evolving to meet the demands of a dynamic digital world. From refining its core P2P functionality to embracing business solutions, instant transfers, and even cryptocurrency, Venmo’s technological advancements underscore a commitment to remaining a pivotal player in the digital economy. Through robust feature development, meticulous UX design, and relentless pursuit of digital security, Venmo continues to navigate the complexities of modern fintech, ensuring that its software remains both powerful and approachable for its vast user base.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.