
The moment the Powerball drawing concludes and the winning numbers are announced, the financial reality for at least one individual—or a group of individuals—shifts in an instant. While millions of Americans search for those five white balls and the single red Powerball to see if they have secured a life-changing fortune, the true challenge begins after the numbers are confirmed. In the realm of personal finance and wealth management, a lottery win is the ultimate “black swan” event: a high-impact, unpredictable occurrence that requires a sophisticated financial strategy to navigate successfully.
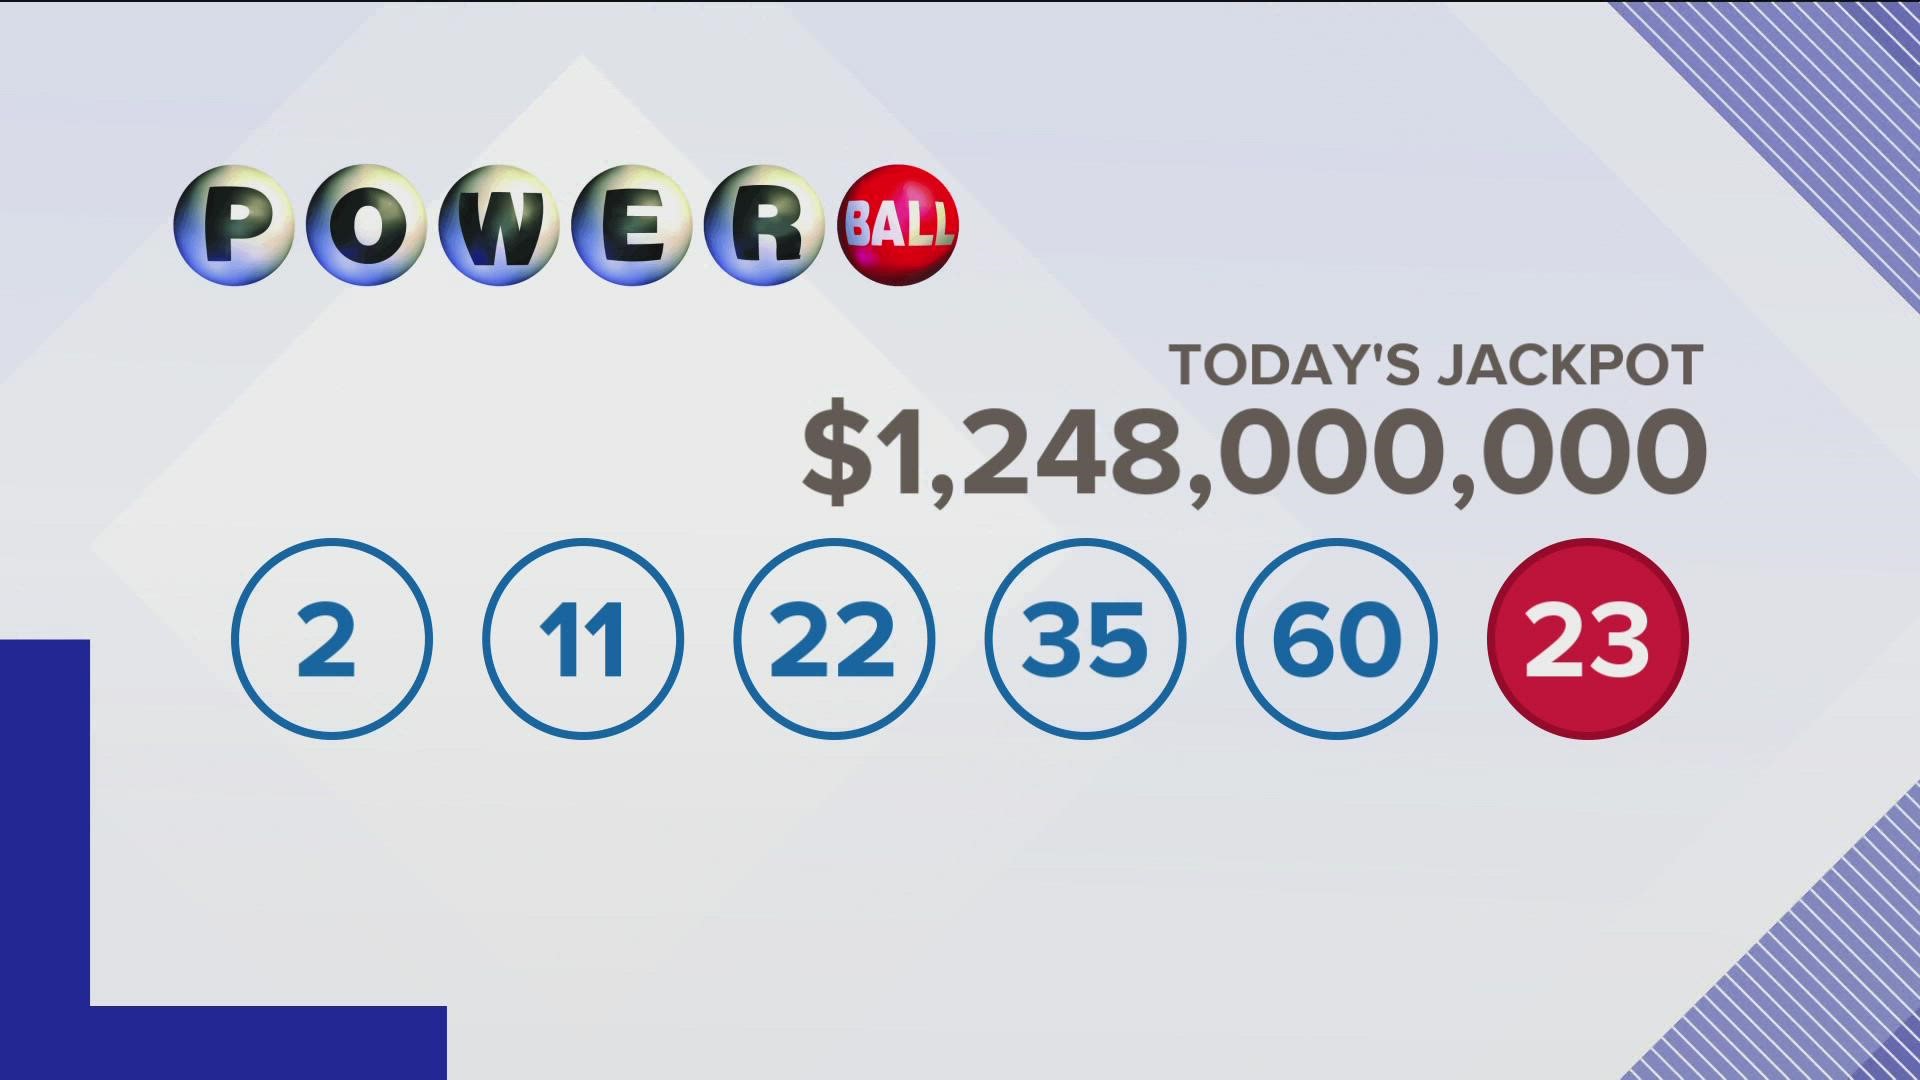
Understanding what to do once the winning numbers match your ticket is less about the numbers themselves and more about the financial infrastructure you build around that new capital. Managing a multi-million dollar windfall requires a transition from the mindset of a standard earner to that of a high-net-worth wealth steward.
The Financial Mathematics of the Powerball Draw
To understand the weight of the winning numbers, one must first understand the mathematical landscape of the Powerball. The game is structured with odds of 1 in 292.2 million. From a personal finance perspective, the “investment” in a lottery ticket is statistically negative in expected value until the jackpot reaches a specific threshold that compensates for the extreme rarity of a win. However, once the numbers are drawn, the focus shifts from probability to liquidity and asset management.
Understanding Probability and Risk
In the world of professional investing, risk is usually balanced against potential returns. The lottery is a unique financial vehicle because it represents a total loss of principal for the vast majority of participants. For the winner, however, the “risk” shifts from the loss of the ticket price to the risk of mismanaging a sudden surge of liquidity.
When the winning numbers are validated, the recipient is suddenly faced with a concentrated position. In finance, a concentrated position is when a huge portion of your net worth is tied up in a single asset—in this case, the claim on the jackpot. The immediate goal of any sound financial plan following the announcement of the winning numbers is to diversify that concentration and mitigate the risks associated with “sudden wealth syndrome.”
The Economic Psychology of the Lottery
The search for winning numbers often spikes when the jackpot exceeds $500 million. Economists refer to this as the “jackpot effect,” where the perceived utility of the potential win outweighs the statistical impossibility of the event. From a money management standpoint, this behavior highlights a fundamental human tendency toward “aspiration-based” financial planning.
When an individual wins, the psychology of money changes. The “winning numbers” represent more than just currency; they represent a total removal of financial constraints. Professional wealth advisors note that the highest risk to a winner is not the market, but rather the psychological impulse to overspend before a long-term fiscal framework is established.
Immediate Financial Protocols Following a Win
Once the winning numbers are confirmed and you realize you hold the winning ticket, the first 48 to 72 hours are the most critical for your long-term financial health. The urge to claim the prize immediately is often overwhelmed by the need for privacy and protection.
Establishing a Legal and Financial Infrastructure
The very first step is not claiming the prize, but rather securing the ticket and seeking professional counsel. In the niche of high-stakes personal finance, “The Big Three” advisors are essential: a tax attorney, a Certified Public Accountant (CPA), and a fee-only financial planner.
A tax attorney is vital for determining the best legal entity to claim the prize. In some jurisdictions, winners can claim the prize through a blind trust or a limited liability company (LLC), which helps maintain anonymity. Anonymity is a powerful financial tool; it protects the winner from predatory “investment opportunities” and requests for capital that can rapidly deplete a windfall.
The Importance of the “Cooling-Off” Period
The period between discovering the winning numbers and claiming the prize should be used as a “cooling-off” period. During this time, the winner should avoid making any major lifestyle changes—no quitting jobs, no purchasing luxury real estate, and no significant gifts to family members.
Financial experts recommend creating a “pro forma” budget during this time. This involves projecting your new net worth after taxes and determining a sustainable “burn rate.” By understanding the difference between the gross jackpot and the net take-home pay, a winner can avoid the common pitfall of over-leveraging their future income based on an inflated headline number.
Lump Sum vs. Annuity: A Deep Dive into Net Present Value
Perhaps the most significant financial decision a Powerball winner faces is the choice between the cash option (lump sum) and the annuity. The “winning numbers” translate into two very different financial paths, and the “correct” choice depends on your age, risk tolerance, and investment expertise.

The Case for the Lump Sum
The lump sum is the present value of the jackpot. While the headline figure might be $1 billion, the cash option might be closer to $500 million. Taking the lump sum allows for immediate control over the capital. From an investment perspective, this is often preferred by those who believe they can achieve an annual return that exceeds the 5% yearly increase provided by the Powerball annuity.
By taking the lump sum, you can implement a diversified portfolio of equities, fixed income, and alternative investments immediately. In a high-inflation environment, having the cash upfront allows for the purchase of “hard assets” like real estate or commodities that can serve as a hedge against the declining purchasing power of the dollar.
The Security of the 30-Year Annuity
The Powerball annuity is paid out over 30 years, with each payment being 5% larger than the last. For individuals who lack experience managing large sums of money, the annuity acts as a “forced discipline” mechanism. It provides a guaranteed income stream that is virtually impossible to squander in its entirety in a single year.
From a tax perspective, the annuity can also be beneficial. Instead of paying the highest marginal tax rate on the entire sum in year one, the tax liability is spread out over three decades. This can potentially result in a lower total tax bill if tax laws change or if the winner resides in a state with fluctuating income tax rates.
Tax Strategies and Wealth Preservation
When the winning numbers are announced, the IRS is effectively a co-winner. Understanding the tax implications is the difference between keeping the majority of your wealth and seeing it eroded by preventable liabilities.
Navigating Federal and State Tax Liabilities
Immediately upon claiming the prize, the lottery commission typically withholds 24% for federal taxes. However, because a large jackpot will almost certainly put the winner in the highest tax bracket (currently 37%), a significant additional payment will be due at tax time.
Furthermore, state taxes vary wildly. Winners in states like Florida or Texas, which have no state income tax, will keep significantly more of their winnings than those in New York or California. A strategic move for those who haven’t yet claimed their prize might involve establishing residency in a more tax-friendly state, though this requires careful legal navigation to ensure compliance with “source income” rules.
Utilizing Trusts for Asset Protection
To preserve wealth across generations, the use of irrevocable trusts is standard practice for windfall recipients. A trust can be structured to provide for the winner’s needs while protecting the principal from creditors and legal judgments.
Moreover, sophisticated estate planning—such as the use of Generation-Skipping Transfer Tax (GSTT) exemptions—can ensure that the wealth generated by those winning numbers benefits children and grandchildren with minimal tax friction. Wealth preservation is not just about growing the money; it is about building a “moat” around it.
Long-Term Investment Philosophy for Large Windfalls
The final stage of managing a Powerball win is shifting from “getting rich” to “staying rich.” This requires a conservative investment philosophy focused on capital preservation and moderate growth.
Diversification Beyond Traditional Markets
With a net worth in the hundreds of millions, a winner can access “institutional-class” investments that are unavailable to the general public. This includes private equity, venture capital, and hedge funds. Diversification should also extend to geographic regions, holding assets in different currencies and jurisdictions to protect against domestic economic downturns.
A typical “winning numbers” portfolio might look like a 40/30/30 split: 40% in low-cost index funds and high-grade bonds, 30% in direct real estate holdings, and 30% in alternative investments and liquid cash reserves. This structure ensures liquidity for lifestyle needs while providing exposure to growth.

Philanthropy as a Financial Strategy
Many winners find that after the initial excitement fades, the most fulfilling use of their wealth is philanthropy. From a financial standpoint, charitable giving is a highly effective tool for reducing taxable income. Establishing a private foundation or a Donor-Advised Fund (DAF) allows the winner to support causes they care about while simultaneously managing their tax bracket.
In conclusion, while the world focuses on “what were the winning numbers on Powerball,” the savvy individual focuses on what those numbers represent: a complex financial responsibility. By treating a lottery win as a business to be managed rather than a stroke of luck to be spent, a winner can transform a momentary windfall into a multi-generational legacy of financial security.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.