
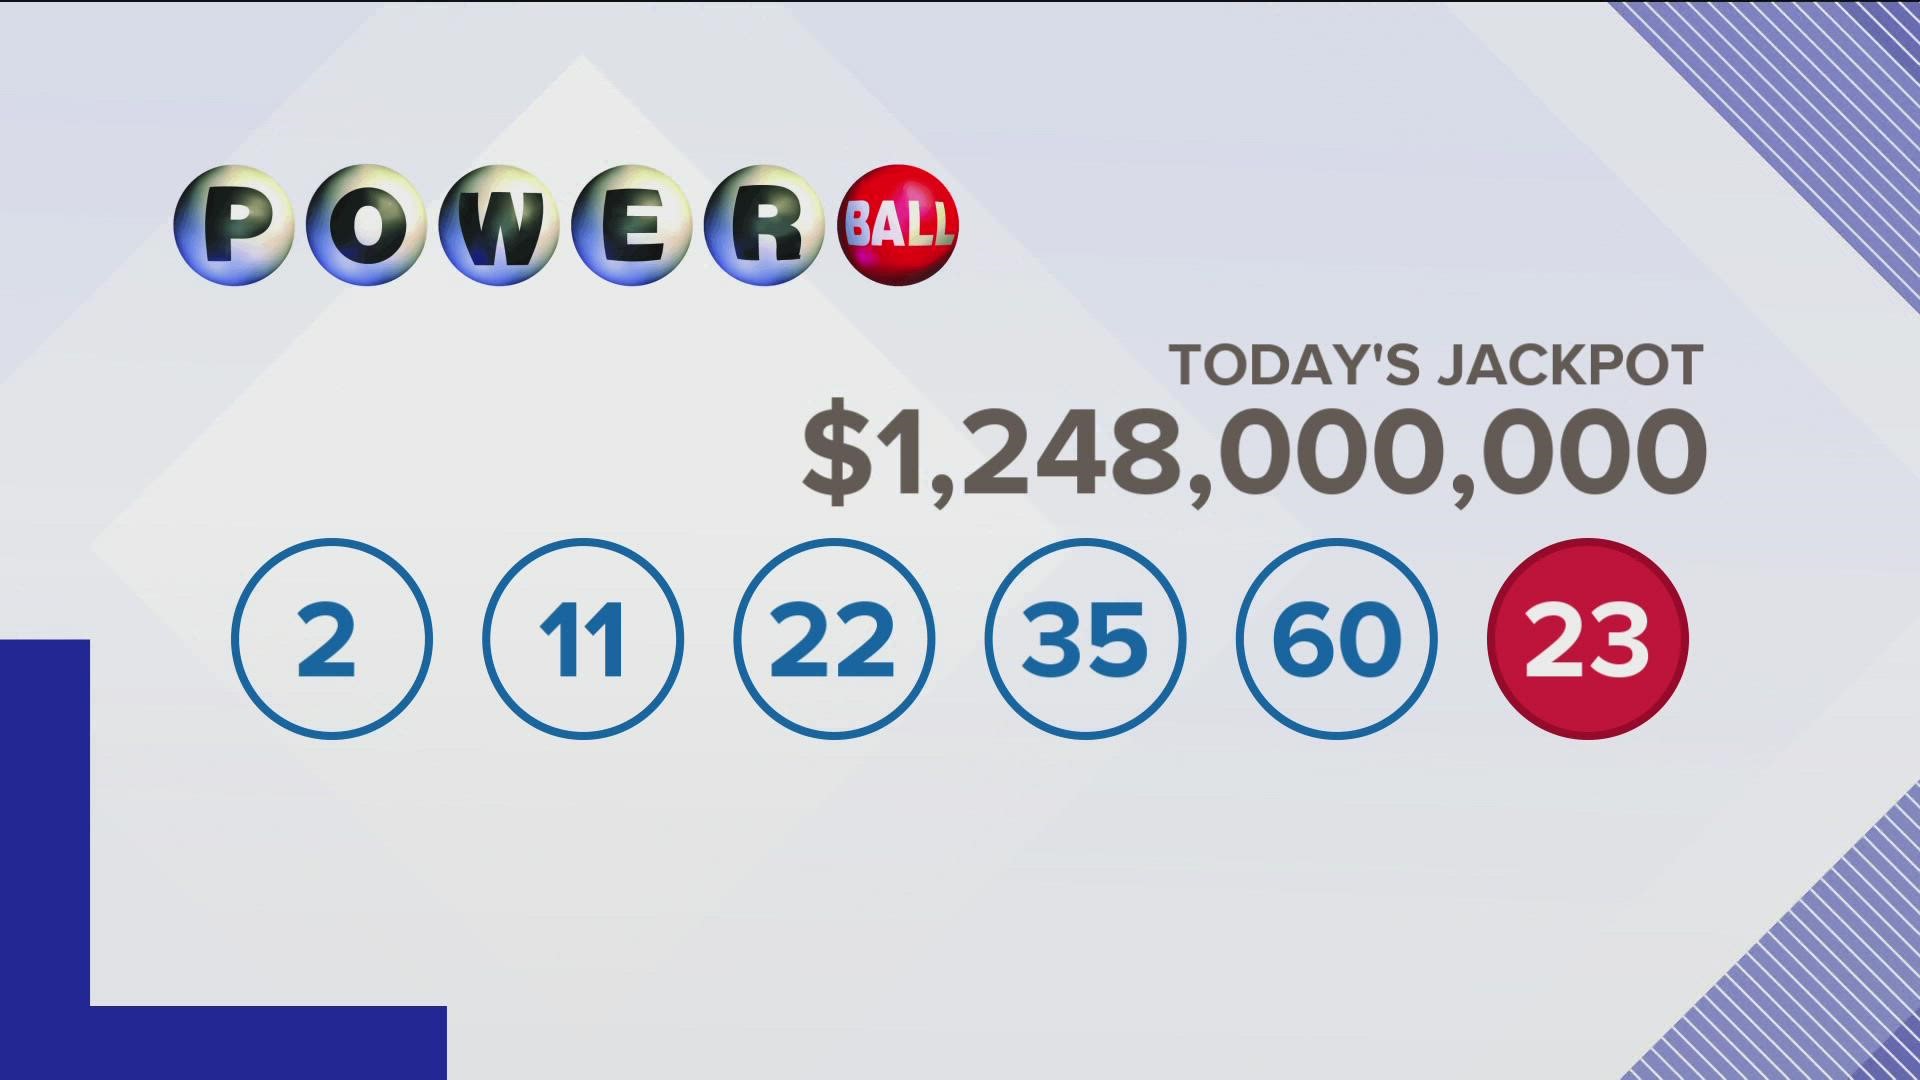
The moment the Powerball draw occurs, millions of people across the country hold their breath, eyes darting between their physical tickets and the glowing screens displaying the six critical numbers. Searching for “what was tonight’s Powerball winning numbers” is often the first step in a journey that could theoretically transform a person’s financial standing from average to astronomical in a matter of seconds. However, the numbers themselves—the white balls and the red Powerball—are merely the keys to a much more complex financial vault.
Winning a massive lottery jackpot is the ultimate “black swan” event in personal finance. It is an outlier of such magnitude that standard financial planning often fails to account for the sheer velocity of wealth accumulation. While the immediate impulse is to celebrate, the secondary impulse must be one of rigorous financial stewardship. Understanding the mechanics of sudden wealth, from tax obligations to long-term asset allocation, is what separates those who build lasting legacies from those who become cautionary tales of the “lottery curse.”

The Immediate Financial Reality of Winning the Lottery
When you confirm that your ticket matches tonight’s winning numbers, the transition from a standard earner to a high-net-worth individual begins instantly. This transition requires a shift in mindset from “how do I pay my bills” to “how do I protect this capital.” The first few hours and days are critical for establishing a foundation of security and privacy.
Immediate Steps After Identifying the Winning Numbers
Before coming forward to claim a prize, a winner must secure the physical proof of their win. In the world of high-stakes finance, a winning lottery ticket is a “bearer instrument,” meaning whoever holds it is generally considered the owner. Signing the back of the ticket and placing it in a secure location, such as a bank safety deposit box, is the first rule of asset protection.
The next step is not calling the lottery office, but rather assembling a “quiet team.” This team typically includes a tax attorney, a certified public accountant (CPA) with experience in high-net-worth clients, and a fee-only financial planner. These professionals act as a buffer between the winner and the public, helping to navigate the jurisdictional laws regarding anonymity. In some states, winners can claim prizes via a blind trust or an LLC, which is a vital strategy for maintaining personal security and preventing unsolicited “investment opportunities” from distant relatives or predatory “financial advisors.”
Choosing Between Lump Sum and Annuity Payments
One of the most significant financial decisions a Powerball winner faces is the choice between the cash option (lump sum) and the annuity. The “advertised” jackpot is almost always the sum of 30 payments over 29 years, which includes the interest earned on the prize pool over time. The lump sum, conversely, is the actual cash currently in the prize pool.
From a pure investment perspective, many financial experts argue for the lump sum. By taking the cash upfront, the winner gains control over the capital and can potentially outpace the lottery’s internal rate of return through a diversified portfolio of equities, real estate, and fixed-income assets. However, the annuity offers a unique form of “behavioral insurance.” It prevents a winner from exhausting their entire fortune in a few years of reckless spending, as a new check will arrive every year regardless of previous financial mistakes. The decision depends heavily on the individual’s financial discipline and their access to sophisticated wealth management tools.
Tax Implications and Legal Structuring
The federal government and most state governments view lottery winnings as ordinary income, not capital gains. This distinction is vital because it means the winnings are taxed at the highest possible brackets. When you see the massive numbers posted after tonight’s draw, remember that the “take-home” pay is significantly lower than the headline figure.
Understanding Federal and State Tax Obligations
The Internal Revenue Service (IRS) considers lottery winnings as gambling winnings, which are taxable. For a jackpot of the size typically seen in Powerball, the winner will automatically fall into the top federal income tax bracket, which currently stands at 37%. When a winner claims their prize, the lottery commission typically withholds 24% for federal taxes immediately. However, this is only a “down payment.” The winner will owe the remaining 13% when they file their tax return the following year.
Furthermore, state taxes vary wildly. States like Florida, Texas, and South Dakota do not tax lottery winnings because they have no state income tax. Conversely, winners in states like New York or New Jersey may face an additional 8% to 10% in state withholdings. Calculating the “net-net” figure—what is left after both federal and state bites—is the only way to accurately budget for the future.
Protecting Your Assets Through Legal Entities
Sophisticated wealth management often involves the use of legal structures to shield assets from liability and to facilitate estate planning. Upon winning, a common strategy is to establish a Family Limited Partnership (FLP) or a series of trusts. These entities serve multiple purposes: they can help keep the winner’s name out of public records, provide a framework for gifting money to family members without triggering excessive gift taxes, and protect the core capital from potential lawsuits.
In the litigious environment that often surrounds sudden wealth, “asset protection” becomes a primary goal. By holding the majority of the winnings in irrevocable trusts or corporate entities, the winner limits their personal exposure. This ensures that even if a personal legal dispute arises, the bulk of the wealth remains legally distinct and protected.
Building a Long-Term Wealth Management Strategy
Once the initial shock wears off and the taxes are accounted for, the focus must shift to capital preservation and growth. The goal of a Powerball winner should be to move from “lottery winner” to “perpetual wealth holder.” This requires a sophisticated approach to the markets and a deep understanding of risk management.
Setting Up a Professional Financial Team
A sudden windfall of hundreds of millions of dollars moves a person into the realm of “Ultra-High Net Worth” (UHNW). Standard retail banking services are no longer sufficient. Winners typically look toward private banking sectors or multi-family offices. These institutions provide specialized services, such as bespoke investment strategies, philanthropic consulting, and concierge services.
The professional team should operate on a fiduciary standard, meaning they are legally obligated to act in the client’s best interest. A common mistake is hiring “friends of friends” or relatives to manage the money. Professional distance is required to make the cold, hard calculations necessary to sustain wealth across generations.
Diversifying Your Portfolio Beyond the Jackpot
A common pitfall for those who strike it rich is “concentration risk.” If a winner takes the lump sum and leaves it in a single savings account or puts it all into a single “sure-fire” business venture, they are courting disaster.
A professional portfolio for a lottery winner should be globally diversified. This includes:
- Equities: A mix of domestic and international stocks to capture market growth.
- Fixed Income: High-quality municipal bonds (which offer tax advantages) and treasury securities to provide a steady income stream.
- Real Estate: Direct ownership of property or investments in Real Estate Investment Trusts (REITs) to act as a hedge against inflation.
- Alternative Investments: Private equity, venture capital, or commodities to provide non-correlated returns.
The objective is to create a “money machine” where the annual returns on the principal are more than enough to fund a lavish lifestyle, ensuring that the original jackpot remains untouched and grows over time.
Psychology of Wealth: Avoiding the “Lottery Curse”
Perhaps the most difficult aspect of winning the Powerball isn’t the math, but the psychology. Data suggests that a startlingly high percentage of lottery winners declare bankruptcy within several years. This phenomenon, often called the “lottery curse,” is usually the result of “lifestyle creep” and the lack of a psychological framework for handling vast sums of money.
Lifestyle Creep and Budgeting for Longevity
Lifestyle creep occurs when your expenses rise in tandem with (or faster than) your income. For a lottery winner, this might manifest as purchasing multiple estates, private jets, and high-maintenance luxury goods. The hidden cost of wealth is the “burn rate”—the monthly amount required to maintain one’s lifestyle.
A professional financial plan includes a strict “withdrawal rate.” Much like an endowment for a university, a lottery winner should aim to spend only 3% to 4% of their total capital annually. On a $100 million net win, a 3% withdrawal rate provides $3 million a year—an extraordinary amount of money that allows for luxury without depleting the core principal. Discipline in the first two years of winning is the most accurate predictor of long-term financial success.

Philanthropy and Legacy Planning
For many winners, the realization eventually hits that they have more money than they could ever spend in several lifetimes. This is where philanthropy and legacy planning enter the conversation. Establishing a private foundation or a Donor-Advised Fund (DAF) allows winners to support causes they care about while also providing significant tax deductions.
Legacy planning involves more than just writing a will; it involves educating the next generation on how to handle wealth. Without proper financial education, heirs can quickly squander what took a stroke of incredible luck to acquire. By structuring the wealth into incentive-based trusts, winners can ensure their children and grandchildren remain productive members of society while benefiting from the financial security the Powerball win provided.
In conclusion, while the search for “tonight’s Powerball winning numbers” is driven by the dream of a different life, the reality of winning is a serious business. It is a transition from a life of labor to a life of capital management. By approaching a windfall with a professional, disciplined, and strategic mindset, a winner can transform a moment of luck into a multi-generational legacy of financial freedom.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.