
The search for “what was the cash 3 number for tonight” is a daily ritual for millions of individuals. It represents a momentary intersection of hope, excitement, and the desire for a quick financial windfall. While the immediate answer to that question is a simple three-digit sequence, the broader implications of participating in daily lottery games like Cash 3 belong to a much larger conversation about personal finance, risk management, and the psychology of wealth building. To understand the true cost and potential of these small-scale financial decisions, one must look beyond the draw results and into the mechanics of probability and long-term asset allocation.
The Psychology of Low-Stakes Gaming in Personal Finance
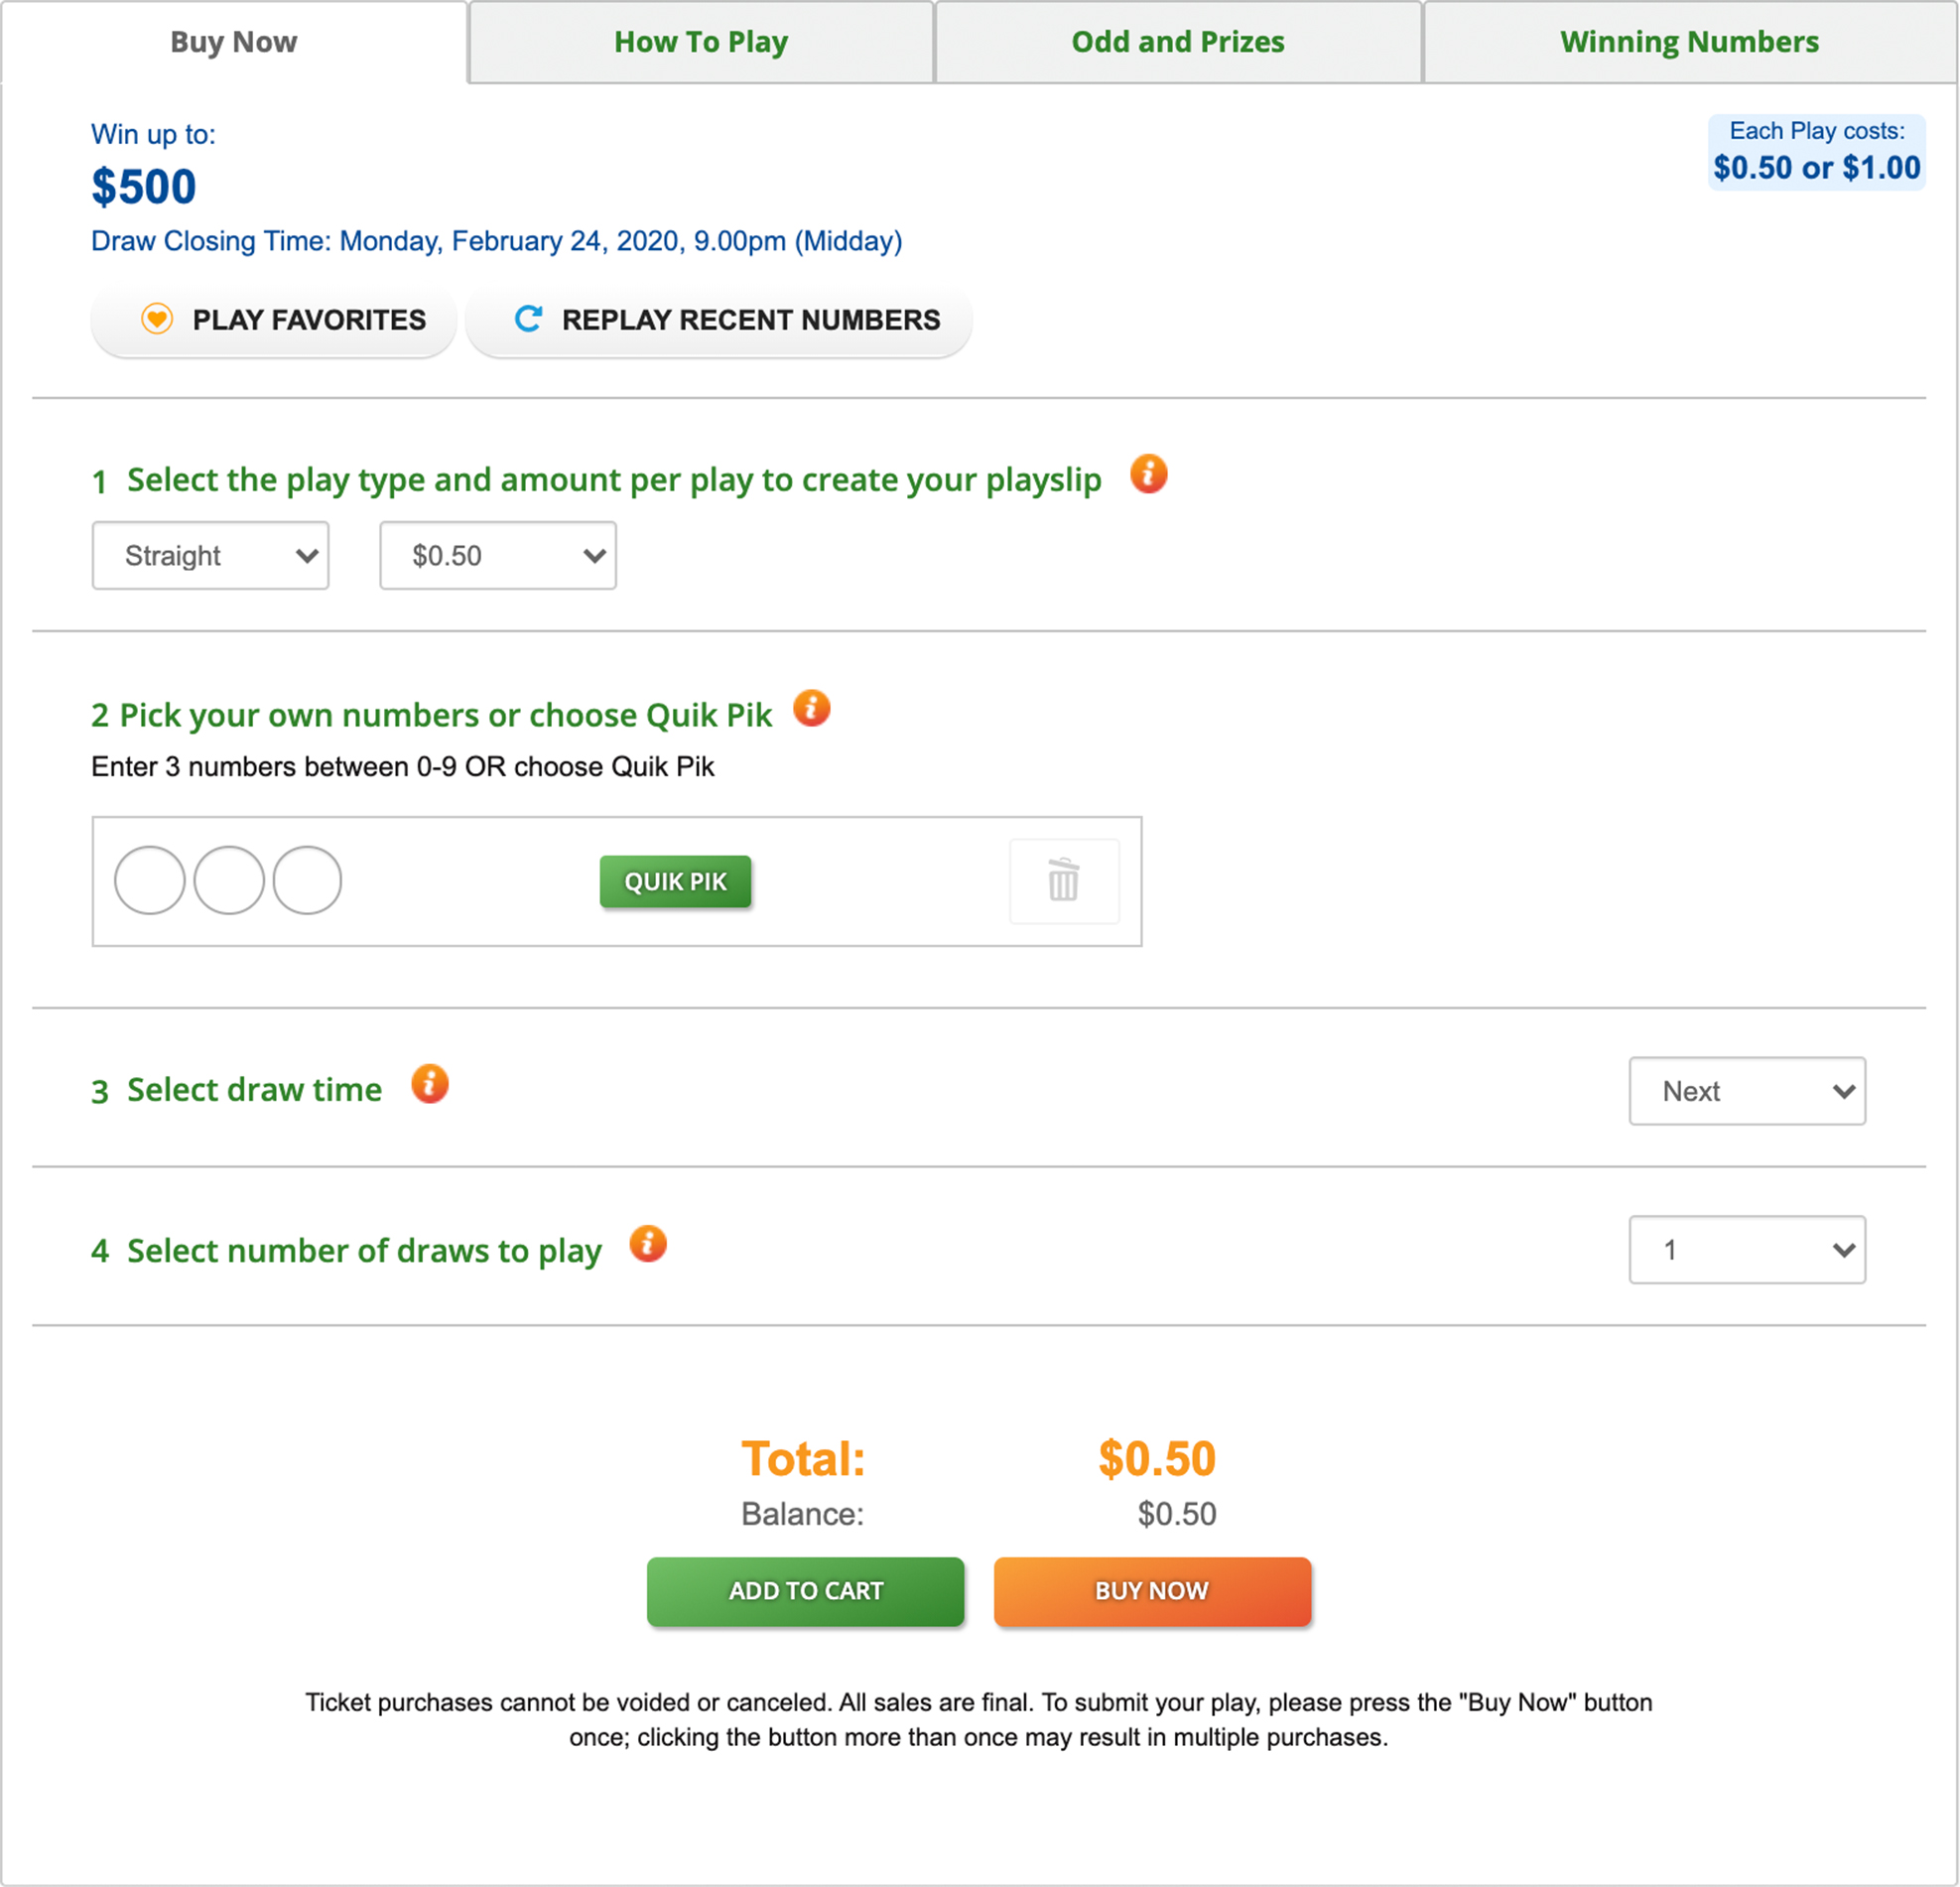
Daily lottery games, particularly the three-digit variety, occupy a unique space in the financial landscape. Unlike massive multi-state jackpots that offer hundreds of millions of dollars at astronomical odds, Cash 3 feels attainable. The mechanics are simple: pick three numbers from 0 to 9. The odds of winning the top prize on a straight play are 1 in 1,000. For many, these odds feel within the realm of possibility, leading to a psychological phenomenon known as the “availability heuristic,” where players overestimate their chances of winning because the event seems simple and frequent.
From a behavioral finance perspective, the “Cash 3” habit is often driven by the “hope factor.” For a small price—typically $0.50 or $1.00—a participant buys a ticket that serves as a placeholder for a better financial future. However, when this habit becomes a daily occurrence, it shifts from a form of entertainment to a line item in a household budget. In the world of professional money management, consistency is the key to wealth. When that consistency is applied to a negative-expectation game, it can create a silent drain on an individual’s net worth over decades.
The Micro-Transaction Trap
In the modern economy, we are accustomed to micro-transactions—small, frequent payments for apps, streaming services, or digital goods. Daily lotteries were the original micro-transaction. Because the cost of entry is so low, players often fail to aggregate the total cost over a year or a decade. A $2-a-day habit equates to $730 a year. Over thirty years, without accounting for inflation or potential investment growth, that is nearly $22,000 spent on a game where the mathematical “expected value” is significantly lower than the cost of the ticket.
The Impact of “Near Misses”
Psychologically, the Cash 3 format is designed to keep players engaged through “near misses.” If the number for tonight is 582 and a player held 581, the brain processes this not as a total loss, but as a sign that they are “close” to a win. This encourages continued play. In professional investing, a “near miss” (such as a stock that almost hit your target price) is viewed objectively as a missed opportunity or an incorrect thesis, but in the world of high-frequency gaming, it acts as a powerful reinforcement loop.
Calculating the Real Cost: Probability vs. Expectation
To manage money effectively, one must understand the difference between “possibility” and “probability.” It is possible to win the Cash 3 tonight, but the probability is 0.1%. More importantly, the expected value (EV) of a lottery ticket is almost always negative. In a standard 3-digit game, a $1 straight bet usually pays out $500. Since the odds are 1 in 1,000, the mathematical value of that $1 ticket is actually $0.50.
This means that for every dollar spent, the player is essentially “giving away” 50 cents to the state or the house. In the world of investing, a 50% immediate loss on capital would be considered a catastrophic failure. Yet, because the amounts are small, they are often overlooked in personal financial planning.
The Power of Opportunity Cost
The most significant cost of asking “what was the cash 3 number for tonight” is not the dollar spent on the ticket, but the “opportunity cost” of that dollar. Opportunity cost is a fundamental principle of economics that measures the value of the next best alternative.
If an individual took that same $30 to $60 a month spent on daily draws and placed it into a low-cost S&P 500 index fund, the historical average return of 7-10% would transform those small payments into a substantial retirement nest egg. For example, $60 a month invested over 30 years at an 8% return grows to approximately $90,000. This is the difference between chasing a $500 payout and building a nearly six-figure asset.
Understanding House Edge and Payout Ratios
Every financial tool has a cost. For a mutual fund, it’s the expense ratio. For a brokerage, it might be the spread. For the lottery, it is the “take-out rate.” Most state lotteries return only 50% to 60% of ticket sales to players in the form of prizes. Compare this to a High-Yield Savings Account (HYSA) or a Treasury Bill, where the “return” is positive and the principal is protected. When viewed through the lens of a financial instrument, the Cash 3 draw is one of the least efficient ways to allocate capital.
Integrating Gaming into a Holistic Financial Plan
It is a reality of human nature that many people enjoy the thrill of the draw. From a financial coaching perspective, the goal isn’t necessarily to eliminate every form of entertainment, but to ensure that “seeking the number for tonight” does not compromise long-term financial security. This requires the implementation of a “Fun Fund” or a strict discretionary budget.
The “Fun Fund” Strategy
A sound financial strategy involves categorizing expenses into “Needs,” “Wants,” and “Savings/Debt Repayment.” Any participation in daily draws must come strictly from the “Wants” category, and only after the “Needs” and “Savings” have been fully funded. If a player allocates $10 a week to the lottery, that $10 should be viewed as the cost of a movie ticket—money spent for entertainment that is not expected to return.
Avoiding the “Recovery” Trap
One of the most dangerous financial behaviors is “chasing losses.” This occurs when a player increases their bet size or frequency after a losing streak in hopes of breaking even. Because the Cash 3 number for tonight is an independent event—meaning tonight’s draw has no connection to last night’s draw—the odds do not “improve” just because a certain number hasn’t appeared in a while. Professional money management relies on the Law of Large Numbers to ensure stability; chasing losses relies on a misunderstanding of that same law.
Alternatives: Turning Small Wins into Long-Term Wealth
For those looking for the “thrill” of a win without the guaranteed mathematical loss, modern financial tools offer several alternatives. The rise of fintech has made it possible to engage with the markets in ways that feel as accessible as buying a lottery ticket but with a positive expected value.
Micro-Investing and Fractional Shares
In the past, the barrier to entry for the stock market was high. Today, apps allow users to buy “fractional shares” of major companies for as little as $1. Instead of picking three numbers for a nightly draw, an individual can pick three blue-chip companies or an ETF. This shifts the mindset from “gambling” to “ownership.” Over time, the dividends and capital appreciation from these fractional shares provide a “win” that is backed by economic productivity rather than random chance.
Prize-Linked Savings Accounts (PLSAs)
A relatively new innovation in the personal finance space is the Prize-Linked Savings Account. These accounts offer the best of both worlds: they provide the excitement of a lottery draw while protecting the user’s principal. In a PLSA, instead of paying for a ticket, you deposit money into a savings account. For every dollar you save, you get an entry into a drawing for cash prizes. If you don’t win, you still have your original dollar, plus a small amount of interest. This “gamifies” saving and aligns the user’s desire for a windfall with their need for financial stability.
The Side Hustle as a “Guaranteed” Win
If the goal of playing Cash 3 is to gain an extra $500, the most reliable way to achieve that is through a side hustle or freelance work. In the modern gig economy, performing a specialized task for a few hours a week can generate a consistent “payout” that far exceeds the statistical likelihood of winning a daily draw. Investing in one’s own skills—whether it’s digital marketing, coding, or even manual labor—offers a Return on Investment (ROI) that no lottery can match.
Developing a Sophisticated Financial Mindset
Ultimately, the quest to find “what was the cash 3 number for tonight” is a symptom of a desire for financial freedom. However, true financial freedom is rarely found in the results of a random number generator. It is constructed through the disciplined application of financial principles, the understanding of compound interest, and the mitigation of unnecessary risk.
Moving from Event-Based Wealth to Process-Based Wealth
Most people view wealth as an “event”—a big win, an inheritance, or a lucky break. Professional wealth builders view wealth as a “process.” The process involves living below one’s means, investing the surplus, and protecting assets from inflation and high-risk gambles. When you shift your focus from the “result of the draw” to the “health of the balance sheet,” your relationship with money changes. You stop looking for a lucky three-digit combination and start looking for undervalued assets and growth opportunities.
The Role of Financial Literacy
Education is the ultimate hedge against poverty. Understanding how the “Cash 3” system works—from the state’s revenue goals to the mathematical impossibility of a long-term winning strategy—empowers individuals to make better choices. When a consumer realizes that the lottery is essentially a voluntary tax on those who do not understand math, they are more likely to redirect those funds toward vehicles that build generational wealth.
In conclusion, while the daily search for the winning numbers provides a momentary spark of interest, the path to genuine financial security is paved with more deliberate actions. By treating the lottery as a minor expense rather than a financial strategy, and by embracing modern investment tools and the power of compounding, anyone can move from the uncertainty of the draw to the certainty of a well-managed financial future. The real “winning number” isn’t drawn tonight; it’s the number reflected in your savings and investment accounts after years of smart, calculated decisions.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.