
The daily ritual of checking lottery results is a habit shared by millions of individuals looking for a break in their financial routine. Whether you are playing in Georgia, Florida, Tennessee, or any of the numerous states that offer a “Cash 3” or “Pick 3” style game, the anticipation of the draw is a constant in the world of low-stakes wagering. However, beyond the immediate curiosity of the winning digits, there lies a complex landscape of financial probability, personal money management, and strategic play that defines this popular numbers game.
Understanding “what was last night’s Cash 3 number” is often the starting point for a broader conversation about how small-scale gaming intersects with personal finance. While the draw results change every evening—and often twice a day with midday and evening drawings—the principles of how to approach these games remain constant.
Understanding the Mechanics of Cash 3 Games
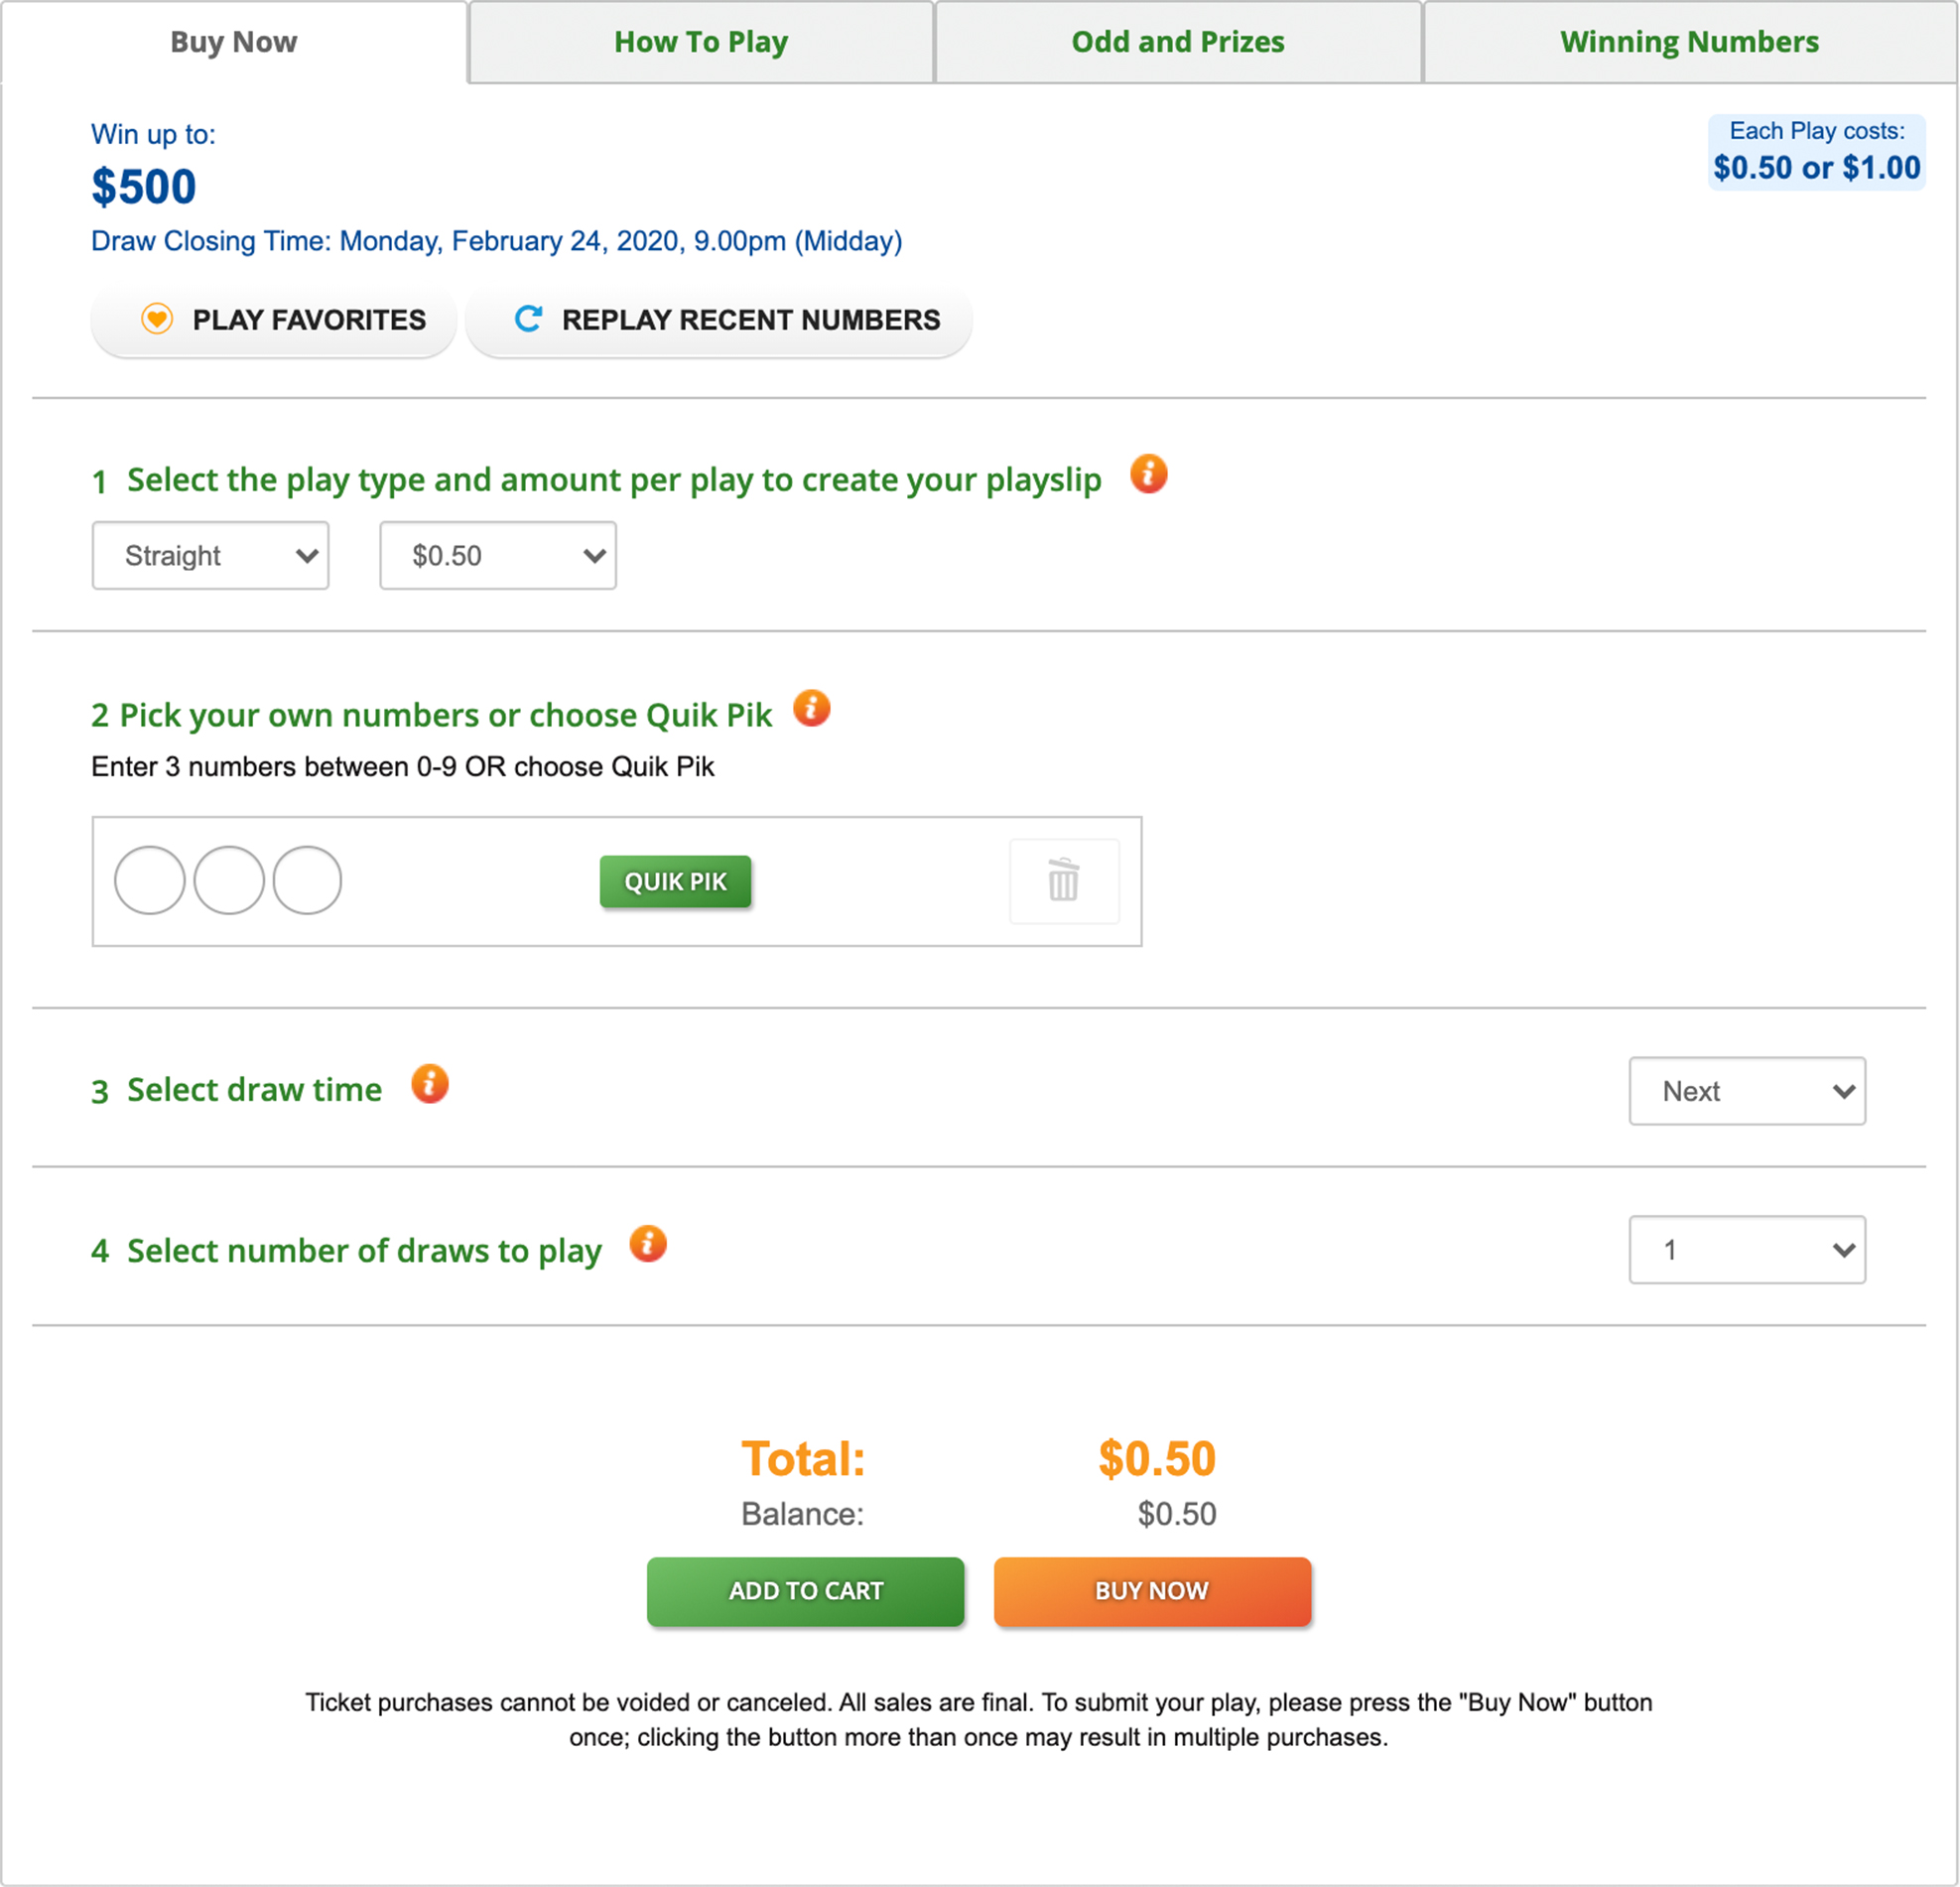
Cash 3 is a fixed-odds lottery game that requires players to select a three-digit number from 000 to 999. Its popularity stems from its simplicity and the high frequency of drawings, which provides immediate feedback compared to multi-state power lotteries that only draw a few times a week.
How the Draw Works
The mechanics are straightforward: three separate chambers or digital random number generators (RNG) select one digit each, ranging from 0 to 9. Because each position is independent, the number 1-1-1 has the same statistical probability of appearing as 3-7-2 or 9-0-5. For the participant, the goal is to match these numbers based on the specific type of wager placed.
Most state lotteries offer two draws daily. The “Midday” draw typically occurs in the early afternoon, while the “Evening” draw—the one most people refer to when asking about “last night’s number”—usually takes place between 7:00 PM and 11:00 PM, depending on the jurisdiction. The results are broadcast live and then disseminated through official lottery apps, websites, and authorized retailers.
Common Variations: Straight, Box, and Pairs
To maximize the utility of your financial outlay, it is essential to understand the different ways to play. In the Money niche, we view these as different risk-to-reward ratios:
- Straight Play: You must match the three digits in the exact order drawn. This carries the highest payout (usually $500 on a $1 bet) but the lowest probability of winning (1 in 1,000).
- Box Play: You win if your numbers are drawn in any order. If you choose 1-2-3, you win if the result is 3-2-1, 2-3-1, etc. The odds are better, but the payout is lower.
- Straight/Box: A hybrid wager where you split your bet between both types, providing a safety net if the numbers match but are out of sequence.
- Pairs: Some states allow you to bet only on the “Front Pair” or “Back Pair,” further diversifying the ways you can engage with the draw.
Tracking Results and Managing Financial Windfalls
For many, checking the previous night’s numbers is a task performed over morning coffee. In the digital age, the methods for verifying these results have become increasingly sophisticated, allowing for better financial tracking and record-keeping.
Reliable Sources for Real-Time Updates
To ensure accuracy, players should rely on official channels. While third-party websites often aggregate numbers, the official state lottery website or mobile app is the only definitive source. From a financial security perspective, relying on unverified sources can lead to “false positives” or, worse, missing a legitimate win because of a typo on a secondary blog.
Most modern lottery apps now include a ticket-scanning feature. By using the camera on your smartphone, you can instantly determine if your ticket is a winner. This eliminates human error in pattern recognition—something that is surprisingly common when dealing with three-digit sequences.
The Importance of Immediate Verification
In the realm of personal finance, time is money. Most lottery tickets have an expiration date, typically ranging from 90 to 180 days after the drawing. While a Cash 3 win might only result in a $40 to $500 payout, failing to claim these funds is essentially leaving money on the table. Consistent verification is part of a disciplined financial habit, ensuring that every asset you own—including a winning ticket—is accounted for and processed.
The Mathematics of the Draw: Odds vs. Potential Returns
To treat Cash 3 with professional financial scrutiny, one must look at the “House Edge.” Unlike the stock market or high-yield savings accounts, where the goal is a positive expected return, lottery games are designed with a built-in advantage for the operator.
Calculating the House Edge
In a standard Cash 3 game, there are 1,000 possible combinations (000 through 999). If you play a “Straight” bet for $1, your statistical chance of winning is 0.1%. A fair payout—one with no house edge—would be $1,000. However, most states pay out $500. This means the “Return to Player” (RTP) is 50%.
From a wealth-building perspective, this is a significant hurdle. For every dollar spent over a long enough timeline, the average player will lose 50 cents. Understanding this math is crucial for anyone who wants to maintain a healthy relationship with their finances. While “last night’s number” might have been your lucky combination, the long-term data suggests that these games should be categorized as “entertainment expenses” rather than “investments.”
Strategic Play vs. Random Probability
Many players use “wheeling systems” or track “hot and cold” numbers. Financial analysts, however, view these through the lens of the Gambler’s Fallacy. Because each draw is an independent event, the fact that “7” hasn’t appeared in the lead position for ten days does not make it any more likely to appear tonight.
Professional financial strategies regarding the lottery often focus on “Budgeted Play.” This involves setting a strict limit on how much capital is allocated to these games, ensuring that the pursuit of the “Cash 3” jackpot never infringes upon essential obligations like rent, insurance, or retirement contributions.
Incorporating Lottery Play into a Modern Financial Strategy
Is there a place for the Cash 3 draw in a sophisticated financial plan? The answer lies in the psychological concept of “Mental Accounting.” If managed correctly, small-stakes gaming can serve as a controlled outlet for risk-taking.
Entertainment Budgeting vs. Investing
The most successful participants in the economy are those who can distinguish between different types of capital. “Investment Capital” is money directed toward assets that appreciate over time (stocks, real estate, education). “Entertainment Capital” is money spent on experiences (movies, dining, gaming).
When you ask “what was last night’s number,” you are engaging with an entertainment product. To keep your finances healthy, this expenditure should be a line item in your monthly budget, much like a streaming subscription. If you spend $5 a week on Cash 3, that’s $260 a year. As long as that $260 isn’t being pulled from your 401(k) contributions, it is a manageable discretionary expense.
Tax Implications of Lottery Winnings
In the event that you do match last night’s numbers, it is important to understand the tax landscape. In the United States, lottery winnings are considered gambling income and are taxable at both the federal and, in most cases, state levels.
For a $500 win, the lottery office usually does not withhold taxes at the source, but you are still legally required to report the income on your tax return. However, you can also deduct gambling losses up to the amount of your winnings, provided you keep accurate records and receipts. This is why keeping your losing tickets can actually be a savvy financial move—they serve as documentation to offset the tax liability of your wins.
Responsible Gaming and Long-Term Wealth Building
The allure of the Cash 3 number is the “micro-win”—the $40 or $500 that can cover a grocery bill, a car payment, or a night out. While these wins provide a short-term dopamine hit and a minor liquidity boost, they are rarely the foundation of true wealth.
The Power of Compound Interest
To put the Cash 3 game in perspective, consider the alternative use of those funds. If a person spends $10 a week on lottery tickets from age 25 to 65, they will have spent approximately $20,800. If that same $40 per month were invested in a low-cost index fund returning an average of 7% annually, it would grow to nearly $100,000 over the same period.
This comparison isn’t meant to discourage the occasional play, but rather to provide the financial context necessary for making informed decisions. The search for “last night’s number” should be balanced with a robust focus on automated savings and diversified investing.
Conclusion: The Balanced Approach
Checking the Cash 3 results is a moment of possibility. Whether the numbers were 1-2-3 or 9-8-7, the real “win” is found in maintaining a disciplined approach to one’s financial life. By understanding the odds, managing the tax implications, and keeping the cost of play within a dedicated entertainment budget, you can enjoy the thrill of the draw without compromising your long-term financial security.
The next time you search for the winning numbers, do so with the confidence of someone who knows exactly how those numbers fit into their broader financial picture. Winning is a matter of luck, but financial stability is a matter of strategy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.