
A fall on concrete is rarely just a physical event; it is a significant financial disruption. Whether the incident occurs on a commercial property, a public sidewalk, or within a workplace, the immediate aftermath sets the stage for how much the accident will cost you—or how much you will be able to recover. Beyond the bruises and fractures, the “concrete fall” triggers a complex series of financial and legal mechanisms involving insurance adjusters, liability assessments, and medical billing cycles.
Understanding the fiscal roadmap after a slip-and-fall is essential for protecting your personal assets and ensuring that a single moment of impact does not lead to years of debt. This guide outlines the strategic steps necessary to manage the financial repercussions of a fall on concrete, focusing on insurance navigation, liability recovery, and long-term financial planning.
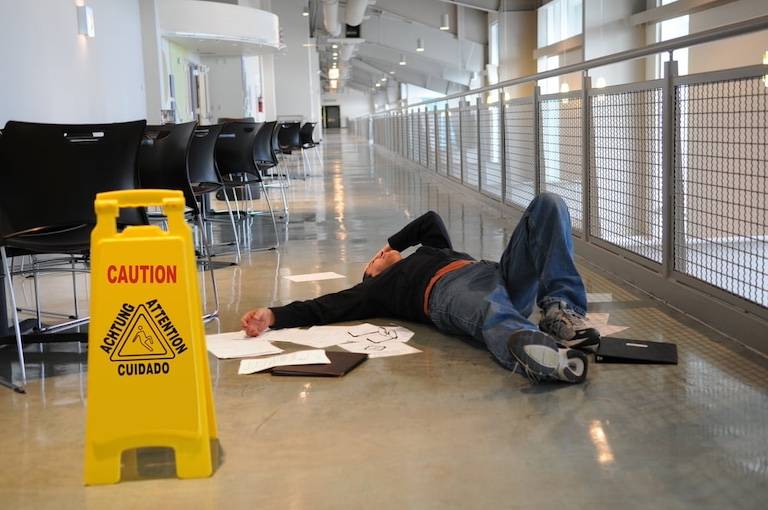
Immediate Documentation: Building the Foundation for a Financial Claim
The moment you regain your footing, you are no longer just a victim of an accident; you are a claimant in a potential financial recovery action. The success of an insurance claim or a personal injury lawsuit depends almost entirely on the quality of evidence gathered in the minutes following the fall.
Capturing the Scene for Liability Proof
Concrete is a unforgiving surface, but it is also a tell-tale one. From a financial perspective, you must identify what caused the fall to determine who is liable. Was there an uneven expansion joint? Was there ice, grease, or a structural crack that violated local building codes?
Using your smartphone to document the exact location and the specific hazard is the most important financial action you can take. High-resolution photos of the defect, the surrounding lighting conditions, and the absence of warning signs provide the leverage needed when negotiating with corporate insurance adjusters. These adjusters are incentivized to minimize payouts; visual evidence makes it harder for them to argue that the victim was solely at fault.
The Paper Trail: Incident Reports and Witnesses
If the fall occurs on a business’s property, filing an official incident report is mandatory for financial protection. This report serves as a “time-stamp” for your claim. Ensure that you receive a physical or digital copy of this report before leaving the premises.
Simultaneously, identify any witnesses. In the world of personal finance and legal settlements, a third-party account is an invaluable asset. Their testimony can validate your version of events, preventing a “he-said, she-said” scenario that often leads to a denied insurance claim. Collect names and contact information immediately; this data is the currency of a successful settlement negotiation.
Navigating Medical Expenses and Insurance Coverage
The financial burden of a fall on concrete begins at the emergency room or urgent care center. Even minor falls can result in hidden internal injuries or concussions that require expensive imaging like MRIs or CT scans. Managing these costs requires a strategic approach to insurance coordination.
Understanding Health Insurance Subrogation
Many individuals assume their health insurance will cover everything, but there is a financial nuance known as subrogation. If you receive a settlement from a property owner’s liability insurance, your health insurance provider may have a legal right to be reimbursed for the medical bills they paid on your behalf.
Managing this requires careful tracking of all “Explanation of Benefits” (EOB) documents. To protect your personal savings, you must ensure that medical providers are billing the correct entities. In some cases, if the fall happened at a business, their “Med-Pay” coverage might cover your initial bills regardless of fault, which can prevent you from having to pay high deductibles out of pocket.
The Hidden Costs of Rehabilitation
Financial recovery isn’t just about the initial ER bill. The long-term impact of falling on a hard surface like concrete often involves physical therapy, specialist consultations, and sometimes home modifications. When calculating the financial “value” of your fall, you must look beyond the current invoices. Professional financial planning after an injury involves projecting these costs out for months or even years. Failing to account for future medical inflation and ongoing therapy needs in a settlement can leave you in a deficit once the initial funds are exhausted.
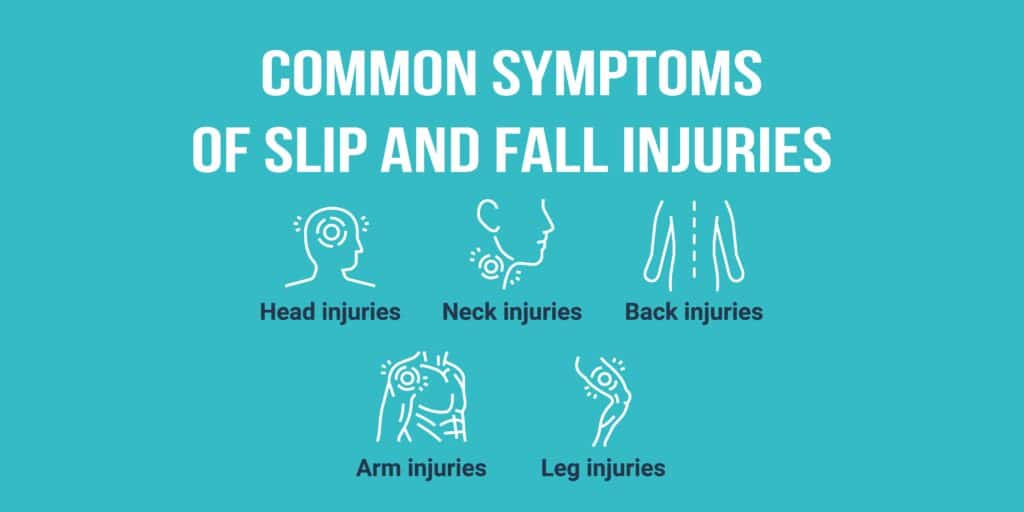
The Legal Landscape: Liability, Negligence, and Settlement Potential
When a fall results in significant medical debt or lost wages, the transition from “accident” to “legal claim” becomes a necessary financial strategy. The goal is to shift the financial burden from your personal bank account to the entity responsible for the unsafe concrete.
Proving Negligence as a Financial Strategy
To win a financial settlement, you must prove negligence. This involves demonstrating that the property owner knew, or should have known, about the hazardous concrete condition and failed to fix it. From a business finance perspective, property owners have a “duty of care” to maintain safe premises.
If the concrete was cracked for months, that constitutes a breach of duty. Understanding the “Reasonable Person Standard” is key here: Would a reasonable property owner have fixed that hole? If the answer is yes, the property owner’s insurance is on the hook for your damages, including medical bills, lost income, and “pain and suffering,” which is a calculated financial multiplier used to compensate for the disruption of your life.
The Role of a Personal Injury Attorney
While many people are hesitant to hire an attorney, doing so is often a calculated financial move. Most personal injury lawyers work on a contingency fee basis, meaning they only get paid if you win. Statistically, settlements negotiated by legal professionals are significantly higher than those handled by individuals. An attorney acts as a financial advocate, identifying all possible avenues of recovery, including umbrella insurance policies that a layperson might overlook.
Workers’ Compensation vs. Personal Injury: Understanding Your Income Streams
If your fall on concrete occurred while you were on the clock, the financial recovery process shifts into the realm of Workers’ Compensation. This is a “no-fault” system, which has both benefits and drawbacks for your personal finances.
The Benefits of Workers’ Comp
In a Workers’ Comp scenario, you do not have to prove the employer was negligent. As long as the fall happened within the scope of your employment, the insurance should cover all medical expenses and a portion of your lost wages (usually around 66%). This provides a faster, though often lower, financial safety net compared to a traditional lawsuit. It ensures a steady stream of income while you are unable to work, protecting your credit score and ability to pay monthly bills.
The “Third-Party” Financial Claim
Sometimes, a fall at work involves a third party—for example, if you are a delivery driver who falls on a poorly maintained concrete stairs at a client’s warehouse. In this case, you may have two financial avenues: a Workers’ Comp claim through your employer and a personal injury claim against the property owner. Coordinating these two claims requires sophisticated financial management to ensure that “double-dipping” rules are followed while maximizing the total recovery amount.
Long-Term Financial Planning Following a Major Injury
A significant fall can alter your earning capacity. If you work in a field that requires physical labor or mobility, a permanent injury from a concrete impact can jeopardize your primary source of income.
Assessing Impact on Earning Capacity
One of the most overlooked aspects of financial recovery is the “loss of future earning capacity.” This is an economic calculation of what you would have earned had the accident not occurred versus what you are now capable of earning. If a fall results in chronic back pain that prevents you from working overtime or pursuing promotions, that loss has a tangible dollar value. Financial experts and vocational consultants are often brought in to quantify this loss, ensuring that your settlement reflects the lifetime cost of the injury.
Protecting Your Settlement and Assets
Once a settlement is reached, the focus shifts to asset protection. Large lump-sum settlements should be managed with the help of a financial advisor to ensure they last. Options like “Structured Settlements”—where payments are distributed over many years—can provide tax-advantaged income and ensure that the money isn’t depleted too quickly.
Furthermore, if the fall resulted in a temporary disability, it is vital to review your personal financial portfolio. Adjusting your investment risk, tapping into disability insurance policies, and potentially seeking a mortgage forbearance if you are out of work for an extended period are all proactive steps to maintain your financial health.
Ultimately, “what to do after a fall on concrete” is a question of both physical and fiscal resilience. By treating the accident with the same rigor you would a business transaction—documenting everything, understanding the insurance contracts, and aggressively pursuing the compensation you are owed—you can mitigate the damage and ensure that your financial future remains on solid ground.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.