
The question of what movie theaters are open today is no longer a matter of checking local health ordinances, as it was in the early 2020s. Instead, it has become a complex inquiry into the fiscal health, debt structures, and operational solvency of the global exhibition industry. For investors, financial analysts, and business enthusiasts, the “open” sign on a theater marquee represents a hard-won battle of balance sheet restructuring and the pivot toward a high-margin, experiential business model. As the industry stabilizes, understanding which theaters remain operational requires an analysis of the economic forces at play, from the dominance of major equity-backed chains to the niche survival of independent luxury houses.

The Financial Health of Global Exhibition Giants
The landscape of open theaters is dominated by three major players: AMC Entertainment, Cinemark Holdings, and Cineworld (owner of Regal Cinemas). Each of these entities has navigated the high-interest-rate environment and the post-pandemic recovery with different financial strategies, impacting their market share and the geographic distribution of their “open” locations.
AMC Entertainment and the Retail Investor Influence
AMC Entertainment stands as the largest theater chain in the world, but its ability to keep its doors open has been a masterclass in aggressive capital raising. Unlike traditional companies that rely purely on cash flow from operations, AMC leveraged its status as a “meme stock” to raise billions of dollars in equity. This infusion of capital allowed the company to pay down high-interest debt and fund the renovation of its most profitable locations into “premium” sites.
From a business finance perspective, AMC’s strategy has been to trade equity for time. By issuing millions of new shares, the company diluted existing shareholders but secured the liquidity needed to keep its massive footprint operational. For the individual investor, AMC remains a high-beta play, heavily influenced by retail sentiment and the company’s ability to manage its remaining debt load through 2026.
Cinemark’s Fiscal Discipline and Market Stability
In contrast to AMC, Cinemark Holdings has often been cited by financial analysts as the most stable investment in the sector. Cinemark’s approach to keeping theaters open has been rooted in fiscal discipline and a lean operational structure. By maintaining a stronger balance sheet and lower leverage ratios prior to the industry downturn, Cinemark avoided the desperate capital raises seen elsewhere. Their theaters, primarily located in suburban markets and throughout Latin America, have shown a faster return to pre-2019 EBITDA levels. For those looking at the “Money” niche, Cinemark represents the value-investing side of the industry—prioritizing consistent margins and manageable CAPEX (Capital Expenditure) over rapid, debt-fueled expansion.
The Restructuring of Regal (Cineworld)
The status of Regal Cinemas was uncertain for a significant period during the Chapter 11 bankruptcy proceedings of its parent company, Cineworld. However, the restructuring process allowed the company to shed billions in debt and renegotiate hundreds of unfavorable leases. Today, the “open” status of Regal locations is the result of a leaner, more efficient corporate entity. The bankruptcy process, while painful for creditors, essentially reset the company’s financial clock, allowing it to compete more effectively with AMC and Cinemark for blockbuster content.
The Business Model Pivot: From Volume to Value
The theaters that have remained open and thrived are those that have successfully pivoted their revenue models. The old cinema economy was built on “filling seats”—a volume-based approach where ticket sales were the primary metric of success. The modern, financially viable theater operates on a “value-per-guest” model.
High-Margin Concessions and the “Kitchen” Model
It is a well-known secret in business finance that movie theaters do not make significant money on ticket sales, especially during the opening weeks of a film when studios take upwards of 60-70% of the gate. The real profit centers are the concession stands. Modern theaters have expanded this into full-service dining and alcohol sales.
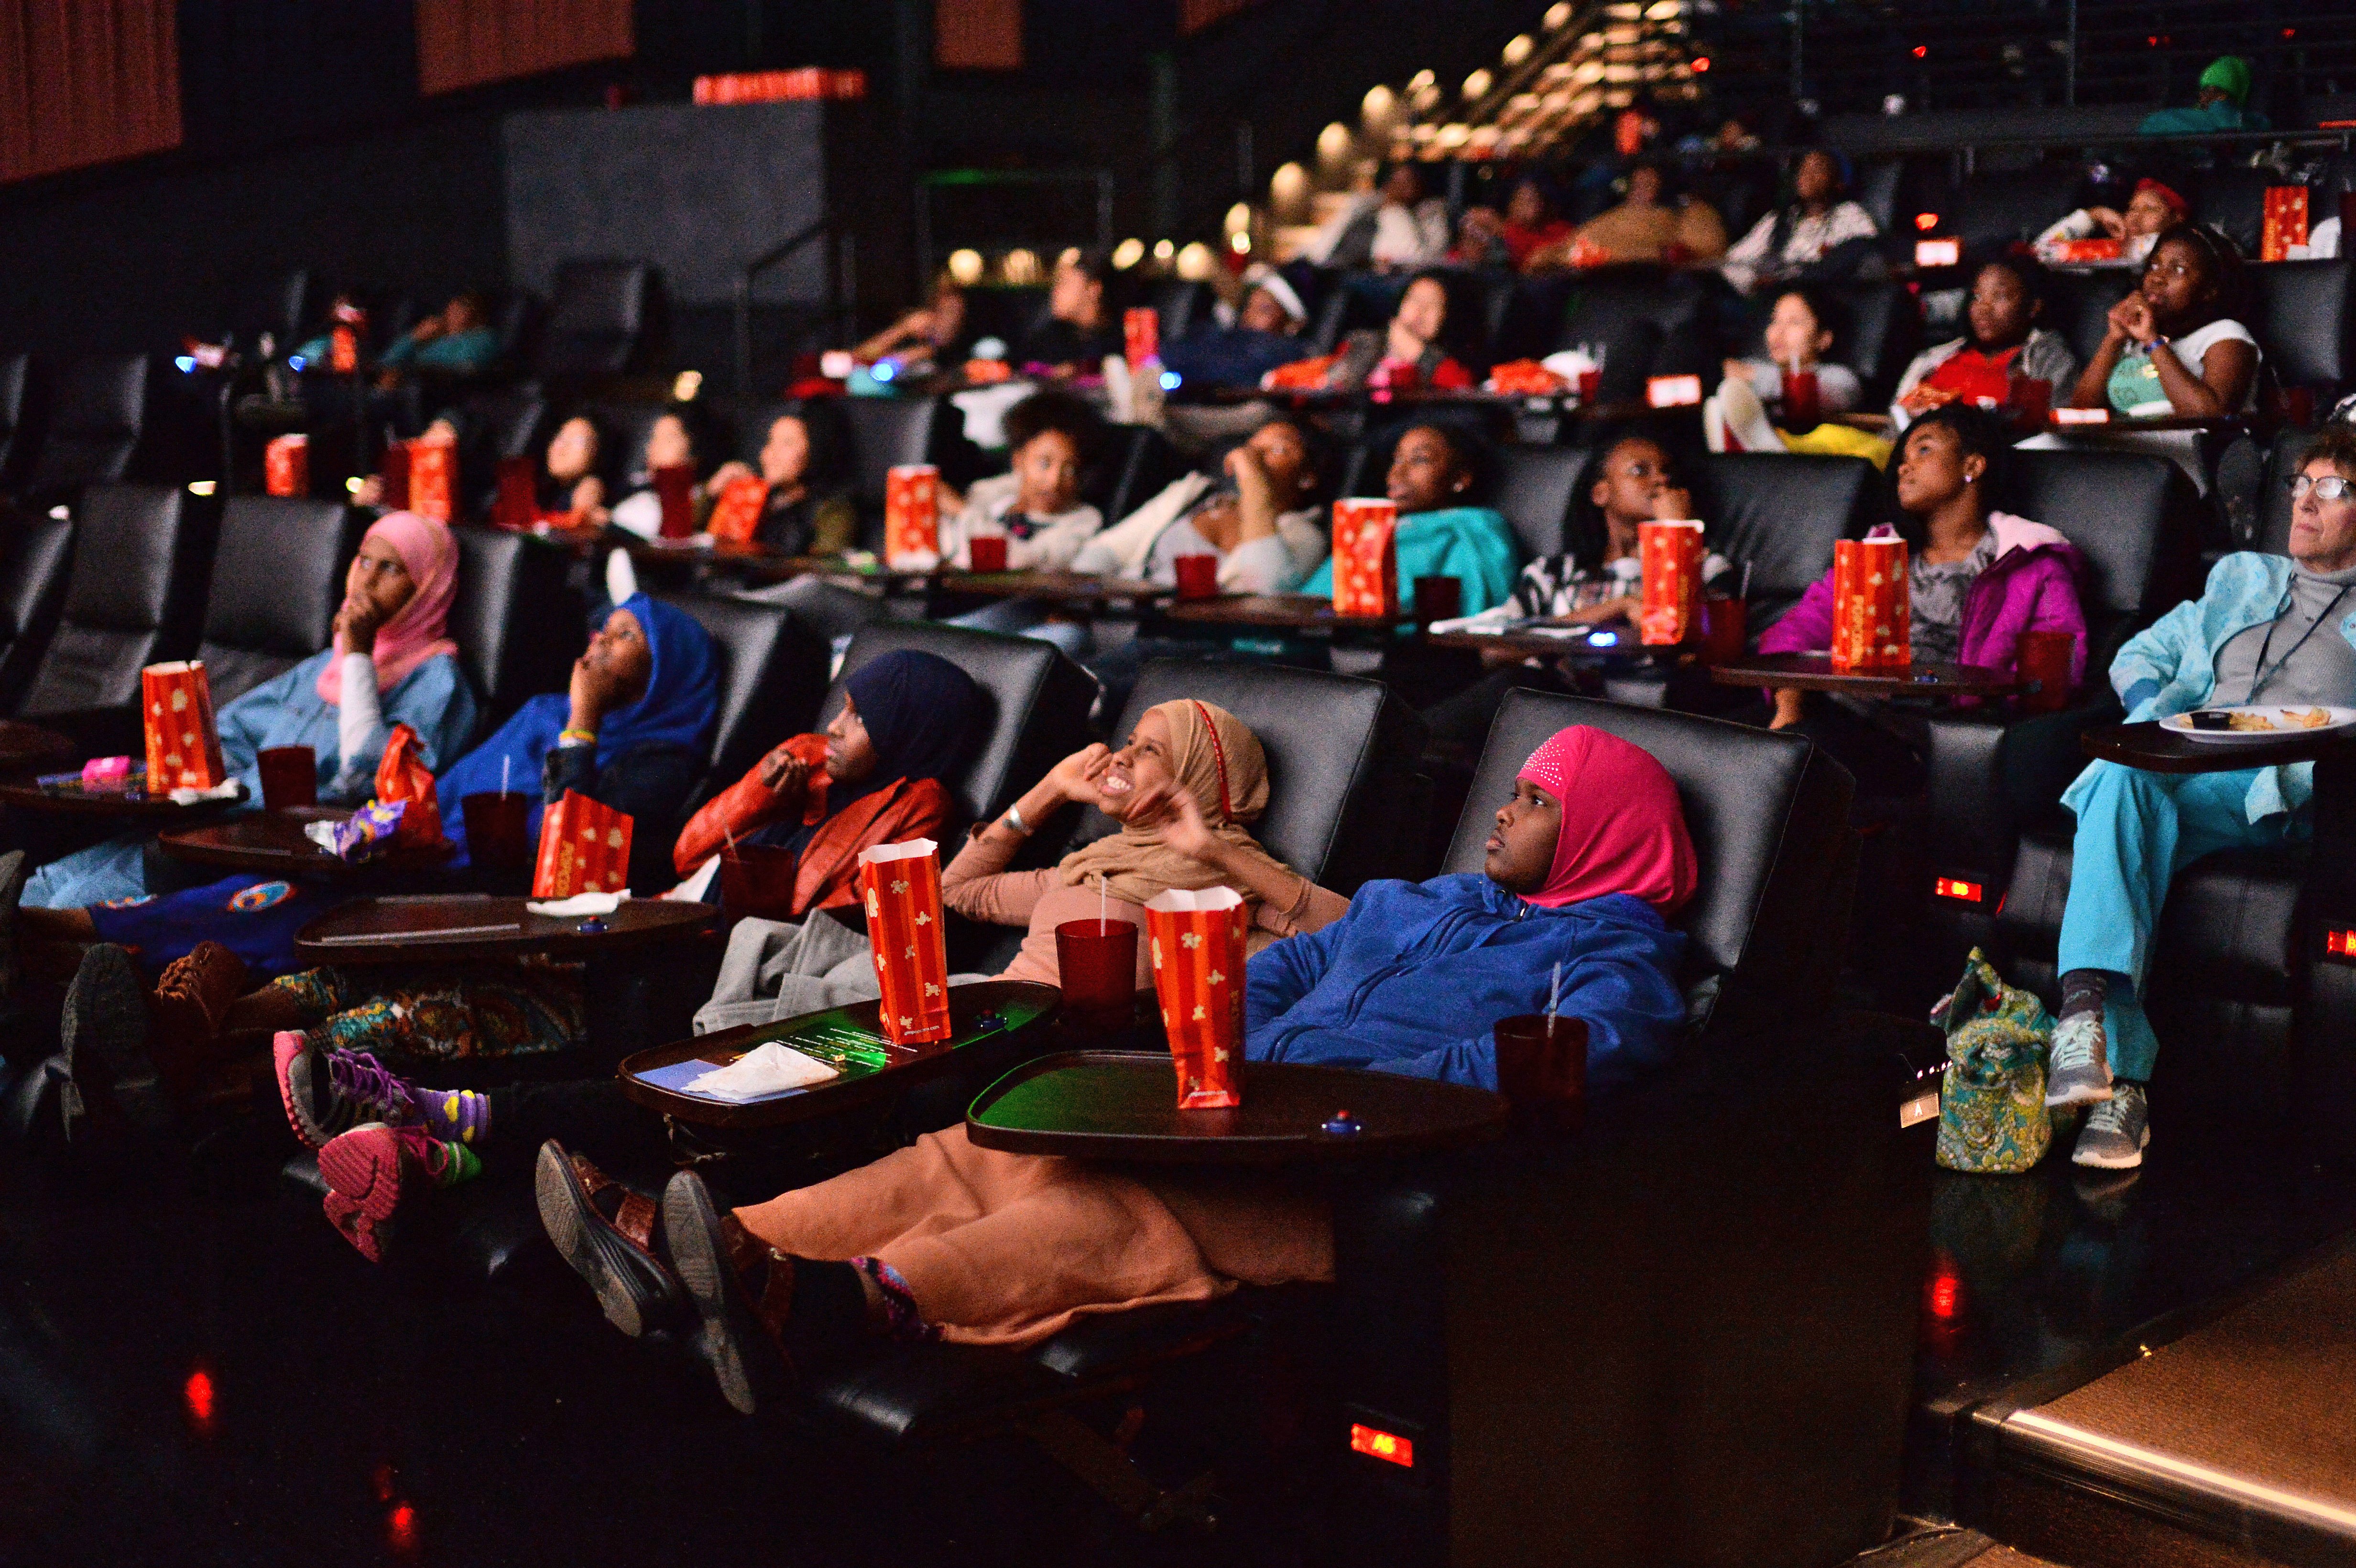
Alcoholic beverages and gourmet food items carry significantly higher margins than traditional popcorn and soda. By integrating “Dine-In” technology and service, theaters have transformed from simple screening rooms into high-end hospitality venues. This shift has allowed theaters to remain open even during periods of lower box office volume, as the average revenue per user (ARPU) has skyrocketed.
The Rise of Premium Large Format (PLF)
Investment in technology has become a prerequisite for staying open. IMAX, ScreenX, and proprietary brands like AMC’s Dolby Cinema are the primary drivers of growth. Consumers have demonstrated a willingness to pay a 20-50% premium for an experience they cannot replicate at home. From a CAPEX perspective, while installing an IMAX screen is expensive, the return on investment (ROI) is significantly higher due to the increased ticket price and the higher occupancy rates these screens command. Data shows that PLF screens often account for a disproportionate amount of a film’s total gross, making them the most valuable assets on a theater’s balance sheet.
Real Estate and the REIT Perspective
When asking what movie theaters are open, one must look at who owns the land beneath the popcorn machines. Real Estate Investment Trusts (REITs) are the silent partners in the cinema industry. Companies like EPR Properties (NYSE: EPR) own hundreds of theater properties and lease them back to operators like AMC and Regal.
The Triple-Net Lease Model
Most major theaters operate under triple-net leases, where the tenant (the theater chain) is responsible for taxes, insurance, and maintenance. For the REIT investor, theaters represent a high-yield, if somewhat risky, asset class. During the industry’s recent volatility, REITs had to work closely with tenants to defer rent or restructure leases to prevent mass closures. The theaters that are open today are often those where the landlord and tenant found a symbiotic financial path forward.
Alternative Use and Valuation
The financial community also looks at the “residual value” of theater real estate. In areas where theaters could not remain solvent, properties are being repurposed into medical offices, warehouses, or multi-family housing. The theaters that remain open are those where the “highest and best use” of the land remains cinematic exhibition—typically in high-traffic retail hubs where the theater serves as an anchor tenant, driving foot traffic to surrounding restaurants and retail stores.
Subscription Models and Recurring Revenue
Perhaps the most significant financial innovation in the theater industry over the last decade has been the shift toward subscription-based revenue. Borrowing a page from the software-as-a-service (SaaS) industry, theater chains have introduced loyalty programs like AMC Stubs A-List and Regal Unlimited.
Predictable Cash Flow
From a business finance perspective, subscriptions provide something the box office traditionally lacks: predictability. Instead of relying on a “hit-driven” model where revenue fluctuates wildly based on the quality of Hollywood’s output, subscription models provide a steady stream of recurring monthly revenue. This cash flow helps theaters manage their fixed costs, such as labor and utilities, during “shoulder” periods between major blockbuster releases.
Data as an Asset
Furthermore, these programs allow theaters to collect massive amounts of consumer data. Knowing exactly who is seeing what movie, at what time, and what snacks they are buying allows for precision marketing. In the world of modern finance, this first-party data is a valuable intangible asset that can be leveraged to increase concession sales and optimize screening schedules through AI-driven analytics.
The Impact of the Theatrical Window on Profitability
The financial viability of “open” theaters is intrinsically linked to the “theatrical window”—the period of time a movie plays exclusively in theaters before moving to streaming or VOD (Video on Demand).
Negotiating with Studios
The tension between theater owners and studios (like Disney, Warner Bros., and Universal) is a central theme in industry finance. A longer window benefits the theater’s bottom line, while a shorter window allows studios to recoup their marketing spend faster through digital sales. Currently, the industry has settled on a flexible window of approximately 17 to 45 days, depending on the film’s performance.
This compromise has stabilized the theatrical business model. It ensures that “event” films have enough time to generate the ticket and concession revenue necessary to keep the theater operational, while acknowledging the reality of the streaming era. For investors, the return of theatrical exclusivity for major tentpole films has been the single most important factor in the recovery of cinema stocks.
Future Trends: Consolidation and Diversification
As we look at the financial trajectory of the cinema industry, the theaters that remain open will likely belong to fewer, larger entities. Consolidation is expected as smaller, independent chains struggle with the high cost of digital upgrades and the bargaining power of major studios.
M&A Activity
The exhibition industry is ripe for mergers and acquisitions. We may see tech giants or streaming platforms acquire theater chains to gain a physical foothold for their original content and to qualify for prestigious awards like the Oscars. Such an acquisition would fundamentally change the valuation metrics of theaters from standalone cash-flow businesses to marketing arms of larger tech ecosystems.
Diversified Content Streams
To maximize the utility of their square footage, theaters are increasingly looking at non-film content. Live sports, concerts (such as the highly successful Taylor Swift and Beyoncé concert films), and e-sports tournaments represent high-margin opportunities to fill seats during traditional “dead” times, such as mid-week mornings or weekday afternoons. These alternative revenue streams are essential for the long-term financial health of the sector, ensuring that “open” theaters remain profitable 365 days a year.
In conclusion, the question of which movie theaters are open is a window into a dynamic and resilient sector of the economy. Through strategic debt management, a pivot toward premium experiences, and the adoption of subscription-based revenue models, the theatrical exhibition industry has rewritten its financial playbook. For the savvy investor or business professional, the cinema remains a compelling case study in how a traditional brick-and-mortar industry can adapt to the digital age by focusing on the unique value of a shared, high-tech experience.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.