
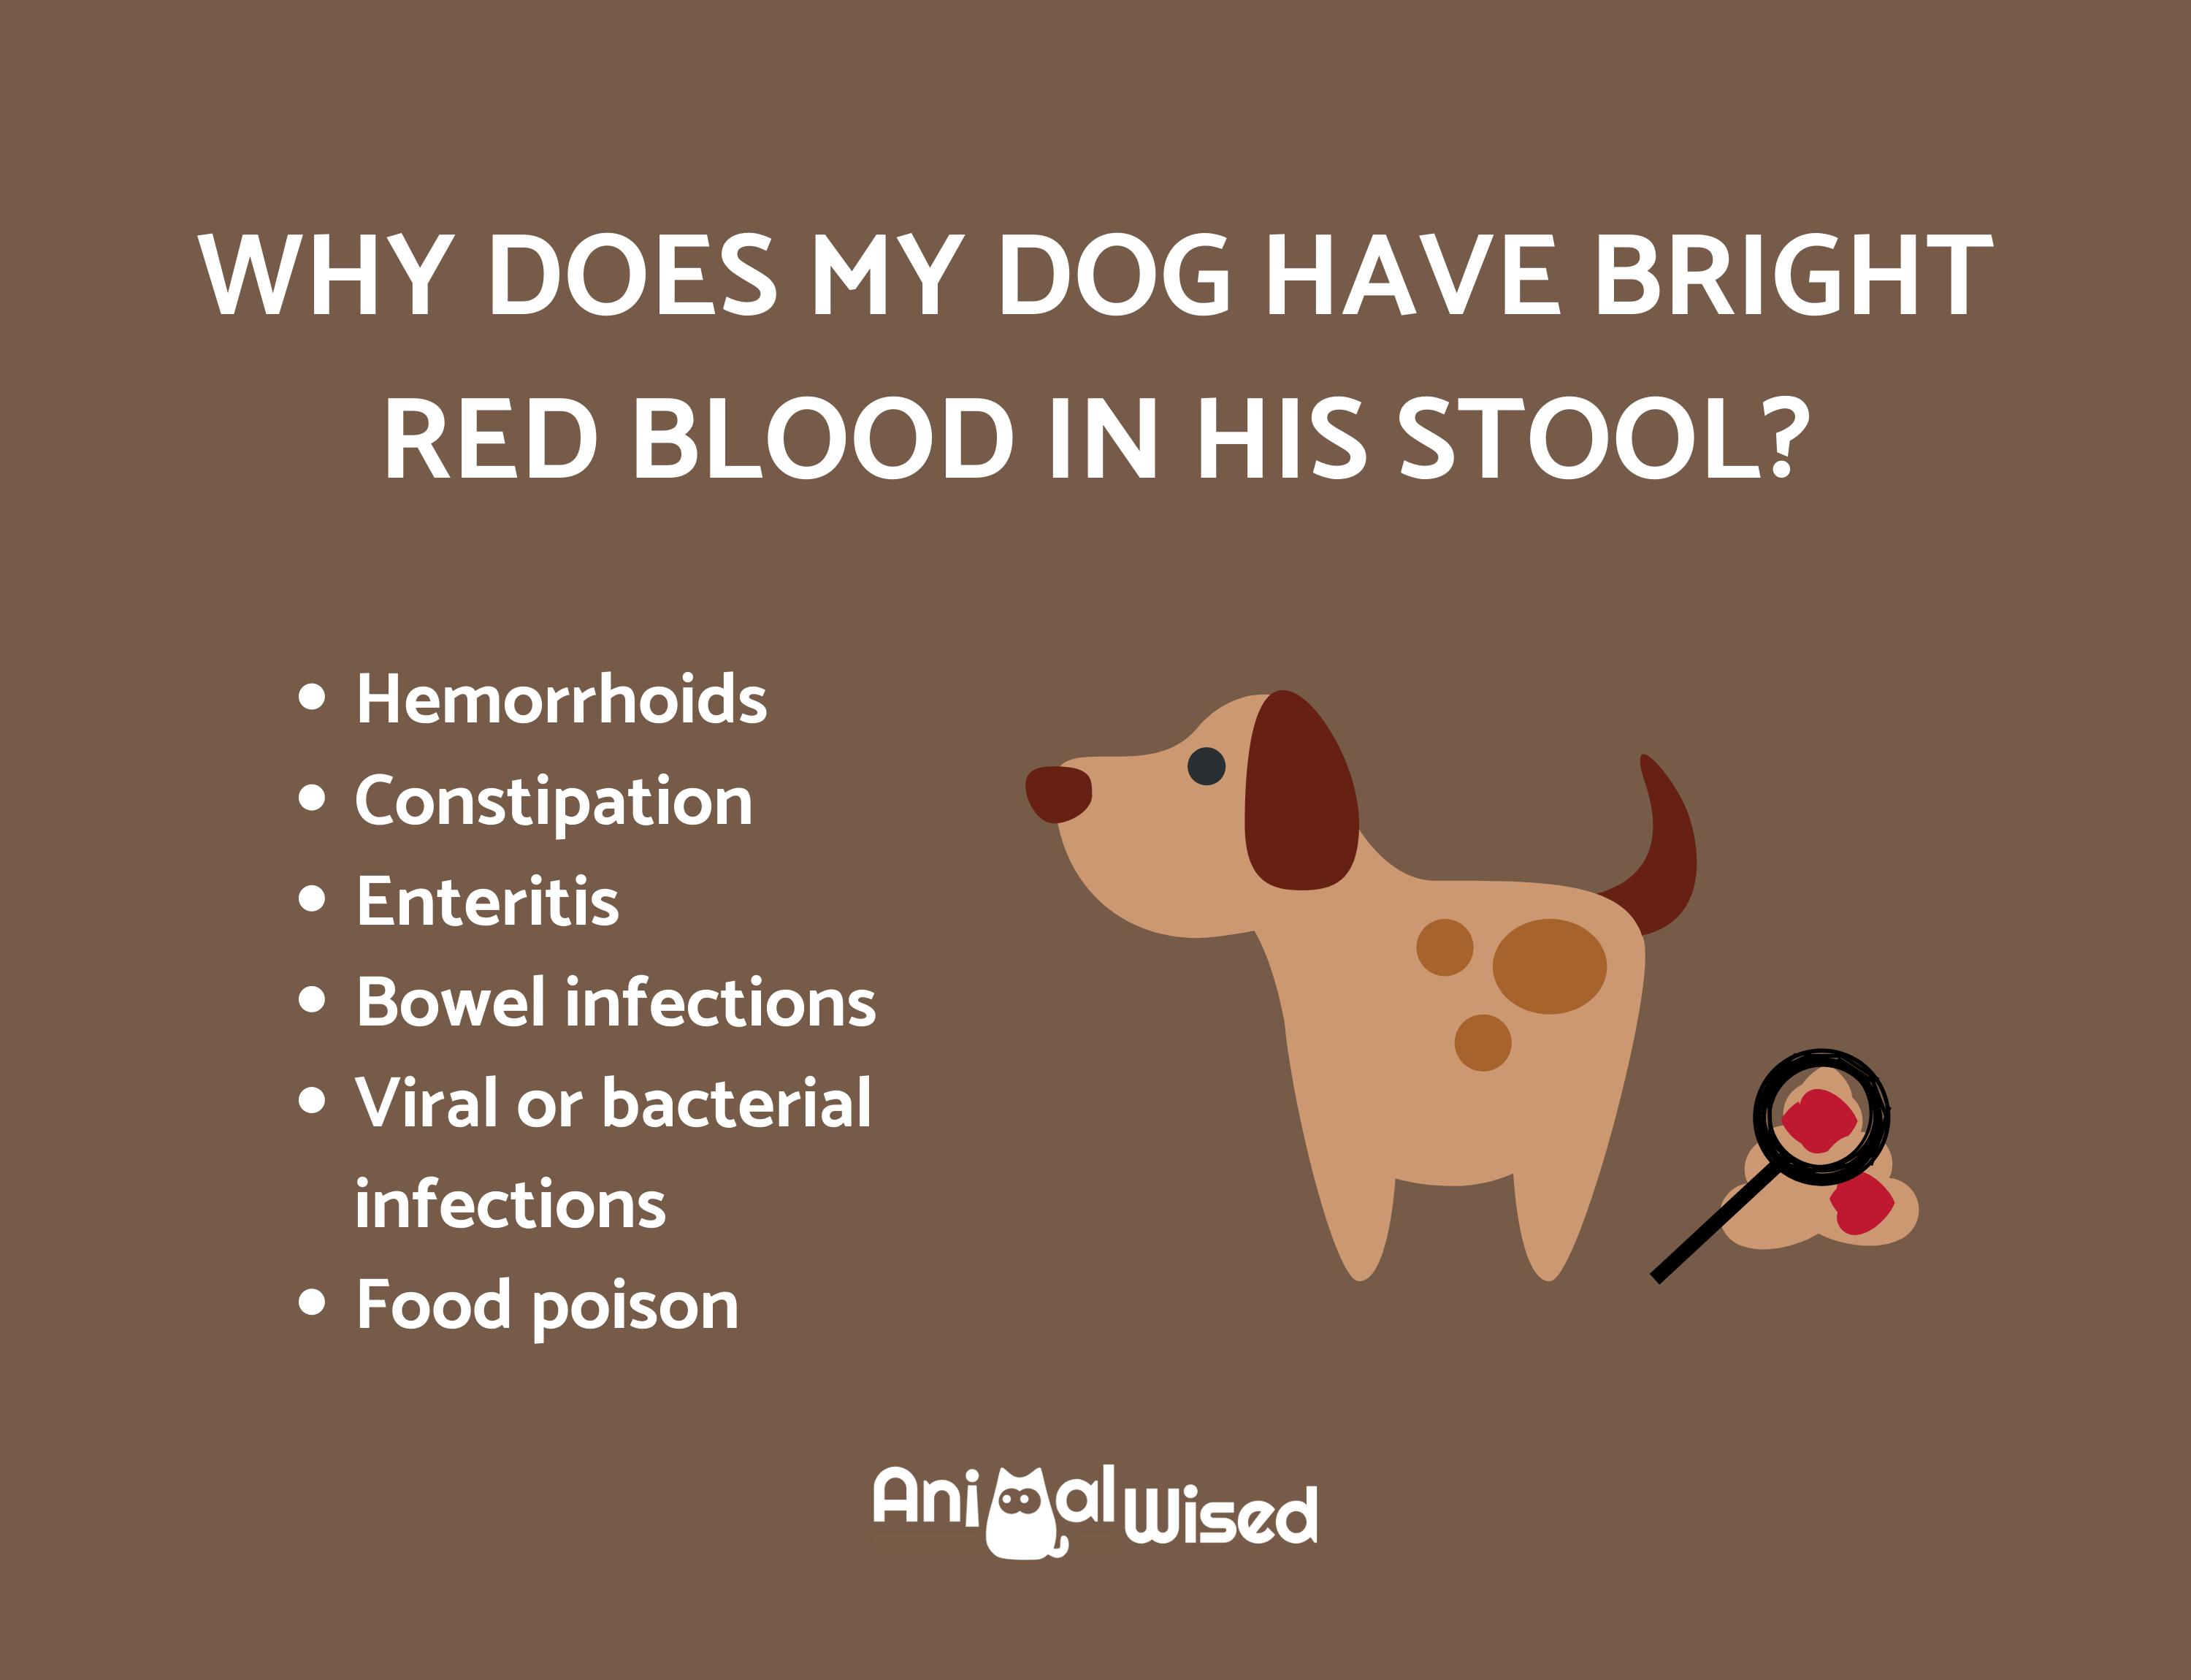
For many households, a pet is not just a companion but a significant member of the family unit. However, from a strictly financial perspective, a pet is also a living asset that requires ongoing maintenance and carries the risk of sudden, high-cost liabilities. One of the most alarming “red flag” events for a pet owner is the discovery of hematochezia (bright red blood) or melena (dark, tarry stool) in their dog’s feces. While the immediate concern is clinical, the underlying reality for the modern consumer is the fiscal pressure that such a symptom creates. Understanding what makes a dog poop blood is the first step in a complex journey through the economics of the pet care industry, diagnostic pricing, and the necessity of robust financial planning.

The Economic Landscape of the Pet Healthcare Industry
The pet care sector has undergone a massive transformation over the last decade, transitioning from a discretionary spending category to a staple of the “household essentials” budget. According to market data, the pet industry in the United States alone is a multi-billion dollar juggernaut, with veterinary care and product sales making up the largest share of that expenditure. When a pet presents with a symptom as severe as bloody stool, it triggers a sequence of economic events that illustrate why this sector is considered “recession-proof.”
The Premium on Specialty Veterinary Services
The cost of addressing a dog pooping blood is driven largely by the shift toward human-grade medical standards in the veterinary field. Modern veterinary clinics are no longer simple neighborhood offices; many have evolved into sophisticated medical centers equipped with state-of-the-art diagnostic tools. This evolution comes at a price. The capital expenditure required to maintain magnetic resonance imaging (MRI) machines, digital radiography, and in-house hematology labs is passed down to the consumer. When a dog exhibits signs of internal bleeding, the requirement for immediate, high-tech intervention moves the case from a standard consultation fee to an emergency or specialty tier, which can carry a baseline cost significantly higher than a routine wellness check.
Market Trends in Pet Wellness and Longevity
There is a direct correlation between the rising standards of pet care and the willingness of consumers to invest in expensive treatments. The “humanization of pets” trend has fundamentally altered the demand curve. Owners are increasingly likely to approve four-figure diagnostic bills to identify the cause of GI distress—whether it be parvovirus, hemorrhagic gastroenteritis (HGE), or ingestion of a foreign body—rather than opting for palliative care. This consumer behavior has attracted significant private equity interest, leading to the consolidation of independent clinics into large corporate entities. For the pet owner, this consolidation often means more standardized pricing but also fewer opportunities for negotiated rates, making financial literacy in pet care more vital than ever.
Breaking Down the Invoice: The High Cost of Diagnostics
When a dog poops blood, the clinical causes range from minor dietary indiscretions to life-threatening internal hemorrhaging. From a financial standpoint, the uncertainty of the diagnosis is the primary driver of cost. A veterinarian cannot provide an accurate prognosis or treatment plan without a suite of tests, each of which adds to the final invoice.
Laboratory Analysis and Imaging Fees
The diagnostic phase is often the most expensive part of the visit. A typical “workup” for a dog with bloody stool may include:
- Fecal Flotation and PCR Panels: Ranging from $50 to $250, these tests identify parasites or bacterial infections like Salmonella or Campylobacter.
- Comprehensive Blood Work (CBC and Chem Profile): Costing between $150 and $300, these panels are essential to check for anemia (loss of red blood cells) and organ function.
- Abdominal Radiographs or Ultrasound: This is where costs often escalate. A simple X-ray may cost $200, but a professional ultrasound performed by a board-certified radiologist can easily exceed $500.
These costs represent the “discovery phase” of the financial transaction. If the cause is found to be something like a “foreign body obstruction”—where a dog has swallowed a toy or fabric—the financial requirement shifts from diagnostic to surgical, often jumping from hundreds to thousands of dollars in a single afternoon.
The Premium on Urgent Care and Emergency Services
Timing is a critical variable in the cost of veterinary care. Because bloody stool is often seen as an emergency, owners frequently find themselves at 24-hour specialty hospitals rather than their regular daytime vet. Emergency clinics operate with higher overhead due to staffing requirements for overnight shifts and the maintenance of life-support equipment. A standard “exam fee” at an emergency hospital can be double or triple that of a general practitioner. For the pet owner, this necessitates a “liquidity strategy”—having access to immediate funds to cover a deposit, which is often 50% to 100% of the high-end estimate for treatment.
Financial Risk Management for Pet Owners
Given that a medical crisis involving a dog can result in an unexpected expense of $2,000 to $7,000, pet ownership requires a sophisticated approach to risk management. Relying on “hope” as a financial strategy is no longer viable in the face of modern medical costs.
The Role of Pet Insurance in Mitigating Loss
Pet insurance has moved from a niche product to a fundamental financial tool for responsible owners. By paying a monthly premium, owners can hedge against the risk of catastrophic expenses. In the case of a dog pooping blood, insurance can be the difference between a “medical decision” and a “financial decision.” Most high-quality plans cover up to 80% or 90% of the costs associated with diagnostics, hospitalization, and surgery, provided the condition is not pre-existing. From an investment perspective, pet insurance offers a high “peace of mind” ROI, ensuring that a sudden health crisis does not deplete a household’s emergency fund or retirement savings.
Emergency Funds vs. Credit Solutions
For those who opt out of insurance, the alternative is the “self-insurance” model. This involves maintaining a dedicated high-yield savings account specifically for pet emergencies. However, the limitation of this model is the “time-to-fund” problem; a puppy might experience a $3,000 emergency before the owner has had enough time to save that amount.
In these scenarios, many consumers turn to specialized credit products. Fintech tools have filled the gap in the veterinary market, offering deferred-interest payment plans. While these can be effective in a crisis, they also carry the risk of high-interest debt if not managed correctly. Insightful pet owners view these credit lines as a secondary safety net, rather than a primary solution.
The Business of Veterinary Practice Management
To understand why it costs so much to treat a dog pooping blood, one must look at the internal economics of a veterinary practice. Unlike human medicine, veterinary medicine is not heavily subsidized by government programs or large-scale employer-sponsored insurance. It is a true “fee-for-service” business model.
Overhead Costs and Pricing Structures
The overhead for a veterinary clinic is immense. Beyond the medical equipment, there are costs for pharmaceuticals, biohazard disposal, and professional liability insurance. Labor is the most significant expense; there is currently a global shortage of veterinarians and certified technicians, which has driven up wages. When a clinic sets its prices for treating a GI emergency, they are factoring in the cost of professional expertise that requires eight years of higher education and continuous training.
Value-Based Care and Customer Retention
From a business strategy perspective, clinics are moving toward “value-based care.” This involves educating the client on the long-term financial benefits of preventative care. For instance, maintaining a dog on high-quality nutrition and regular parasite prevention is significantly cheaper than treating the hemorrhagic consequences of a neglected parasitic infection. By positioning themselves as financial partners in the pet’s health, clinics can build long-term loyalty, which is more profitable than one-off emergency interventions.
The Bottom Line: Integrating Pet Health into Personal Finance
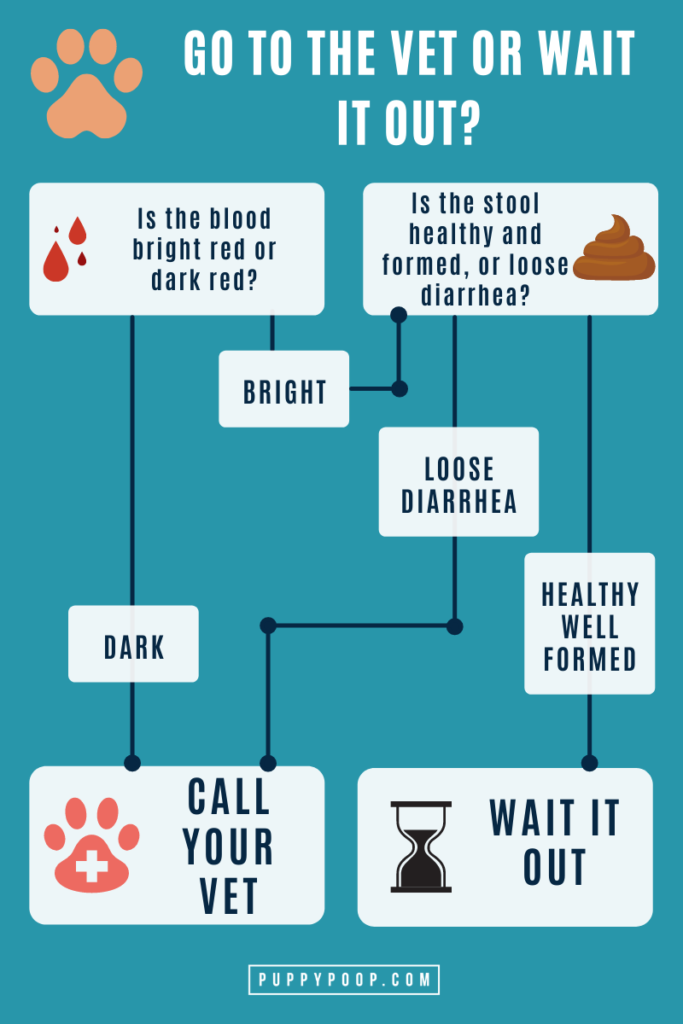
Seeing a dog poop blood is a stressful event that demands immediate action. While the biological causes are the domain of the veterinarian, the financial repercussions are the domain of the owner. In the modern economy, pet ownership is an investment that requires a diversified strategy: insurance to hedge against the “black swan” events, an emergency fund for the deductibles, and a deep understanding of the market forces that drive veterinary costs.
Ultimately, the ability to provide for a pet during a medical crisis is a reflection of one’s financial health and preparedness. By viewing veterinary emergencies through the lens of business and personal finance, owners can move past the initial shock of the symptom and make informed, rational decisions that protect both their pet’s life and their own financial future. The cost of care is high, but with the right financial tools and a proactive mindset, it is a manageable component of a well-rounded financial plan.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.