
As the United States approaches the midpoint of the decade, the projected US population for 2025 is estimated to reach approximately 342 to 345 million people. While this number represents a steady increase from previous years, the underlying demographic shifts tell a much more complex story. For investors, business owners, and individuals focused on personal finance, the “how” and “who” of the 2025 population are far more critical than the “how many.”
Demographics are the silent engine of the economy. They dictate labor supply, drive consumer demand, and influence the long-term solvency of national social programs. In 2025, the convergence of an aging Baby Boomer generation, declining birth rates, and shifting migration patterns will create a unique economic environment that requires a sophisticated financial approach.

The Macroeconomic Impact of the 2025 Demographic Profile
The US population growth rate has been slowing for decades, and 2025 marks a pivotal year where the “aging of America” becomes a dominant economic variable. When population growth slows, the traditional model of perpetual economic expansion faces new challenges. However, for those positioned in the right sectors, these shifts offer significant opportunities for wealth preservation and growth.
Deciphering the Numbers: Growth vs. Stagnation
While the total population continues to climb toward the 345 million mark, the rate of natural increase (births minus deaths) is at historic lows. Much of the growth realized in 2025 is expected to come from international migration and the “momentum” of previous generations. From a financial perspective, a slowing population growth rate often leads to a tighter labor market.
In 2025, businesses may find it increasingly difficult to fill entry-level and mid-management roles. For the individual worker, this translates to increased bargaining power and higher wage potential—a trend known as “wage-push” dynamics. For the investor, this means prioritizing companies that excel in automation and productivity, as they will be less vulnerable to rising labor costs.
The Labor Market and Wage Push Inflation
By 2025, the youngest members of the Baby Boomer generation will be entering their 60s, while the eldest will be well into their late 70s. This mass exodus from the workforce creates a vacuum. In the “Money” niche, this is viewed as a double-edged sword. On one hand, it necessitates higher interest rates to combat potential inflation driven by higher wages. On the other, it creates a robust environment for side hustles and the “fractional” workforce.
Professionals in 2025 are likely to leverage their expertise through consulting and independent contracting, filling the gaps left by retirees. This shift toward a “gig” economy for high-skilled workers will require new financial tools for tax planning, solo 401(k) management, and private insurance solutions.
Investing in the “Silver Tsunami” and Healthcare Infrastructure
The year 2025 is often cited by economists as a peak year for the “Silver Tsunami”—the period where the largest cohort of Boomers transitions into late-stage retirement. This demographic reality is one of the most predictable and investable trends in the modern financial landscape.
Healthcare REITs and Medical Innovation
Real Estate Investment Trusts (REITs) focusing on senior housing, skilled nursing facilities, and medical office buildings are positioned for a significant demand surge in 2025. As the 345 million residents of the US age, the consumption of healthcare services per capita is expected to rise exponentially.
Investors should look beyond traditional pharmaceuticals and examine the “infrastructure” of health. This includes companies that manage outpatient clinics and home-health technology. With a larger portion of the 2025 population requiring long-term care, the financial burden will shift toward private savings and insurance, making Long-Term Care Insurance (LTCI) a critical component of any personal finance strategy.
The Longevity Economy: Services for the Aging
The 2025 population isn’t just getting older; it is also staying wealthier for longer. The “longevity economy” refers to the trillions of dollars spent by those over 50. In 2025, this demographic will control more than 70% of the US disposable income.
From a business finance perspective, companies that pivot their marketing and product design to cater to the “active senior” will see outsized returns. This includes travel, leisure, and financial services tailored to “decumulation”—the process of spending down retirement assets efficiently while minimizing tax exposure.
Real Estate Market Corrections and Geographic Shifts

The US population in 2025 is not distributed the same way it was in 2015. Internal migration has fundamentally altered the real estate landscape, with significant implications for property investors and those looking to relocate for tax advantages.
The Migration to the Sun Belt and Secondary Cities
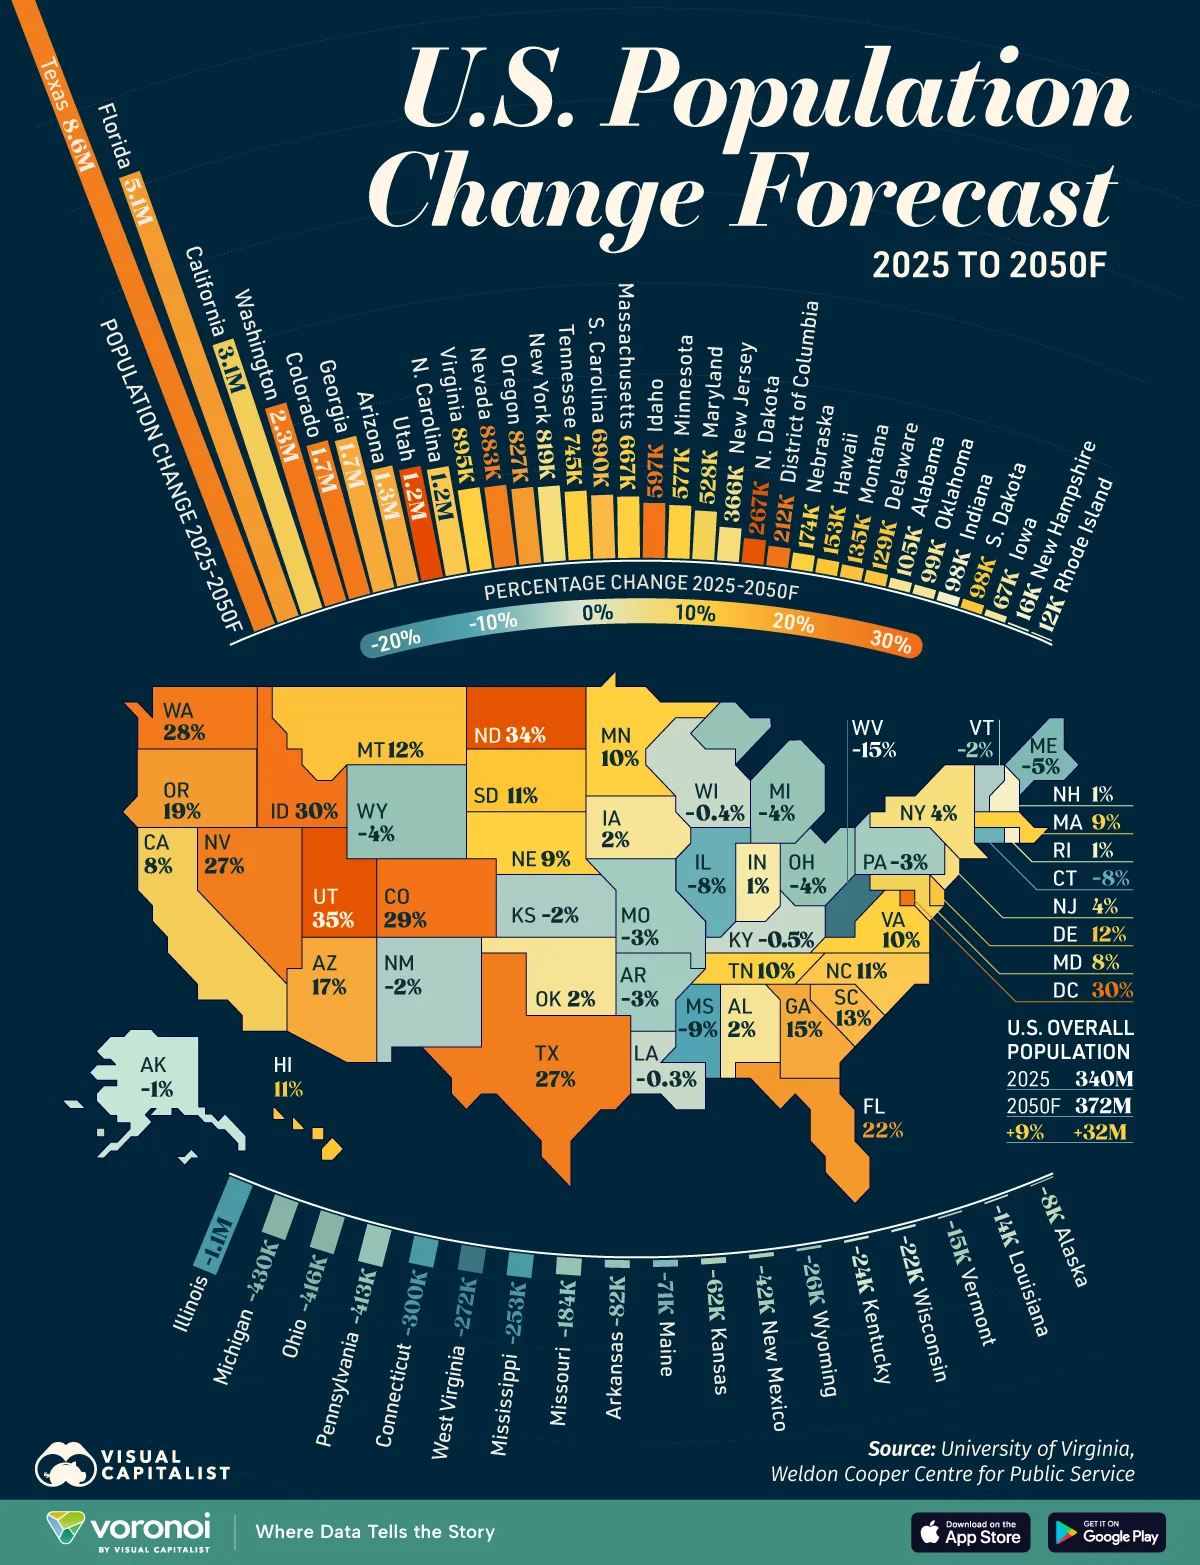
Data suggests that by 2025, the shift from high-tax, high-density northern states to the Sun Belt (Florida, Texas, Arizona, and the Carolinas) will have reached a saturation point, creating new “boomtowns.” For personal finance enthusiasts, this migration is driven by the search for lower costs of living and better tax climates.
Investing in residential real estate in these growth hubs remains a viable strategy, but the “easy money” of the early 2020s has vanished. Success in 2025 requires a focus on secondary cities—smaller metropolitan areas that offer the amenities of a large city with the affordability that the 2025 workforce craves.
Changing Housing Needs: Multi-Generational Living
As the population hits 345 million, housing inventory remains a bottleneck. A notable trend in 2025 is the rise of multi-generational living. Driven by both the high cost of entry for first-time buyers (Gen Z) and the care needs of aging parents, homes with “accessory dwelling units” (ADUs) or dual-master suites are seeing a premium in the market.
From a wealth-building perspective, renovating existing properties to accommodate multi-generational living can significantly increase property value and provide a hedge against the rising costs of professional senior care.
Retirement Sustainability and the Social Security Question
Perhaps the most pressing financial concern regarding the 2025 US population is the sustainability of social safety nets. With more people drawing from the system and a smaller ratio of workers contributing to it, the “dependency ratio” is reaching a critical threshold.
The Dependency Ratio and Tax Policy
In 2025, the ratio of retirees to active workers will put unprecedented pressure on the federal budget. While Social Security is not expected to “go bust” by 2025, the conversation around increased payroll taxes or pushed-back retirement ages will be a central theme in financial planning.
Prudent financial strategy for 2025 involves “tax-diversification.” Relying solely on a traditional 401(k) may be risky if tax rates rise to support the aging population. Utilizing Roth IRAs, Health Savings Accounts (HSAs), and municipal bonds can provide tax-free or tax-advantaged income streams that are shielded from future policy changes.
Private Wealth Management in a High-Demand Era
As the 2025 population navigates these complexities, the demand for sophisticated financial advice will peak. The “Great Wealth Transfer”—estimated at over $68 trillion—will be in full swing as Boomers pass assets to Gen X and Millennials. This transfer requires meticulous estate planning to avoid the “death tax” and ensure that assets are not liquidated to cover healthcare costs. Personal finance in 2025 is less about “beating the market” and more about “protecting the principal.”
Adapting Your Personal Finance Strategy for 2025
Knowing that the US population in 2025 is older, more concentrated in specific regions, and facing a tighter labor market allows you to adjust your financial sails accordingly.
Diversification Beyond Traditional Equities
In a slower-growth demographic environment, capital appreciation in the S&P 500 may not be as robust as it was during the post-WWII population boom. In 2025, income-producing assets—such as dividend-paying stocks, private credit, and specialized real estate—become more attractive. The focus shifts toward “yield” as a way to combat the persistent inflation that often accompanies a shrinking labor pool.
Leveraging the Gig Economy and Fractional Income
With a US population of 345 million, the competition for traditional high-paying corporate roles remains fierce, yet the shortage of skilled labor persists. This creates a “Money” opportunity: the rise of the specialized consultant. By 2025, many individuals will diversify their income streams by taking on fractional roles at multiple companies.
This “portfolio career” approach is a powerful hedge against economic volatility. By not relying on a single employer, and instead serving a slice of the 345 million-strong market, individuals can create a more resilient financial foundation.
Ultimately, the story of the US population in 2025 is one of transition. By understanding the economic ripples caused by these 345 million individuals—their age, their location, and their spending habits—you can position your personal and business finances to thrive in the second half of the decade.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.