
In an era where personal finance permeates every aspect of our lives, from budgeting for groceries to investing in our future, the intersection of health and wealth has become increasingly apparent. While the phrase “what is the normal level of triglycerides” might initially evoke thoughts purely of medical diagnoses and bodily functions, a closer examination reveals profound financial implications. Understanding and managing your triglyceride levels isn’t merely a health imperative; it’s a critical component of prudent personal financial planning, impacting everything from healthcare costs and insurance premiums to lost income and long-term financial security.
This article delves into the often-overlooked financial dimensions of maintaining healthy triglyceride levels, treating it as an investment in your most valuable asset: your well-being. We will explore how understanding these lipid levels can protect your wallet, enhance your financial resilience, and contribute to a more prosperous future.
Understanding Triglycerides and Their Financial Implications
Triglycerides are a type of fat (lipid) found in your blood. When you eat, your body converts any calories it doesn’t need to use right away into triglycerides. These are then stored in your fat cells. Later, hormones release triglycerides for energy between meals. While a certain level of triglycerides is essential for energy, consistently high levels can signify a substantial financial risk.
The Basics of Triglycerides: More Than Just Fat
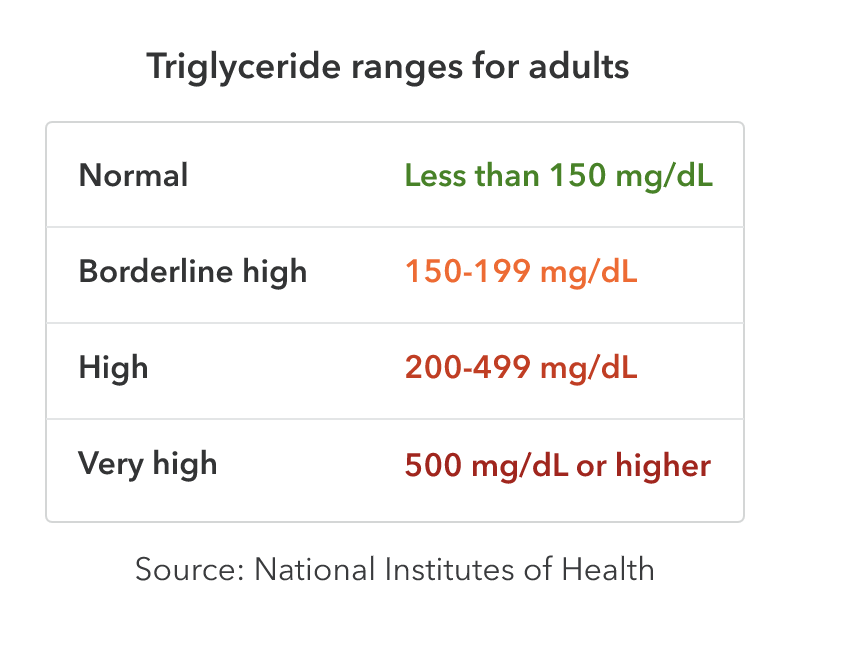
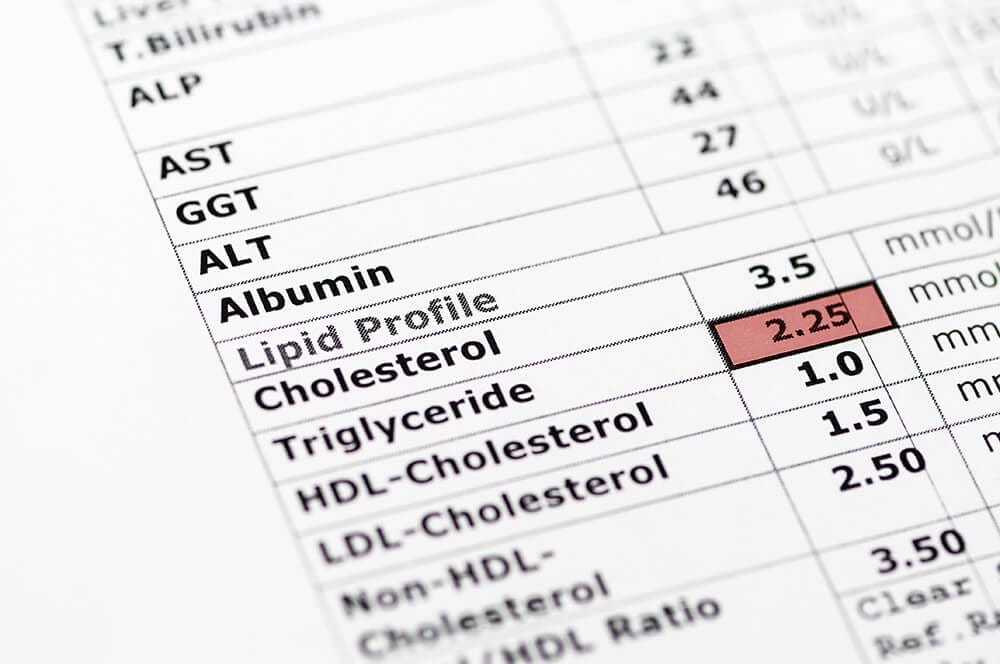
To grasp the financial implications, one must first understand the basics. Triglyceride levels are typically measured during a lipid panel, a routine blood test often recommended as part of an annual physical. The commonly accepted categories for triglyceride levels are:
-
Normal: Less than 150 milligrams per deciliter (mg/dL) or less than 1.7 millimoles per liter (mmol/L). This is the ideal range for optimal health and, by extension, minimal financial risk associated with lipid disorders.
-
Borderline high: 150 to 199 mg/dL (1.7 to 2.2 mmol/L). Levels in this range suggest a need for lifestyle adjustments and careful monitoring, as they start to flag a potential increase in future health expenses.
-
High: 200 to 499 mg/dL (2.3 to 5.6 mmol/L). At this level, the risk of heart disease and other complications rises significantly, often necessitating medical intervention and incurring direct healthcare costs.
-
Very high: 500 mg/dL (5.6 mmol/L) or above. This level indicates a substantial risk of acute pancreatitis and severe cardiovascular events, leading to potentially catastrophic financial burdens.
The body’s intricate financial ecosystem is surprisingly similar to its biological one; just as a balanced budget fosters financial stability, balanced lipid levels underpin robust physical health. Deviations from the “normal” range represent not just a medical challenge, but a potential leak in your financial reserves.
The Silent Threat: How High Triglycerides Impact Future Costs
High triglyceride levels often present without immediate symptoms, earning them the moniker of a “silent threat.” This insidious nature makes them particularly dangerous, as the damage accumulates over time, leading to conditions that can drain financial resources significantly. The primary concern with elevated triglycerides is their strong association with atherosclerosis, the hardening and narrowing of the arteries. This condition is a precursor to a range of costly cardiovascular diseases, including heart attack, stroke, and peripheral artery disease.
Consider the compounding effect. Just as neglected credit card debt accrues interest and ballooning balances, unmanaged high triglycerides lead to escalating health issues and corresponding medical expenses. These can range from diagnostic tests and specialist consultations to ongoing medication and, in severe cases, life-altering surgeries. The initial “cost” of ignorance or inaction is deceptively low, but the long-term financial interest on this “health debt” can be astronomical.
Medical Costs: The Price of Unmanaged Lipid Levels
The financial burden of unmanaged high triglycerides is multifaceted and substantial. Here’s a glimpse into the direct and indirect medical costs:
-
Medication: For many, lifestyle changes alone are insufficient, and doctors prescribe lipid-lowering drugs such as statins, fibrates, or omega-3 fatty acid supplements. These can be a recurring monthly expense, ranging from tens to hundreds of dollars, depending on the drug and insurance coverage. Over a lifetime, these costs can accumulate to thousands, if not tens of thousands, of dollars.
-
Doctor Visits and Specialists: Regular monitoring requires frequent visits to general practitioners and potentially cardiologists or endocrinologists. Co-pays, deductibles, and out-of-pocket expenses for these visits add up.
-
Diagnostic Tests: Beyond routine lipid panels, high triglycerides might necessitate further tests like advanced cholesterol panels, imaging tests (e.g., echocardiograms, stress tests) to assess cardiovascular health, or even genetic testing. These can be expensive, particularly if not fully covered by insurance.
-
Hospitalizations and Procedures: The most significant financial shock comes from acute events. A heart attack, stroke, or severe pancreatitis, directly linked to very high triglycerides, often requires emergency hospitalization, intensive care, and potentially invasive procedures like angioplasty, bypass surgery, or pancreatic surgery. The costs for these can easily reach tens or hundreds of thousands of dollars, even with insurance, due to deductibles, co-insurance, and non-covered services.
-
Rehabilitation: Post-event, cardiac rehabilitation, physical therapy, and ongoing follow-up care add further layers of expense, which are crucial for recovery but demanding on the wallet.
These direct medical costs highlight why maintaining normal triglyceride levels is not just a health goal but a crucial financial objective, effectively a preventative financial strategy.
Investing in Health: Proactive Financial Management of Triglycerides
Just as savvy investors diversify portfolios and regularly review their financial health, individuals should adopt a proactive approach to their physical health, particularly concerning triglyceride management. Viewing health as an investment asset means understanding that upfront “deposits” in healthy habits yield significant “returns” in long-term financial stability and reduced healthcare expenditures.
Diet and Nutrition: Budgeting for a Heart-Healthy Lifestyle
One of the most powerful and cost-effective strategies for managing triglycerides is through dietary modification. This isn’t about expensive superfoods but smart, budget-conscious choices.
-
Minimize Sugars and Refined Carbohydrates: Sugary drinks, candies, baked goods, and white bread are significant culprits in raising triglyceride levels. Replacing these with water, whole fruits, and whole grains is often cheaper and certainly healthier. For instance, making coffee at home instead of buying sugary lattes saves money and reduces sugar intake.
-
Choose Healthy Fats: Opt for monounsaturated and polyunsaturated fats found in olive oil, avocados, nuts, and fatty fish (like salmon) over saturated and trans fats. While some healthy fats (like avocados) can seem pricier per item, their nutritional density and satiety value can lead to overall savings by reducing cravings and less healthy snack purchases. Cooking at home with fresh ingredients is invariably cheaper and healthier than frequenting fast-food establishments, which often feature meals high in unhealthy fats and sugars.
-
Increase Fiber Intake: Foods rich in soluble fiber (oats, beans, apples, pears) help lower triglyceride levels. These are generally affordable pantry staples that can be incorporated into numerous budget-friendly meals.
Budgeting for a heart-healthy diet is a direct financial investment. It reduces the likelihood of future expensive medical interventions, and in the short term, it can be more economical than relying on processed foods and takeout.
Exercise and Activity: Free and Frugal Ways to Boost Lipid Health
Regular physical activity is a cornerstone of good health and an excellent, often free, way to lower triglycerides. You don’t need an expensive gym membership or high-tech equipment to reap the benefits.
-
Walking and Jogging: These are among the most accessible forms of exercise, requiring only comfortable shoes. Incorporating daily walks can significantly improve cardiovascular health and lipid profiles without any direct cost.
-
Bodyweight Exercises: Push-ups, squats, lunges, and planks can be done anywhere, anytime, building strength and improving metabolism. Online resources offer free workout routines.
-
Cycling: If you own a bicycle, it offers a fantastic way to combine exercise with transportation, saving on fuel costs while burning calories.
-
Active Hobbies: Gardening, hiking, dancing, or even active chores around the house contribute to physical activity without necessitating dedicated gym time.
The “return on investment” for exercise is substantial: not only does it help lower triglycerides, but it also improves mood, energy levels, and overall physical resilience, translating to fewer sick days and higher productivity—tangible financial benefits.
Regular Check-ups: A Small Investment for Major Savings
Routine medical check-ups, including lipid panels, are perhaps the most critical “small investment” in your long-term financial health. Identifying elevated triglyceride levels early, when they are “borderline high,” allows for timely lifestyle modifications that can prevent the need for expensive medications or treatments down the line.
-
Preventative Care Coverage: Most health insurance plans cover annual physicals and basic blood tests, including lipid panels, at little to no out-of-pocket cost. Utilizing these benefits is a no-brainer financial strategy.
-
Early Detection: Catching high triglycerides before they escalate to “very high” levels or cause significant arterial damage can save tens of thousands of dollars in future medical bills. It’s akin to addressing a small leak in your roof before it causes extensive water damage to your entire house.
-
Personalized Advice: A doctor can provide tailored advice on diet and exercise, which is more effective than generic health recommendations. This personalized guidance helps you optimize your health investments for maximum return.
The cost of skipping a preventative check-up can be exponentially higher than the co-pay or minimal deductible associated with an annual visit. It’s an essential element of a sound personal finance plan that accounts for future health expenditures.
The Economic Burden of Cardiovascular Disease Linked to Triglycerides
While focusing on individual financial decisions, it’s crucial to acknowledge the broader economic burden of cardiovascular diseases (CVD) to which high triglycerides contribute. This burden affects not only personal finances but also national healthcare systems, employer productivity, and overall economic stability.
Lost Productivity and Income: The Ripple Effect of Poor Health
When high triglycerides lead to CVD events like heart attack or stroke, the financial impact extends far beyond medical bills.
-
Lost Wages: Recovery from such events often involves prolonged periods away from work, leading to significant income loss. For hourly workers, this can be catastrophic; for salaried employees, it might mean exhausting sick leave or disability benefits.
-
Reduced Earning Potential: Long-term disability, cognitive impairment from stroke, or chronic fatigue can permanently reduce an individual’s earning capacity, impacting retirement savings and overall financial security.
-
Caregiver Burden: Family members often have to take time off work to care for an ailing loved one, leading to their own lost income and increased household stress. This “sandwich generation” phenomenon creates a dual financial strain.
-
Employer Costs: Businesses incur costs from absenteeism, reduced productivity, and the need to train temporary replacements. This demonstrates how individual health choices have wider economic repercussions.
Insurance Premiums and Healthcare Access: Navigating the System
Chronic health conditions, including those associated with high triglycerides, can influence insurance.
-
Life Insurance: While health status doesn’t directly impact current health insurance premiums in many regions due to regulations (like the Affordable Care Act in the US), it significantly affects life insurance policies. Individuals with a history of high triglycerides and related CVD may face higher premiums or even be denied coverage, impacting their ability to provide financial protection for their families.
-
Disability Insurance: Similarly, disability insurance might be more expensive or have exclusions for pre-existing conditions related to lipid disorders.
-
Access to Care: Managing complex conditions requires access to specialized care, which can be challenging and costly, even with insurance, due to network limitations and high deductibles. Navigating this system efficiently becomes another financial skill.
Long-Term Care and Medication Costs: Planning for the Future
The long tail of high triglycerides leading to chronic CVD often involves lifelong medication and potentially long-term care needs.
-
Lifelong Medication: Many individuals with a history of heart disease will be on multiple medications indefinitely (e.g., statins, blood thinners, blood pressure medications). These recurring costs become a permanent fixture in the monthly budget.
-
Long-Term Care: Severe CVD can result in chronic disability requiring assisted living or skilled nursing care. The costs of long-term care facilities are exorbitant, often depleting life savings and requiring significant estate planning. Without proper planning, this burden falls heavily on family members.
These are not hypothetical scenarios but tangible financial realities for millions. Recognizing these costs underscores the immense value of prevention and proactive health management.
Financial Tools and Strategies for Lipid Health Management
Integrating lipid health into financial planning requires utilizing existing financial tools and adopting specific strategies that prioritize well-being as a core financial asset.
Budgeting for Health: Allocating Resources for Well-being
A robust personal budget should explicitly include categories for health and wellness. This isn’t just about reactive spending on sick care but proactive investment in preventative measures.
-
“Healthy Living” Category: Allocate funds for nutritious groceries, a gym membership (if desired), fitness classes, or even health-related apps. Treat these expenses as non-negotiable investments, much like retirement contributions.
-
“Medical Expenses” Buffer: Create a dedicated savings buffer for unexpected medical costs, co-pays, and deductibles not covered by insurance. This mitigates financial shock when health issues arise.
-
Review and Adjust: Regularly review your health spending, just as you would any other budget category. Are you getting good value for your money? Are there more cost-effective ways to stay healthy?
Utilizing Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs)
These tax-advantaged accounts are powerful financial tools for managing health-related expenses, including those associated with monitoring and treating triglycerides.
-
HSAs: If you have a high-deductible health plan, an HSA allows you to save and invest money tax-free for qualified medical expenses. Contributions are tax-deductible, earnings grow tax-free, and withdrawals for medical expenses are tax-free. This is an excellent way to save for future medical costs, medication, and even some healthy lifestyle expenses (like gym memberships prescribed by a doctor).
-
FSAs: Offered by employers, FSAs allow you to set aside pre-tax money for medical expenses. While they typically have a “use-it-or-lose-it” rule, they are ideal for covering predictable annual medical costs like co-pays, prescriptions, and preventative care not fully covered by insurance.
Leveraging these accounts effectively reduces your taxable income while providing a dedicated fund for health needs, making it easier to afford preventative care and necessary treatments for triglyceride management.

The ROI of Prevention: Calculating Your Health Investment
Finally, consider the Return on Investment (ROI) of prevention. While difficult to quantify precisely, the financial benefits of maintaining normal triglyceride levels are undeniable.
-
Cost Avoidance: Every dollar spent on healthy food, exercise, and preventative check-ups potentially avoids multiple dollars in future medical bills, lost income, and long-term care expenses.
-
Enhanced Productivity: Good health leads to more energy, better focus, and fewer sick days, directly contributing to higher earning potential and career longevity.
-
Quality of Life: Beyond mere dollars, the ability to enjoy life, travel, and participate in activities without the burden of chronic illness has an immeasurable financial value in terms of avoided opportunity costs.
-
Peace of Mind: Knowing you’ve taken proactive steps to protect your health and, by extension, your financial future, brings invaluable peace of mind.
In conclusion, understanding “what is the normal level of triglycerides” transcends a purely medical inquiry to become a fundamental component of astute personal finance. By proactively managing these lipid levels through diet, exercise, and regular medical check-ups, individuals are not just safeguarding their health but also making a sound investment in their long-term financial stability, ensuring a richer, healthier, and more secure future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.