
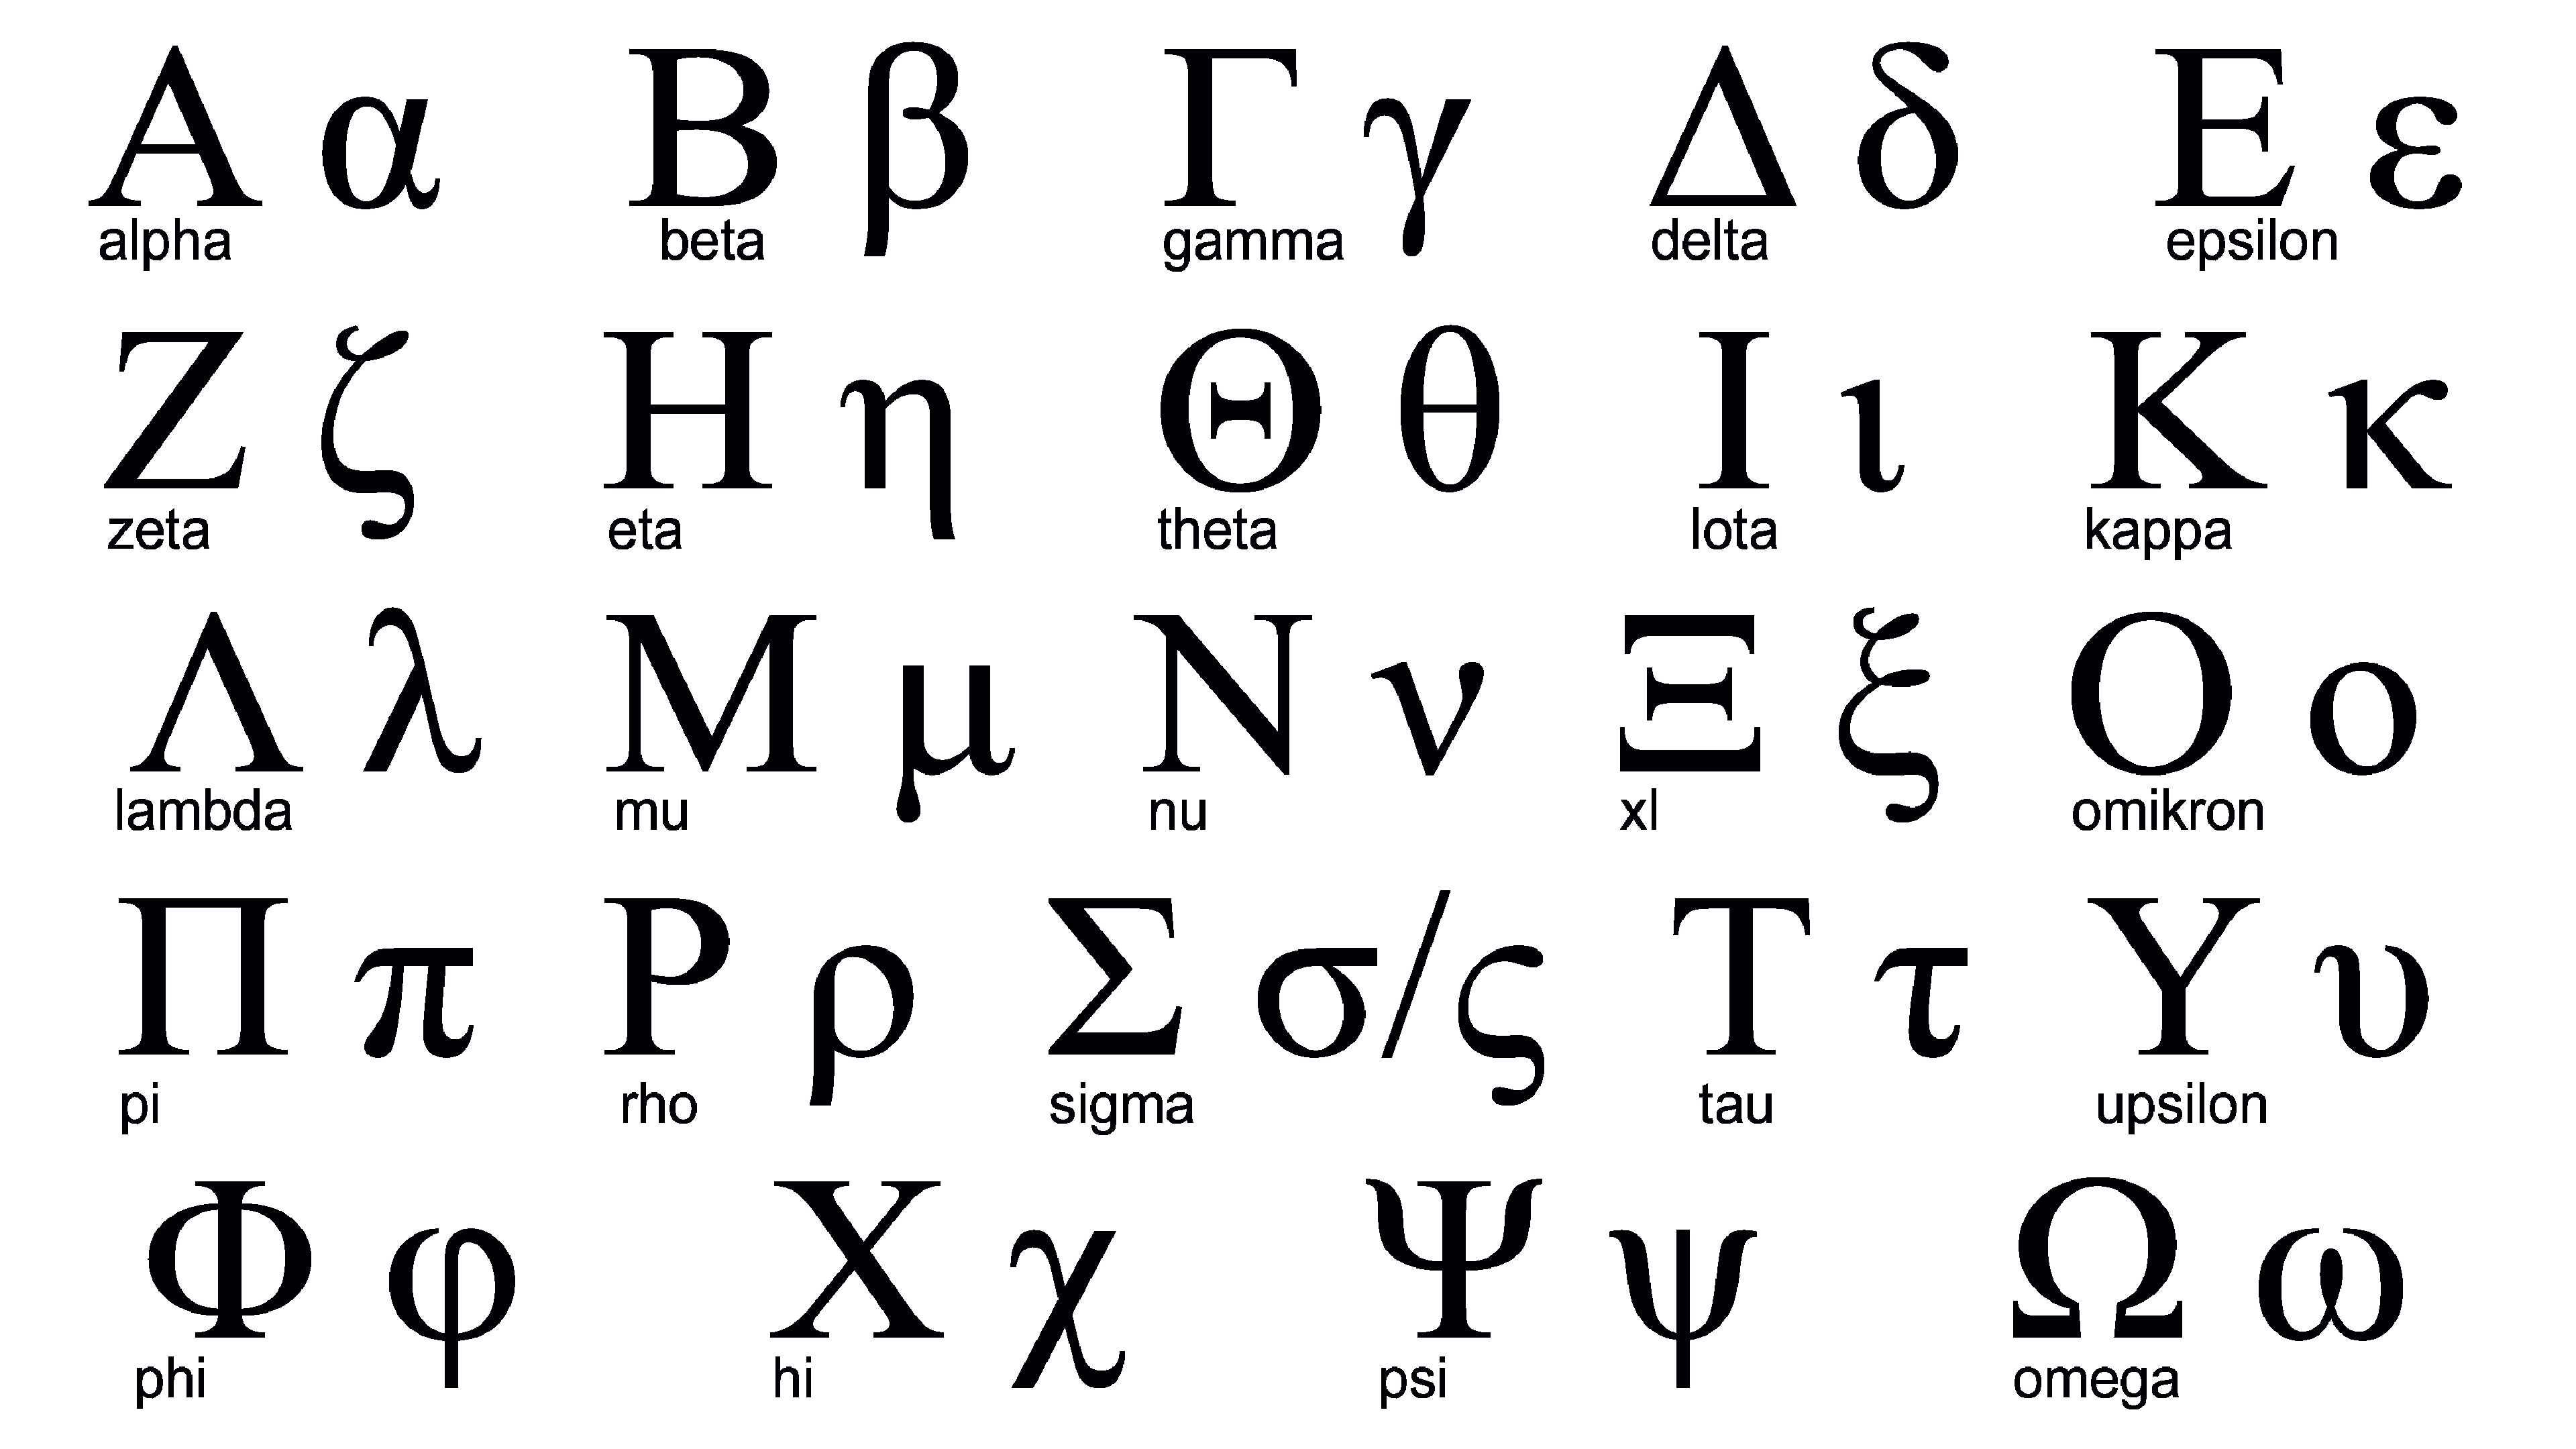
While the literal answer to the question of the first letter in the Greek alphabet is “Alpha,” for the modern investor, the term carries a weight far beyond linguistics. In the world of finance, Alpha represents the “holy grail”—the ability to outperform the market, the edge that distinguishes a master strategist from a casual observer, and the metric by which every hedge fund manager is ultimately judged. To understand Alpha is to understand the core engine of active wealth creation and the sophisticated mechanisms that drive the global economy.

In the context of personal finance and institutional investing, Alpha is not just a character; it is a mathematical expression of skill. It represents the excess return of an investment relative to the return of a benchmark index. As markets become increasingly efficient and technology-driven, the pursuit of this “first letter” has evolved into a complex science that blends psychology, data analysis, and strategic risk-taking.
Defining Alpha: The Mathematical Edge in Finance
In the simplest terms, Alpha measures the performance of an investment compared to a suitable market benchmark, such as the S&P 500. If the market returns 10% and your portfolio returns 12%, you have generated 2% of Alpha. However, in professional finance, the calculation is significantly more nuanced, often involving the Capital Asset Pricing Model (CAPM).
The Relationship Between Alpha and Beta
To truly appreciate Alpha, one must understand its counterpart: Beta. Beta represents the systematic risk or the volatility of an investment in relation to the overall market. If an investment has a Beta of 1.0, it moves in lockstep with the market. Beta is “passive” return—what you get simply for showing up and participating in the market’s natural growth.
Alpha, conversely, is the “active” return. It is the portion of the return that cannot be explained by market movements alone. It is the value added (or subtracted) by a portfolio manager’s decisions. In a world where low-cost index funds provide easy access to Beta, the financial industry’s primary challenge is justifying higher fees by consistently delivering Alpha.
Jensen’s Alpha and Risk Adjustment
Professional investors use “Jensen’s Alpha” to determine if a manager is truly providing value or simply taking on more risk. A manager might deliver high returns by investing in highly volatile assets; Jensen’s Alpha adjusts for this risk. If the adjusted Alpha is positive, it suggests the manager has a “secret sauce”—a methodology or insight that allows them to beat the expected return for that specific level of risk. This is the difference between being lucky and being skilled.
The Mechanics of Generating Alpha: Active Management Strategies
The pursuit of Alpha is what drives the active management industry. While passive investing focuses on tracking the market (earning Beta), active investing is a relentless search for inefficiencies. In a perfectly efficient market, Alpha would be impossible to find because all information would already be priced into every asset. Fortunately for the strategic investor, markets are frequently driven by emotion, lag time, and structural anomalies.
Fundamental Analysis and Value Investing
The traditional path to Alpha involves deep-dive fundamental analysis. This involves scrutinizing balance sheets, income statements, and cash flow projections to find companies that the market has undervalued. Value investors like Warren Buffett have built empires on this brand of Alpha—buying “dollars for eighty cents.” By identifying a gap between a company’s intrinsic value and its current stock price, an investor can capture Alpha as the market eventually corrects its oversight.
Quantitative Analysis and the Data Revolution
In the modern era, the search for the “first letter” has moved from the boardroom to the server room. Quantitative Alpha involves using mathematical models and algorithms to identify patterns that are invisible to the human eye. These might include statistical arbitrage, where minute price discrepancies between related securities are exploited, or high-frequency trading that capitalizes on micro-second delays in market data. In this niche, Alpha is a function of computational power and algorithmic sophistication.
Information Asymmetry and Alternative Data
Historically, Alpha was found by having information that others didn’t. Today, with the internet democratizing financial data, “information asymmetry” has become harder to find. Investors are now turning to “alternative data” to regain their edge. This includes tracking satellite imagery of retail parking lots to predict quarterly earnings, monitoring social media sentiment through natural language processing, or analyzing credit card transaction data in real-time. By processing these non-traditional signals, firms attempt to generate Alpha before the rest of the market catches on.
Alpha vs. Beta: The Balancing Act of Risk and Reward
Every investor must decide how much they are willing to pay for Alpha versus how much they are willing to rely on Beta. This decision is at the heart of modern portfolio construction and personal financial planning.
The Rise of Passive Investing
Over the last two decades, there has been a massive migration of capital from active funds to passive ETFs and index funds. The logic is simple: most active managers fail to consistently deliver Alpha after fees are deducted. For many individual investors, capturing the “Beta” of the S&P 500 at a cost of 0.03% per year is a mathematically superior strategy to paying a 1% management fee for a fund that might underperform. This shift has forced the industry to redefine what “true Alpha” looks like.
The Cost of Chasing Alpha
Alpha is a zero-sum game. For every investor who outperforms the market, there is another who must underperform. This makes the pursuit of Alpha expensive. It requires high-caliber talent, expensive data feeds, and sophisticated infrastructure. When an investor chooses an active strategy, they are essentially betting that the manager’s Alpha will be greater than the cost of the search. In the current landscape, the “fee hurdle” is one of the greatest obstacles to net-Alpha for the retail investor.
Smart Beta: The Middle Ground
A relatively new category called “Smart Beta” attempts to bridge the gap. These are rules-based investment strategies that don’t just track a standard index by market capitalization but instead weight stocks based on factors like volatility, dividends, or momentum. While technically a form of Beta (as it is passive and rules-based), it seeks to capture “factor Alpha” by exploiting known market anomalies without the high cost of a traditional human manager.
The Evolution of Alpha in the Digital Age
As we look toward the future of finance, the concept of Alpha is being transformed by artificial intelligence and the globalization of capital. The “first letter” is becoming more elusive, but also more valuable.
AI and Machine Learning in Alpha Discovery
Artificial Intelligence is the new frontier for Alpha. Machine learning models can process millions of data points simultaneously, identifying non-linear correlations that traditional models miss. AI doesn’t just look at what happened; it attempts to predict what will happen by recognizing complex historical echoes. However, as more participants use AI, the “Alpha” generated by these tools may begin to shrink, leading to an “AI arms race” in the financial sector.
Alpha in Alternative Assets
With traditional stock and bond markets becoming hyper-efficient, many wealth managers are looking to alternative assets to find their edge. Private equity, venture capital, real estate, and even cryptocurrency offer “Alpha” opportunities that are less correlated with the broader stock market. These markets often lack the transparency of public exchanges, creating more opportunities for skilled players to find mispriced assets. However, these “pockets of Alpha” often come with higher liquidity risks and longer lock-up periods.
The Psychology of Alpha
Finally, one must consider the behavioral aspect. Often, the greatest source of Alpha is not a computer or a spreadsheet, but emotional discipline. Behavioral Alpha is the return generated by staying the course when others panic, or by remaining cautious when the market is euphoric. In an era of instant notifications and 24-hour news cycles, the ability to maintain a long-term perspective is perhaps the rarest and most sustainable form of Alpha available to the individual investor.

The Perpetual Pursuit of the Investment ‘Alpha’
While “Alpha” may simply be the first letter of the Greek alphabet, in the world of money and business, it is the symbol of excellence and the benchmark of success. Whether you are a retail investor building a retirement nest egg or a multi-billion dollar hedge fund, the quest for Alpha is a quest for a better future.
It is important to remember that Alpha is not guaranteed. It requires a combination of rigorous analysis, technological leverage, and psychological fortitude. For most, the most effective strategy involves a foundation of low-cost Beta—capturing the steady growth of the global economy—complemented by strategic, high-conviction “Alpha” plays where an edge truly exists.
The first letter of the Greek alphabet serves as a constant reminder that in finance, as in language, everything starts with a single step toward understanding. By mastering the concepts of risk, return, and the elusive “Alpha,” investors can navigate the complexities of the modern market with clarity and confidence, ensuring that their capital is not just sitting in the market, but actively working to outperform it.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.