
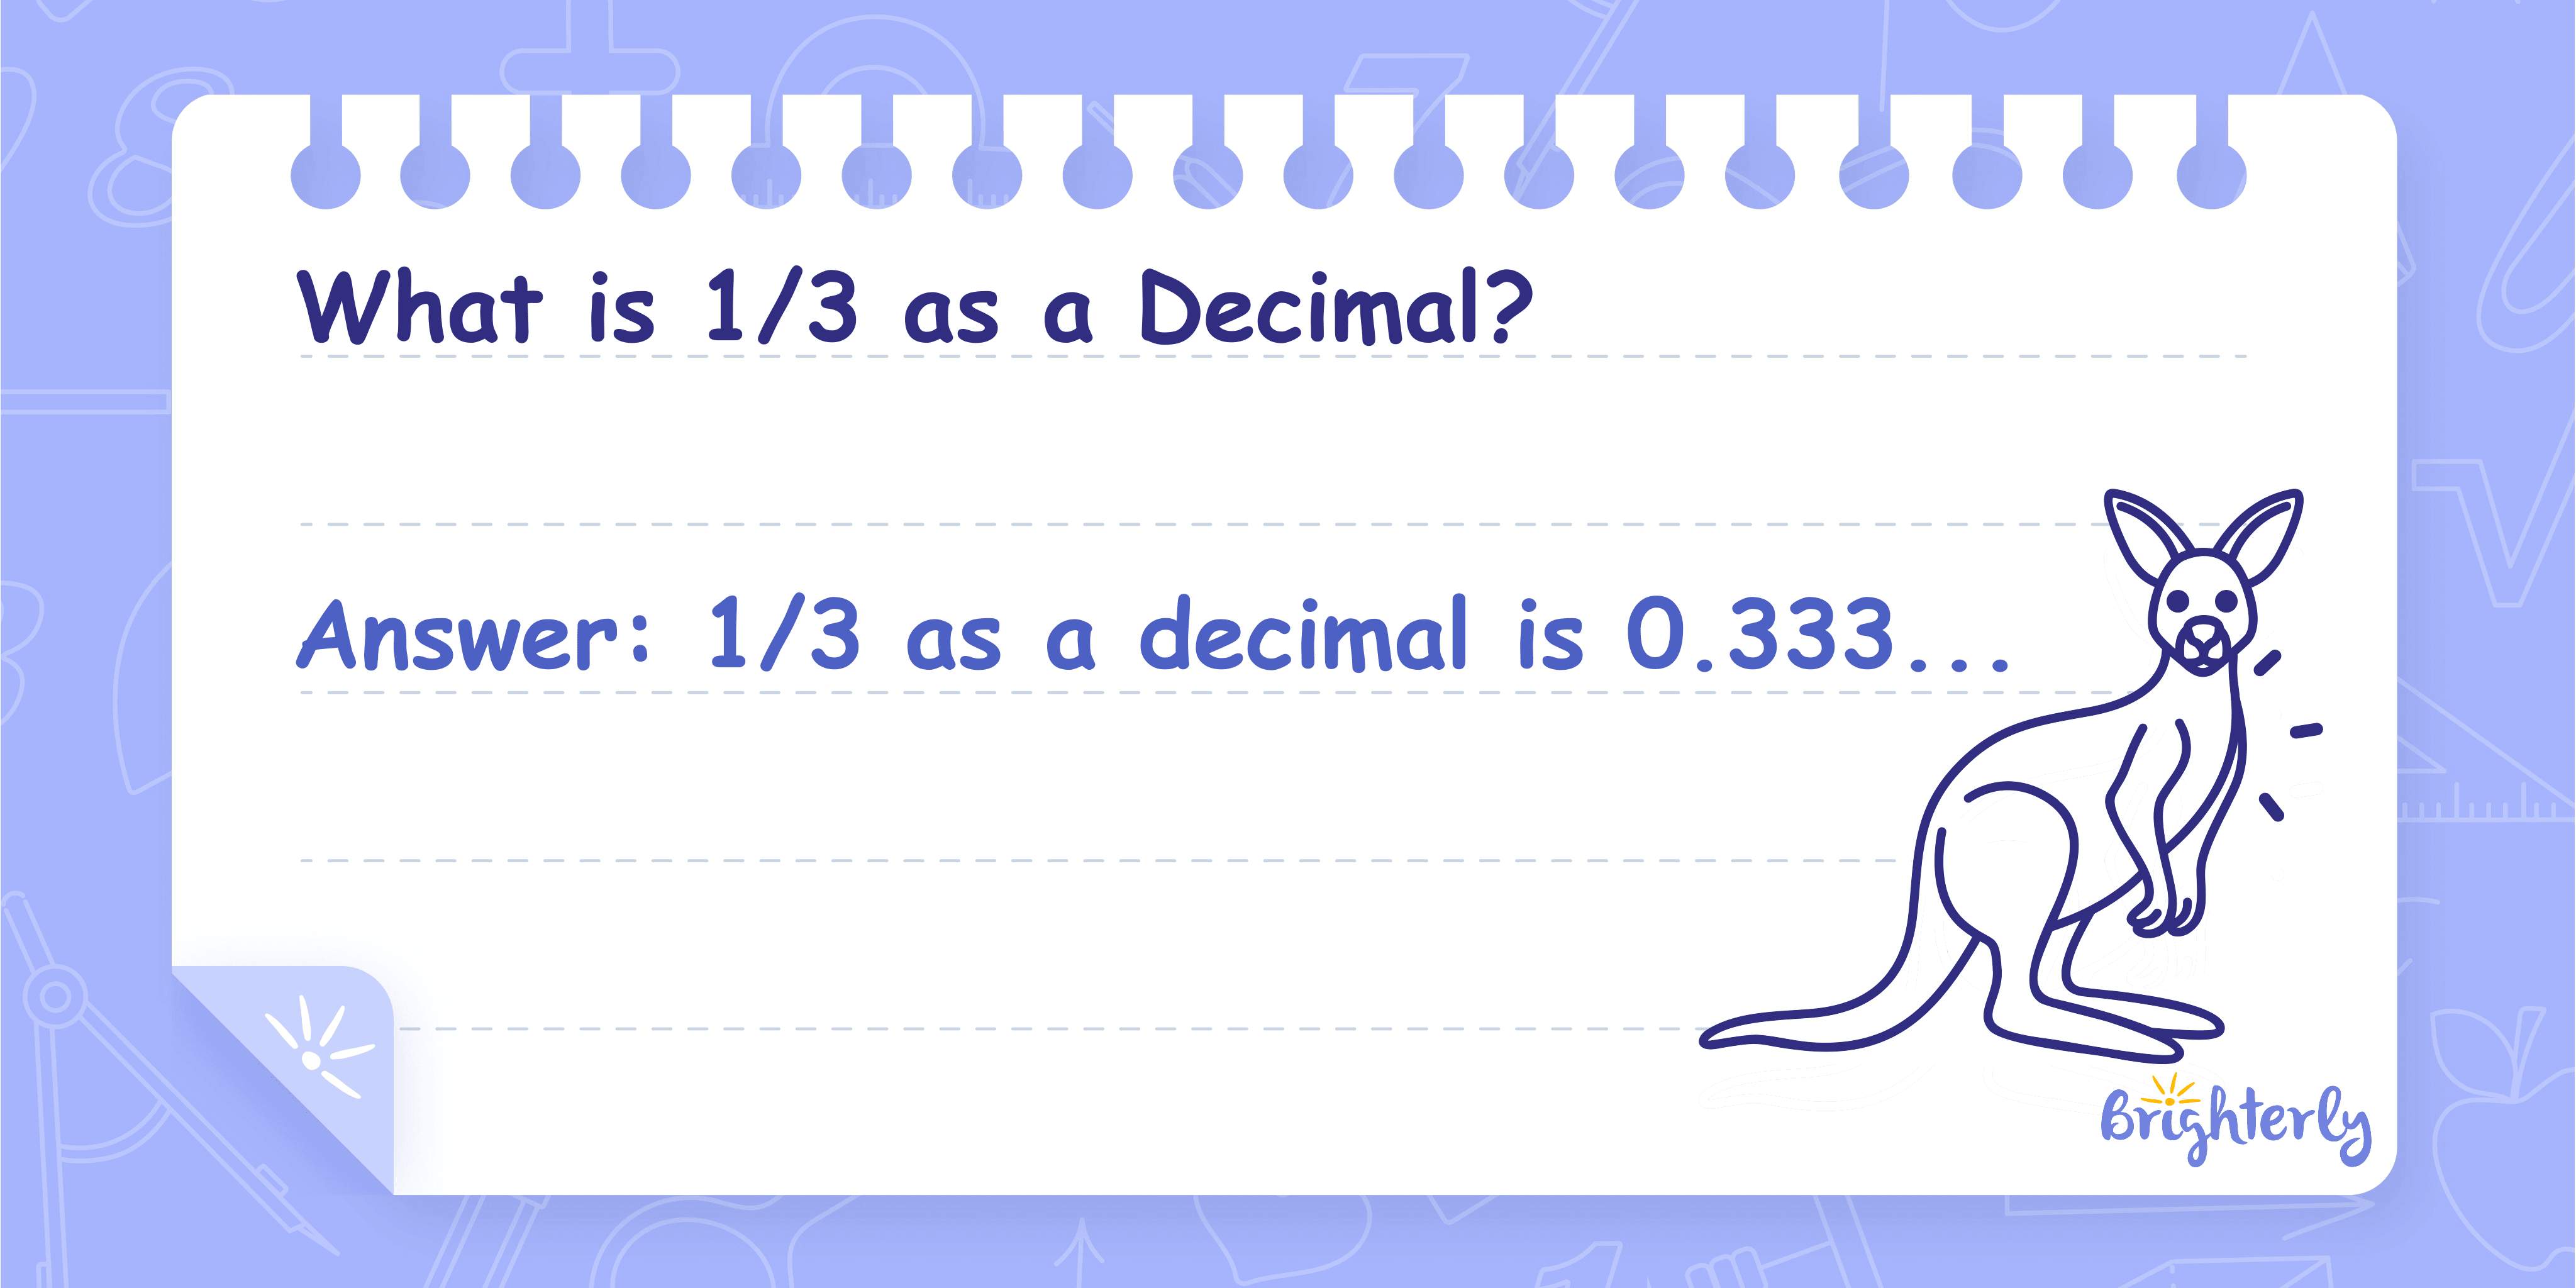
The decimal form of 1/3 is 0.333… — an infinitely repeating decimal where the digit ‘3’ continues without end. While this might seem like a simple mathematical concept, its implications in the world of finance are profound, touching upon precision, budgeting, investing, and the very nature of how we manage and account for money. Understanding not just what 1/3 is in decimal form, but why it matters, is crucial for anyone navigating the complexities of personal finance, business operations, and investment strategies where exactness can mean the difference between profit and loss, or clarity and confusion.

The Fundamental Nature of 1/3 in Financial Calculations
At its core, 1/3 represents a division of a whole into three equal parts. In finance, this fraction frequently arises in scenarios ranging from shared expenses to calculating proportional ownership or returns. However, the conversion to its decimal equivalent, 0.333…, introduces a fascinating challenge: perfect precision becomes elusive without acknowledging the infinite nature of the number.
Understanding Fractions and Decimals in Financial Transactions
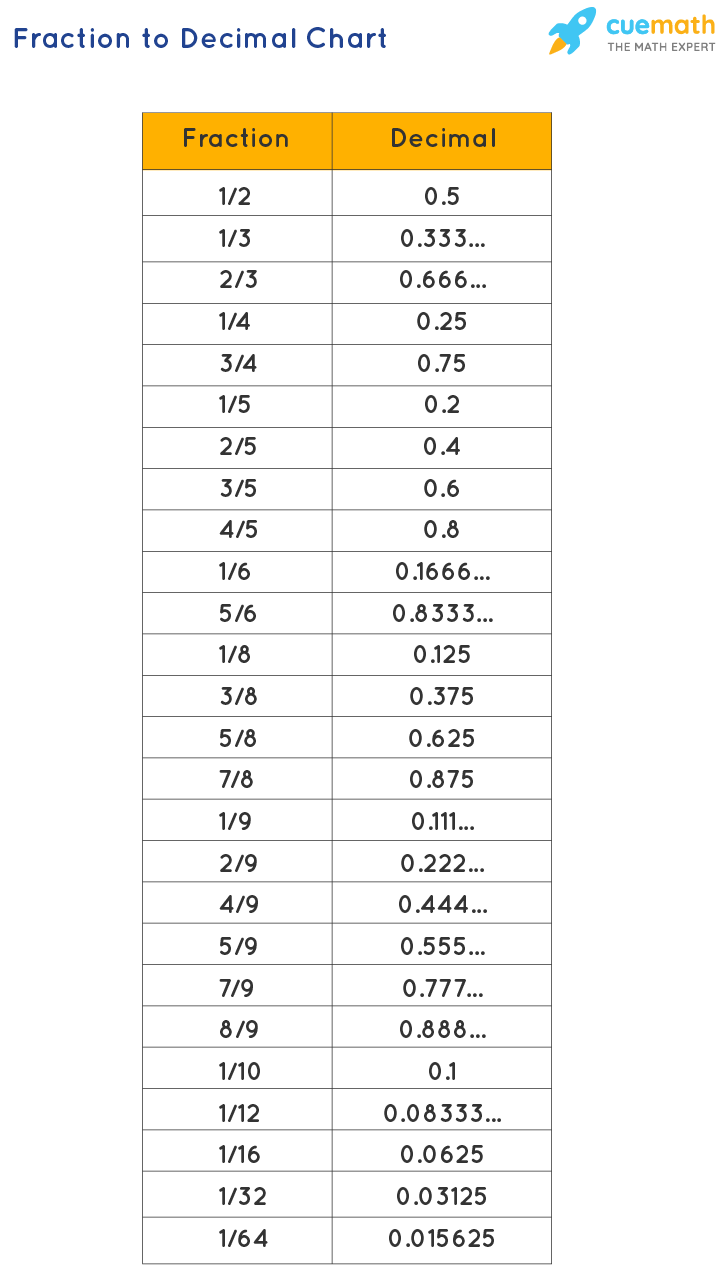
Financial systems, from banking software to trading platforms, predominantly operate using decimals. Stock prices are quoted in dollars and cents (e.g., $10.50), interest rates are expressed as percentages (e.g., 5.25%), and tax rates are applied as decimal multipliers (e.g., 0.25 for 25%). The conversion between fractions and decimals is a daily occurrence, yet it’s often taken for granted. For most fractions, this conversion is straightforward, resulting in terminating decimals (e.g., 1/2 = 0.5, 1/4 = 0.25). These tidy numbers integrate seamlessly into calculations.
However, fractions like 1/3 or 1/7 produce repeating decimals. While mathematically precise, 0.333… presents a practical dilemma in systems designed to handle finite numbers of decimal places. A bank account can’t practically credit someone with 0.333… of a cent; it must round. This rounding, though seemingly minor, can accumulate and have significant financial consequences, especially in large-scale or long-term financial contexts. It underscores the critical need for financial literacy that extends beyond simple arithmetic to grasp the nuances of numerical representation in real-world monetary applications.
The Peculiar Case of 0.333… and Its Real-World Impact
The repeating decimal 0.333… means that you can never perfectly represent 1/3 using a finite number of decimal places. This mathematical reality has tangible consequences in finance:
-
Shared Costs: Imagine three roommates splitting a $100 utility bill. Dividing by three yields $33.333… per person. If two pay $33.33 and one pays $33.34, someone is technically paying an extra penny, or the landlord might be short by a penny. While a penny seems negligible, in formal accounting, every cent must be accounted for.
-
Investment Ownership: If a fund holds shares and distributes them based on a fractional ownership that results in 1/3, the process of allocating those shares or the dividends they generate must contend with this recurring decimal. Fractional share investing has become more common, allowing individuals to own portions of a single share, but the underlying calculations for true ownership percentages and payouts can become complex if not managed carefully.
-
Taxation and Proportions: Governments often levy taxes based on percentages or proportions. If a tax rate is precisely 1/3 of a certain income bracket, the actual calculation will involve rounding, which needs to be consistent and legally defined to avoid discrepancies.
The recurring nature of 0.333… forces financial systems and individuals to make decisions about rounding. Understanding these decisions, and their potential implications, is a key component of robust financial management.
Precision vs. Approximation: When Every Cent Counts
In finance, the adage “a penny saved is a penny earned” highlights the importance of every unit of currency. While rounding seems innocuous, the cumulative effect of small approximations can distort financial pictures, impact balances, and even lead to disputes, especially when dealing with transactions involving large sums or over extended periods.
Budgeting and Expense Allocation
Budgeting is fundamentally about allocating a finite amount of money. When dividing expenses among multiple parties or across different categories, encountering fractions like 1/3 is common. Consider a small business with three partners who agree to split all expenses equally. A $1,000 marketing expense would mean each partner owes $333.333…
-
Practical Implications: In practice, one partner might pay $333.34 and the other two $333.33. Over numerous transactions, the “extra penny” shifts. For informal arrangements, this might be overlooked, but in formal business accounting, such minor discrepancies must be reconciled. If not, the books won’t balance perfectly, causing headaches during audits or financial reviews.
-
Resolution Strategies: Clear agreements are essential. Partners might agree to rotate who pays the extra penny, or to simply let small differences accumulate and settle them periodically, or to use a common pot for such fractional remainders. The key is transparency and a predefined method for handling these inevitable rounding scenarios.
Investing and Returns
The world of investing, particularly with the rise of fractional share ownership and complex financial instruments, demands a high degree of precision.
-
Fractional Shares: Many brokerage platforms now allow investors to buy fractional shares. For instance, if a share costs $300 and you want to invest $100, you’d own 1/3 of a share (0.333…). When dividends are paid, you receive 1/3 of the dividend amount. If the dividend is, say, $1.00 per share, you would receive $0.333…, which the brokerage must then round to $0.33 or $0.34 for distribution. While trivial for a single instance, imagine this across thousands of investors or millions of shares over years.
-
Compound Interest: The magic of compound interest relies on exact calculations. Interest is often compounded daily or monthly, meaning even tiny fractions of a cent earned each period contribute to the principal for the next period’s calculation. If a financial institution consistently rounds down a recurring decimal in your favor or against it, the cumulative effect over decades on a significant sum can be substantial. A seemingly minor difference in how 1/3 of a percentage point is calculated can lead to thousands of dollars difference in the total return of a long-term investment.
-
Performance Metrics: Calculating investment returns, expense ratios, or portfolio allocations often involves divisions that can yield repeating decimals. Analysts and investors need to be aware of how these numbers are being rounded and ensure consistency when comparing different investments or periods.
Taxation and Financial Reporting
Tax laws are built on strict definitions and precise calculations. Tax rates, deductions, and credits are often expressed as percentages or specific fractions.
-
Tax Liabilities: If a tax bracket specifies that 1/3 of income over a certain threshold is taxable, the exact calculation of that 1/3 for millions of taxpayers must adhere to strict rounding rules set by tax authorities. These rules dictate whether to round up, down, or to the nearest cent. Deviations, even small ones, can lead to incorrect tax payments, audits, and penalties.
-
Business Accounting: For companies, maintaining accurate financial records is paramount. Every transaction, asset, and liability must balance. When revenues or expenses are divided or allocated based on fractions that produce repeating decimals, the accounting system must have a consistent method for handling the remainder. This is particularly crucial for multi-currency transactions, intercompany allocations, or complex revenue recognition models. Auditors scrutinize these practices to ensure compliance and accuracy.
Tools and Strategies for Managing Fractional Finance
Navigating the complexities introduced by repeating decimals like 0.333… requires both awareness and the intelligent application of financial tools and best practices. Modern financial technology has largely automated the handling of these numerical nuances, but user understanding remains vital.
Leveraging Financial Software and Spreadsheets
Spreadsheets like Microsoft Excel, Google Sheets, and specialized accounting software are indispensable for financial management. They are designed to handle complex calculations and typically manage precision internally with a very high number of decimal places (e.g., up to 15 significant digits in Excel) before displaying or rounding for user readability.
-
Internal Precision: While a spreadsheet cell might display “0.33,” its underlying calculation could be using 0.333333333333333. This internal precision is crucial for ensuring that sums and subsequent calculations remain as accurate as possible.
-
Display vs. Calculation: Users must understand the difference between a cell’s displayed value and its actual calculated value. Applying currency formatting often rounds to two decimal places, but the original underlying value is still used in formulas. This can lead to situations where a column of numbers appears to sum to one value, but the actual calculated sum differs slightly due to internal precision.
-
Rounding Functions: Spreadsheets offer specific rounding functions (e.g., ROUND, ROUNDUP, ROUNDDOWN). Financial professionals use these deliberately to align calculations with legal or practical rounding requirements, especially when final outputs like invoices or financial statements need to adhere to specific penny values.
The Importance of Clear Communication in Shared Finances
Whether in business partnerships, family budgets, or informal expense splits, clear communication about how fractional amounts will be handled is essential to prevent misunderstandings and disputes.
-
Pre-defined Rules: Before embarking on shared financial ventures, establish a clear policy for dealing with remainders. Will they be rounded up for one party and down for another? Will a “kitty” be maintained for tiny discrepancies?
-
Documentation: Documenting these agreements, even for small sums, can save significant headaches later. This is particularly true for shared investments, property ownership, or ongoing business ventures where financial accountability is critical.
-
Transparency: In any shared financial arrangement, transparency fosters trust. Showing the actual calculations and how rounding decisions were made builds confidence among all parties involved.
Strategic Rounding and Its Consequences
Rounding isn’t just a technical necessity; it can be a strategic decision with financial implications.
-
“Penny Rounding” in Accounting: In some accounting systems, especially for payroll or sales tax, “penny rounding” is a specific practice where individual line items might be rounded, and the total adjusted to ensure the overall sum is an exact dollar and cent figure.
-
Impact on Stakeholders: A company might choose to consistently round up when calculating customer charges (within legal limits) or round down when calculating supplier payments. These small strategic choices, when scaled, can impact profitability or relationships.
-
Legal and Regulatory Compliance: Financial institutions and businesses must adhere to strict legal and regulatory guidelines regarding how they handle rounding, particularly for consumer interest rates, loan amortizations, and tax calculations. Non-compliance can lead to hefty fines and reputational damage.
Beyond 1/3: A Mindset for Financial Acuity
Understanding the decimal form of 1/3 is a gateway to a broader financial acumen. It encourages a deeper appreciation for numerical precision, the limitations of digital systems, and the critical thinking required to make informed financial decisions.
Developing Quantitative Literacy
The seemingly simple question of 1/3’s decimal form underscores the importance of quantitative literacy – the ability to understand and reason with numbers in real-world contexts. For finance, this means:
-
Understanding Percentages and Ratios: Beyond basic arithmetic, comprehending how percentages (which are essentially fractions of 100) are derived and applied to interest, returns, and taxes is fundamental.
-
Interpreting Financial Data: Financial reports are rich with numbers, graphs, and ratios. A solid quantitative background allows individuals to critically analyze these reports, identify trends, and spot potential misrepresentations or anomalies.
-
Evaluating Financial Products: From mortgage rates to investment fees, understanding the underlying calculations and how different terms can impact total costs or returns is crucial for choosing the best financial products.
Questioning Financial Assumptions
The insight gained from exploring 1/3’s decimal form should foster a healthy skepticism and a proactive approach to financial matters.
-
Don’t Just Accept Face Value: Always question how numbers are presented. Is a “33%” discount truly 1/3 off, or is it a rounded figure? How does the rounding impact the final price?
-
Read the Fine Print: Particularly with financial products, the “fine print” often details how interest is calculated, how fees are applied, and how rounding might occur. Understanding these details can prevent unpleasant surprises.
-
Empowerment Through Knowledge: By understanding the nuances of numbers, individuals are better equipped to challenge financial advice, negotiate terms, and make decisions that truly align with their financial goals, rather than passively accepting what is presented to them.
In conclusion, the decimal form of 1/3, 0.333…, is far more than an academic curiosity. It is a practical lesson in financial precision, the challenges of numerical representation, and the critical importance of understanding how money is accounted for and managed in a world that often demands exactitude. Mastering this seemingly small concept contributes significantly to developing robust financial literacy and making wiser financial choices.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.