
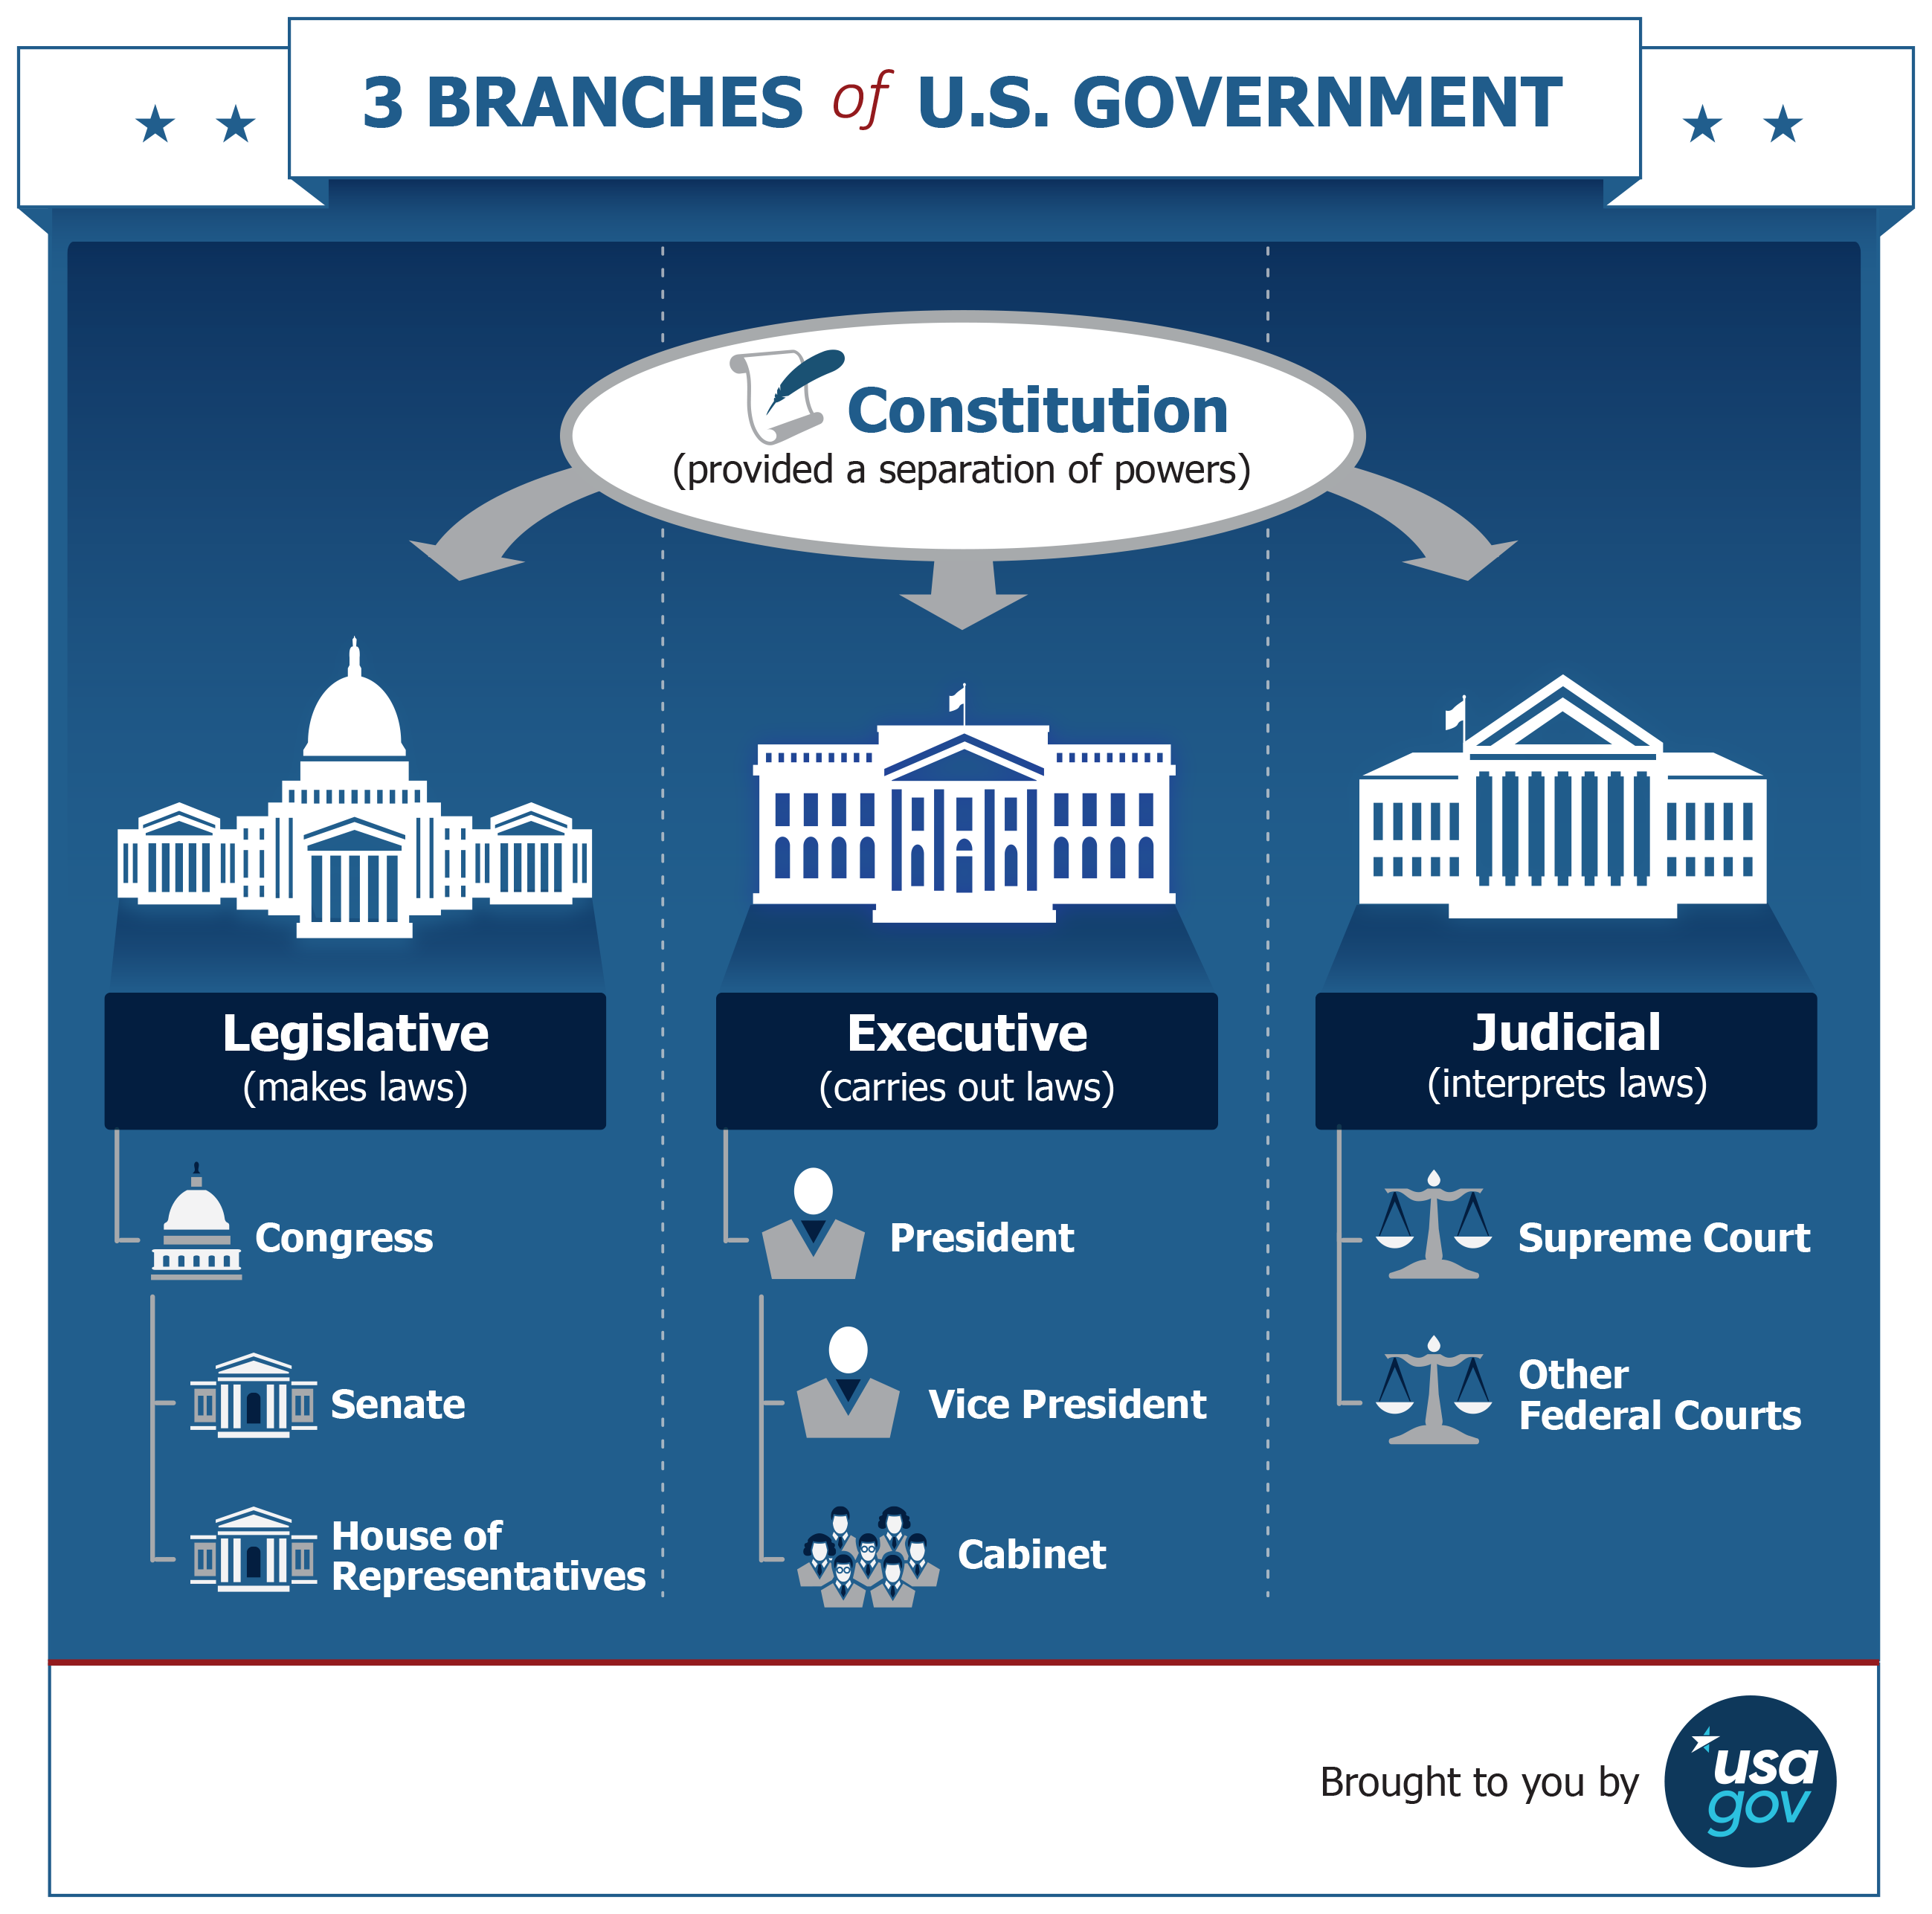
In the architecture of modern democracy, the legislative branch stands as the primary engine of structural change. While many citizens view the question “what is the branch of government that makes laws” as a simple civics refresher, for the savvy investor and the financially conscious individual, the answer carries profound implications for wealth preservation, market volatility, and long-term economic planning. In the United States, this power resides in Congress—the House of Representatives and the Senate.
This branch does more than just draft statutes; it controls the “power of the purse,” dictates the tax code, and sets the regulatory boundaries within which all businesses must operate. Understanding how this branch functions is not merely an academic exercise; it is a fundamental requirement for navigating the complexities of personal finance and investment strategy.
The Legislative Powerhouse: Fiscal Policy and the Economy
The legislative branch is the sole entity with the constitutional authority to create federal laws, and among its most significant powers is the control over fiscal policy. Unlike the executive branch, which implements laws, or the judicial branch, which interprets them, the legislative branch decides how much money the government will collect and how it will be spent.
The Power of the Purse: How Spending Bills Affect Inflation
Every dollar that enters the economy via government spending starts as a bill in the halls of Congress. When the legislative branch passes massive spending packages—whether for infrastructure, social programs, or defense—it directly influences the money supply and aggregate demand. For the individual, this means that the legislative branch is often the primary driver of inflation or deflation.
When Congress authorizes high levels of deficit spending, it can lead to an increase in the money supply, potentially eroding the purchasing power of your savings. Conversely, during periods of fiscal restraint, the legislative branch can act as a cooling mechanism for an overheated economy. Investors must monitor the legislative calendar, as the passage of a major budget resolution can signal upcoming shifts in consumer prices and interest rate trajectories.
Taxation and Regulation: The Legislative Impact on Disposable Income
Perhaps the most direct way the branch that makes laws impacts your wallet is through the tax code. The Internal Revenue Service (IRS) may collect taxes, but it is the legislative branch that writes the Internal Revenue Code. Every deduction, credit, and tax bracket is the result of a negotiated piece of legislation.
For those focused on personal finance, legislative shifts in tax policy can represent either a massive windfall or a significant hurdle. For instance, changes to the capital gains tax rate can alter the attractiveness of long-term stock holdings versus short-term trading. Similarly, adjustments to the corporate tax rate by Congress directly impact the earnings reports of publicly traded companies, which in turn dictates stock prices. When the legislative branch decides to “make a law” regarding taxes, it is essentially deciding how much of your hard-earned income remains in your pocket.
How Congressional Decisions Influence Your Investment Portfolio
Modern markets do not operate in a vacuum. They are deeply reactive to the legislative environment. Because the legislative branch has the power to regulate commerce and oversee specific industries, its actions can create “winners” and “losers” in the stock market overnight.
Sector-Specific Legislation: Winners and Losers in the Stock Market
When the legislative branch pivots its focus toward a specific industry, investors must take note. For example, if Congress passes a comprehensive green energy bill, subsidies and tax credits are often funneled toward renewable energy companies, driving up their valuations. On the flip side, the same branch can introduce restrictive regulations or “windfall profit” taxes on traditional energy sectors, creating a bearish environment for oil and gas stocks.
Healthcare is another sector where the legislative branch wields immense power. Laws regarding drug pricing, insurance mandates, and Medicare reimbursement rates are all products of the legislative process. A single vote in a Senate committee can cause the share prices of pharmaceutical giants to fluctuate by billions of dollars. Wealth management requires a keen eye on these legislative movements to ensure a portfolio is positioned to benefit from—rather than be crushed by—new laws.
Interest Rates and Debt: The Legislative-Executive Synergy
While the Federal Reserve is technically independent, its actions are often a response to the fiscal environment created by the legislative branch. When Congress passes laws that increase the national debt, the Treasury must issue more bonds. This increased supply of government debt can influence yields across the board, affecting everything from mortgage rates to the return on high-yield savings accounts.

Furthermore, the legislative branch is responsible for setting the debt ceiling. The political theater surrounding the debt limit is a recurring source of market anxiety. When the branch that makes laws struggles to reach a consensus on the debt ceiling, it introduces “sovereign risk” into the equation, which can lead to credit rating downgrades and massive volatility in the bond market.
The Financial Tools Shaped by Federal Law
The very vehicles we use to build wealth—401(k)s, IRAs, and 529 plans—are not natural phenomena. They are legislative constructs. The “branch that makes laws” created these tools to encourage specific financial behaviors, and it has the power to change them at any time.
Retirement Accounts: From the 401(k) to the SECURE Act
The modern retirement landscape is defined by the Employee Retirement Income Security Act (ERISA) and its subsequent amendments, such as the SECURE Act and SECURE 2.0. These laws, passed by the legislative branch, determine your contribution limits, the age at which you must take required minimum distributions (RMDs), and the tax advantages of various accounts.
For example, the recent passage of SECURE 2.0 by Congress significantly changed the rules for “catch-up” contributions for older workers and modified the age for RMDs. These legislative tweaks require individuals to constantly update their financial plans. Without the legislative branch’s intervention, the private retirement system as we know it would not exist. Understanding that these accounts are subject to the whims of future legislation is a critical component of risk management.
Student Loans and Education Funding: A Legislative Tug-of-War
For many young professionals, student loan debt is the largest hurdle to building net worth. The interest rates, repayment terms, and forgiveness programs associated with federal student loans are all dictated by the legislative branch. When Congress passes a law to freeze interest rates or expand the Public Service Loan Forgiveness (PSLF) program, it effectively changes the balance sheets of millions of households.
The legislative branch also governs 529 college savings plans. Recent legislation has expanded the utility of these plans, allowing for leftover funds to be rolled into Roth IRAs under certain conditions. This is a prime example of how the branch that makes laws can enhance financial flexibility for those who stay informed about policy changes.
Navigating Political Risk in Personal Finance
Since the legislative branch is the primary source of economic “rules,” its inherent instability—driven by election cycles and partisan shifts—introduces what financial analysts call “political risk.” Managing this risk is essential for protecting your online income, side hustles, and long-term investments.
Diversification as a Defense Against Legislative Shifts
Because the legislative branch can pivot on policy, diversification is more than just a tool for market volatility; it is a hedge against legislative volatility. If your entire net worth is tied up in a sector currently favored by the majority party in Congress, you face significant “concentration risk” if the next election flips the legislative balance.
For instance, a portfolio heavily weighted in tech might be vulnerable to new anti-trust laws or data privacy regulations passed by a more interventionist Congress. By diversifying across different asset classes and sectors, you ensure that no single law can derail your entire financial strategy.

Staying Informed: Tracking Bills that Impact Your Bottom Line
In the digital age, tracking the “branch that makes laws” is easier than ever, yet few people do it effectively. Following the progress of bills through committees (such as the House Ways and Means Committee or the Senate Finance Committee) provides a lead time that most retail investors ignore.
When a bill that significantly alters corporate tax rates or environmental regulations gains momentum, the market usually prices in the change long before the President signs it into law. By understanding the legislative process—how a bill becomes a law—you can anticipate market moves rather than merely reacting to them. This proactive approach is what separates professional wealth managers from casual observers.
The legislative branch is not just a subject for history books; it is the most powerful architect of our financial reality. Every law it makes ripple through the economy, affecting the value of the dollar, the profitability of corporations, and the tax efficiency of your retirement plan. By recognizing that Congress is the “branch that makes laws,” and by extension, the branch that makes the rules of the financial game, you can better position yourself to thrive in an ever-changing economic landscape. Stay vigilant, stay informed, and always consider the legislative context of your financial decisions.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.