
For millions of high school students each year, the SAT is more than just another test; it’s a gateway to higher education, a determinant of scholarship eligibility, and an often-underestimated factor in long-term financial planning. Understanding “what is the average for SAT scores” isn’t merely an academic curiosity; it’s a crucial piece of the puzzle when strategizing for college admissions, financial aid, and ultimately, one’s future economic trajectory. In the intricate world of personal finance, the choices made during the college application process, heavily influenced by test scores, can ripple through decades, impacting everything from student debt burdens to earning potential and even early investment capabilities. This article delves into the average SAT score, dissecting its significance through a purely financial lens, and exploring how students and families can leverage this understanding to make smarter, more profitable educational investments.
The SAT Score Landscape: A Financial Lens on Academic Performance
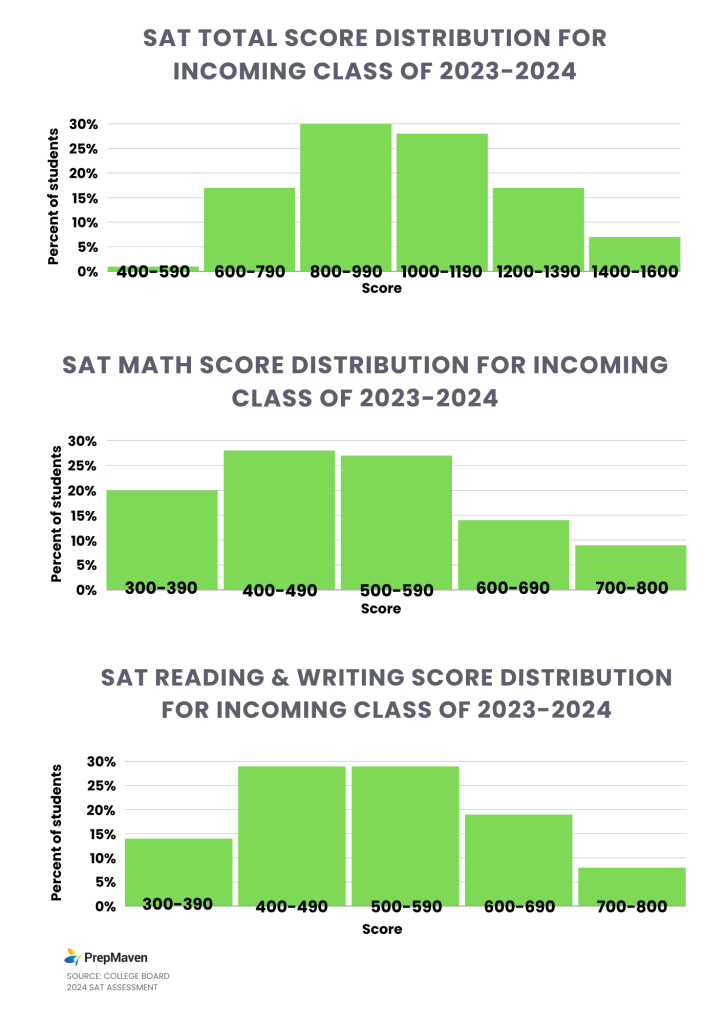
The SAT, administered by the College Board, is a standardized test widely used for college admissions in the United States. It evaluates critical reading, writing and language, and math skills. Each section is scored on a scale of 200-800, leading to a total composite score range of 400-1600. When considering the average, we’re looking at a benchmark, but more importantly, we’re assessing its implications for financial strategy.
Deconstructing the National Average: What it Means for Your Wallet
The national average SAT score fluctuates slightly year by year, reflecting shifts in test-taker demographics and performance. For recent years, the average composite score has hovered around 1050-1060 out of 1600. While this number provides a general benchmark, its financial significance lies in its context. A score significantly above this average can unlock a cascade of financial opportunities, primarily through merit-based scholarships and increased access to institutions known for higher post-graduation earning potentials. Conversely, a score at or below the average might necessitate a more intensive search for need-based aid, a reevaluation of college choices towards more affordable options, or a heavier reliance on student loans—all of which have direct impacts on a family’s budget and a student’s future financial health. Understanding where a student’s score stands relative to this national average is the first step in crafting a financially sound college plan. It’s not just about getting into college; it’s about getting into college affordably.
Beyond the Score: Percentiles and Their Monetary Value
While the raw score provides a number, the percentile rank offers a more nuanced understanding of a student’s performance relative to their peers. For instance, if a student scores in the 75th percentile, it means they scored higher than 75% of all test-takers. This distinction holds significant monetary value. Colleges often use percentile ranks, not just raw scores, to award merit-based scholarships. A student scoring in the 90th percentile or above, for example, might find themselves eligible for substantial institutional grants or full-tuition scholarships at various universities. These scholarships directly reduce the out-of-pocket cost of education, turning what would have been a significant liability into a more manageable, or even fully funded, investment. Even a jump from the 50th percentile to the 60th percentile, while seemingly small, can sometimes be enough to cross a scholarship threshold at certain institutions, leading to thousands of dollars in savings over four years. This makes improving one’s percentile rank not just an academic goal, but a direct financial objective.
Regional Disparities and Economic Factors Influencing Averages
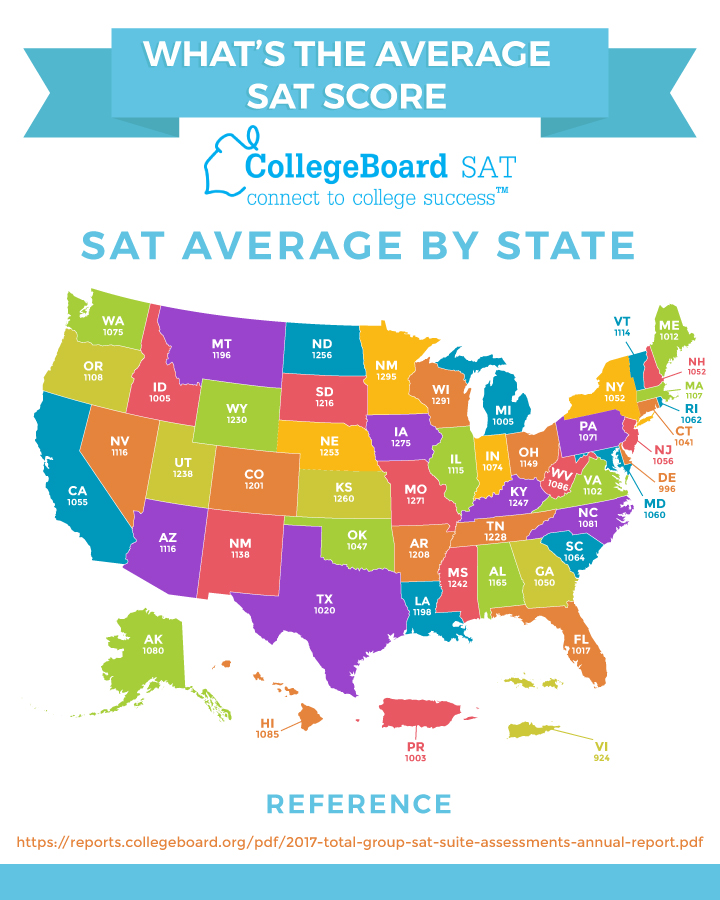
It’s also crucial to acknowledge that SAT averages are not uniform across the United States; they vary significantly by state and even by school district. These regional disparities often correlate with differing levels of public school funding, access to test preparation resources, and socio-economic conditions. In states with higher average household incomes and greater investment in education, average SAT scores tend to be higher. From a financial perspective, this creates a challenging landscape. Students from regions with lower average scores might face an uphill battle when competing for scholarships against peers from high-scoring areas, potentially leading to greater financial strain. Conversely, some colleges actively seek geographic diversity and may offer scholarships to strong students from underrepresented regions, making it a strategic advantage. Recognizing these economic and geographic factors allows families to tailor their college search and financial aid applications more effectively, potentially identifying institutions or scholarships that value a broader range of student profiles and backgrounds.
Strategic Investment: Leveraging SAT Scores for Optimal College Finance
Viewing college education as a significant financial investment fundamentally changes how one approaches the SAT. It transitions from being merely a test to a powerful financial tool that, when wielded strategically, can significantly reduce costs and maximize returns.
Maximizing Merit Scholarships: The Direct Financial Benefit of High Scores
This is perhaps the most direct and impactful financial benefit of a strong SAT score. Merit scholarships are awards based on academic achievement, talent, or other specific criteria, rather than financial need. Universities, particularly private ones, use high SAT scores as a key indicator of academic promise, and they are often willing to offer substantial, sometimes full, scholarships to attract top-tier students. Imagine reducing your annual tuition bill by $10,000, $20,000, or even more, simply by achieving a high score. Over four years, this can translate into savings of $40,000 to $80,000 or more—a staggering amount that directly impacts the student’s future debt burden and capacity for financial independence. Investing time and resources into SAT preparation can thus be seen as an extremely high-return investment, yielding far greater dividends than many traditional financial instruments in the short term.
Navigating Financial Aid Packages: How SAT Scores Influence Offerings
While merit scholarships are directly tied to academic performance, need-based financial aid is primarily determined by a family’s demonstrated financial need. However, the influence of SAT scores isn’t entirely absent. A strong academic profile, including high SAT scores, can make a student a more attractive candidate for institutional grants—money from the college itself that doesn’t need to be repaid. In competitive admissions cycles, colleges often have a pool of discretionary funds they can allocate to “package” attractive students. A student with strong SAT scores might receive a more generous package that combines institutional grants, federal grants, and perhaps a manageable loan component, compared to a student with similar financial need but lower academic standing. Furthermore, a high SAT score might open doors to colleges that are “generous” with aid, offering better overall financial packages, effectively lowering the net price of attendance. This strategic interplay between academic performance and financial aid offerings underscores the financial weight of SAT performance.
Public vs. Private ROI: Matching Scores to Economic Returns on Education

The decision between a public state university and a private institution is often fraught with financial considerations. Public universities generally have lower tuition costs, especially for in-state residents, but may offer fewer large merit scholarships directly tied to SAT scores, relying more on broad academic performance for in-state tuition waivers. Private universities, while often having significantly higher sticker prices, are also more likely to offer substantial merit aid packages, making them surprisingly affordable for students with high SAT scores.
Calculating the Return on Investment (ROI) for higher education is critical. A high SAT score might allow a student to attend a top-tier private university with a strong alumni network and career services, leading to higher starting salaries and quicker career progression, effectively boosting their long-term ROI even if the initial net cost is slightly higher than a public alternative. Conversely, a strong SAT score can secure a spot and potentially some aid at a flagship public university, offering an excellent education at a significantly lower cost. The optimal financial strategy involves matching a student’s SAT score and academic profile with institutions that offer the best balance of educational quality, financial aid, and post-graduation economic prospects. This careful consideration directly impacts future earning capacity and the overall financial health of the graduate.
Long-Term Financial Planning: The Ripple Effect of Your SAT Performance
The immediate financial impact of SAT scores through scholarships and aid is clear, but their influence extends far beyond graduation. The college chosen, partly due to SAT performance, sets the stage for a student’s entire professional and financial life.
College Choice and Future Earning Potential: A Direct Correlation
Numerous studies demonstrate a correlation between the selectivity and reputation of an undergraduate institution and the future earning potential of its graduates. While correlation doesn’t always equal causation, the networks, career services, brand recognition, and educational quality offered by highly selective institutions (which often require above-average SAT scores for admission) frequently translate into higher starting salaries and faster career advancement. For a student with a high SAT score, choosing a college that offers not only financial aid but also a strong track record of graduate success can be a shrewd financial move. Over a lifetime, the difference in earnings between graduates from different tiers of institutions can be hundreds of thousands, if not millions, of dollars. This long-term earning power is a cornerstone of financial independence, impacting everything from homeownership to retirement savings and investment portfolios.
Mitigating Student Debt: How Smart College Choices, Backed by Scores, Pay Off
Student loan debt is a pervasive financial challenge for many graduates. The average student loan debt in the U.S. is substantial, often hindering individuals from achieving other financial milestones like buying a home, saving for retirement, or starting a business. A strong SAT score, by opening doors to scholarships and more generous financial aid packages, directly contributes to mitigating this debt burden. Choosing a college that offers significant merit aid or has a lower net price (after grants and scholarships) means graduating with less debt. Less debt translates into more disposable income post-graduation, allowing for earlier investment, faster wealth accumulation, and greater financial freedom. This proactive approach to debt reduction, significantly influenced by early academic performance like the SAT, is a critical component of sound personal finance. It frees up capital that would otherwise be allocated to loan payments, enabling it to be directed towards growth-generating assets.
The Entrepreneurial Edge: Education, Skills, and Financial Independence
For those with aspirations of entrepreneurship, online income, or building a side hustle into a main venture, a strong educational foundation can be invaluable. Colleges, particularly those with strong academic programs often favored by high SAT scorers, cultivate critical thinking, problem-solving, analytical skills, and robust professional networks. These are precisely the attributes that fuel successful business ventures and innovative income streams. A degree from a reputable institution, potentially made affordable by high SAT scores, signals a level of discipline and intellectual capability that can inspire confidence in investors, partners, and clients. Furthermore, the alumni networks of top universities can be goldmines for mentorship, seed funding, and collaboration—all essential ingredients for entrepreneurial success and achieving financial independence outside traditional employment structures. Thus, the SAT’s role extends beyond merely securing a job; it can be a foundational step toward creating one’s own financial destiny.
Financial Tools and Resources for the College-Bound Journey
Navigating the financial complexities of higher education requires more than just good test scores; it demands proactive planning, diligent research, and savvy use of available resources.
Pre-College Financial Literacy: Budgeting and Saving for Higher Education
For families embarking on the college journey, early financial literacy is paramount. This involves rigorous budgeting, consistent savings, and understanding the various financial instruments available. Tools like 529 college savings plans offer tax advantages for educational expenses, while setting up a dedicated savings account helps families earmark funds. It’s crucial for students and parents to collaboratively create a comprehensive budget that not only accounts for tuition but also for room and board, books, supplies, transportation, and personal expenses. Understanding the total cost of attendance (COA) versus the net price (COA minus grants and scholarships) is vital. Financial aid calculators on college websites can provide early estimates, helping families set realistic expectations and adjust their financial strategies long before application deadlines. This pre-planning helps minimize financial stress and ensures that the financial implications of SAT scores and college choices are fully understood.
Exploring Alternative Funding: Beyond Traditional Loans and Scholarships
While scholarships influenced by SAT scores and traditional student loans are common, a broader financial strategy includes exploring alternative funding avenues. Grants, unlike loans, do not need to be repaid and can come from federal, state, or private organizations. Work-study programs allow students to earn money through part-time jobs on campus, directly offsetting living expenses. Furthermore, the rise of the gig economy and online income opportunities means students can actively pursue side hustles during college to supplement their income and reduce reliance on loans. From freelance writing and graphic design to tutoring and virtual assistance, these ventures not only provide financial support but also offer valuable real-world experience. Encouraging students to develop entrepreneurial skills and pursue these avenues aligns perfectly with a long-term strategy for financial independence and minimizing post-graduation debt.
Post-Graduation Financial Planning: From Debt Repayment to Investing
The financial journey doesn’t end with graduation; in many ways, it’s just beginning. Graduates, especially those who have strategically leveraged their SAT scores to minimize debt, are better positioned for success. Post-graduation financial planning involves creating a robust budget, aggressively paying down any remaining student loans, establishing an emergency fund, and, most importantly, starting to invest early. The power of compound interest means that every dollar invested early can grow exponentially over time. Understanding investment vehicles like 401(k)s, IRAs, and brokerage accounts is crucial. Financial literacy acquired during college (or through self-study) becomes invaluable in making informed decisions about retirement planning, wealth building, and achieving long-term financial goals. The groundwork laid during the SAT preparation and college selection phase directly impacts the ease and speed with which these post-graduation financial milestones can be achieved, underscoring the profound and lasting financial significance of understanding “what is the average for SAT scores.”
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.