
Private duty nursing represents a unique and increasingly vital segment within the broader healthcare ecosystem, distinguished not only by its personalized care delivery but significantly by its distinct financial model. Unlike the institutional nursing care typically covered by standard health insurance plans or government programs like Medicare/Medicaid in hospitals or skilled nursing facilities, private duty nursing often operates on a direct-pay or specialized insurance basis. To truly understand “what is private duty nursing,” one must delve into its financial underpinnings—how it is funded, its cost implications for clients, and its economic opportunities for nurses and entrepreneurs.
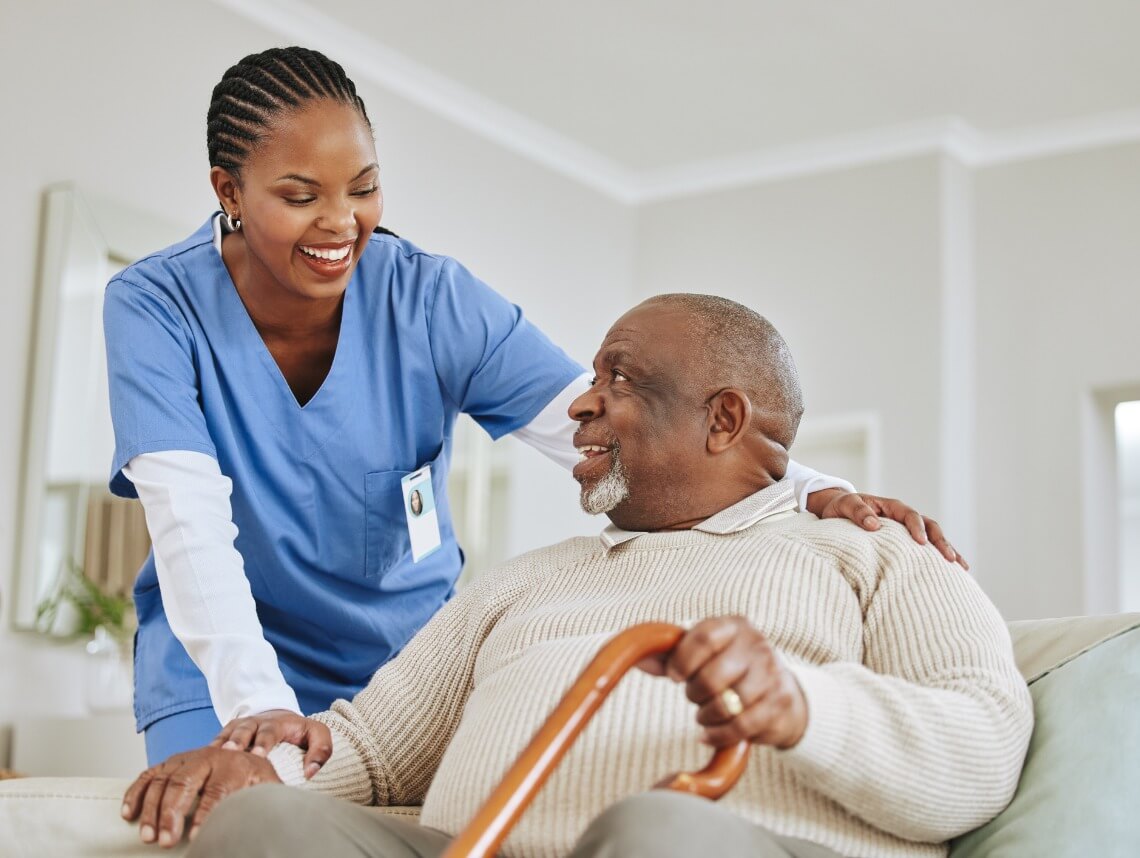
This comprehensive exploration will dissect private duty nursing through a financial lens, offering insights into its funding mechanisms, the economic realities for those seeking care, and the burgeoning income and business opportunities it presents.
The Financial Framework of Private Duty Nursing
Private duty nursing, at its core, is a service where a registered nurse (RN) or licensed practical nurse (LPN) provides one-on-one medical care to a client, typically in their home, but sometimes in other settings like hospitals, assisted living facilities, or during travel. What sets it apart financially is the direct nature of the service and often, its payment structure.
Defining Private Duty Nursing Through a Financial Lens
From a financial perspective, private duty nursing signifies a direct contractual relationship for highly skilled medical care. Clients or their families typically contract directly with an independent nurse or a specialized agency, leading to a financial arrangement that prioritizes individualized care over standardized institutional billing. This model often implies a greater degree of choice and control for the client regarding the nurse’s schedule, specific duties, and even personality match, a flexibility that comes with a different financial commitment. The value proposition here is explicit: premium, personalized medical attention designed to meet complex needs, prevent hospital readmissions, and improve quality of life, often at a premium cost.
Distinguishing Private Duty from Traditional Nursing
The financial distinctions between private duty nursing and traditional nursing are stark. In traditional hospital or clinic settings, nursing care is bundled into facility fees, covered largely by mainstream health insurance (e.g., commercial plans, Medicare, Medicaid). The patient rarely sees a direct line item for nursing services. In contrast, private duty nursing typically involves transparent, hourly rates or package deals paid directly by the client or through specific funding sources.
Payment sources for private duty nursing diverge significantly. While traditional nursing care is usually reimbursed through an established third-party payer system, private duty care heavily relies on:
-
Private Pay (Out-of-Pocket): The most common method, where families directly cover costs.
-
Long-Term Care Insurance: Policies specifically designed to cover extended care services, including skilled nursing at home.
-
Specific Private Health Insurance Riders: Some premium health plans may offer limited coverage or riders for home-based skilled nursing.
-
Workers’ Compensation: In cases of work-related injuries requiring continuous skilled care at home.
-
Veterans Benefits: Certain VA programs can provide financial assistance for eligible veterans requiring home care.
This direct financial engagement underscores the “private” aspect, highlighting a shift away from the institutionalized billing models prevalent in most healthcare settings.
The Cost Components for Clients
Understanding the cost of private duty nursing involves dissecting several key components that factor into the hourly or daily rate:
-
Skill Level and License: RNs typically command higher rates than LPNs due to their broader scope of practice and advanced training.
-
Specialization: Nurses with specialized training (e.g., critical care, wound care, palliative care, ventilator management) or certifications in specific conditions (e.g., Parkinson’s, Alzheimer’s) can charge higher rates due to their niche expertise.
-
Geographic Location: Rates vary significantly by region, reflecting the cost of living and local demand for skilled nursing services.
-
Complexity of Care: Clients requiring more intensive medical interventions, round-the-clock monitoring, or sophisticated equipment management will incur higher costs.
-
Duration and Frequency of Care: While shorter, intermittent visits might have higher hourly rates, long-term, consistent care packages might offer slight discounts.
-
Agency vs. Independent Nurse: Agencies often have overhead costs (insurance, staffing, marketing) that translate to higher hourly rates, but also offer backup nurses, administrative support, and vetted professionals. Independent nurses might offer slightly lower rates but require more direct management from the client or family.
-
Travel and Other Incidentals: Some services may include charges for travel time, specialized supplies, or administrative fees.
These factors combine to determine the final financial commitment for families seeking this level of personalized medical support.
Funding Private Duty Nursing Care
Securing private duty nursing care often necessitates a proactive approach to financial planning, as it frequently falls outside the scope of traditional health insurance benefits for routine, extended home care.
Self-Pay and Out-of-Pocket Expenses
For many families, private duty nursing is a self-funded endeavor. This means individuals or their families directly cover the costs out of their personal savings, retirement funds, or ongoing income. This financial reality often requires careful budgeting, financial counseling, and sometimes difficult decisions about asset liquidation. It emphasizes the importance of early financial planning for long-term care needs, as the costs can be substantial, particularly for complex or continuous care. Families often weigh the financial burden against the invaluable benefits of keeping a loved one at home, maintaining their independence, and receiving highly personalized medical attention.
Long-Term Care Insurance and Other Private Policies
Long-Term Care (LTC) insurance is specifically designed to alleviate the financial strain of extended care, including private duty nursing at home. These policies typically cover a range of services when an individual requires assistance with Activities of Daily Living (ADLs) or suffers from cognitive impairment. However, coverage limits, elimination periods (a waiting period before benefits begin), and specific policy stipulations vary widely. Understanding one’s LTC policy—its daily benefit amount, maximum benefit period, and qualifying triggers—is crucial for effective financial planning. Some premium health insurance policies or riders might also offer limited benefits for skilled home care, though this is less common for comprehensive private duty nursing.
Government Programs and Waivers (Limited Scope)
While private duty nursing largely operates outside of standard government health programs, there are limited instances where state-specific Medicaid waivers or other community-based programs might offer financial assistance. These waivers typically target specific populations (e.g., individuals with disabilities, the elderly meeting certain income and care criteria) to allow them to receive care at home rather than in institutional settings. However, eligibility is often stringent, and the scope of services covered may not always align perfectly with comprehensive private duty nursing as broadly defined. Families must research local and state programs thoroughly, understanding that the “private” aspect of private duty nursing often means a reduced reliance on these publicly funded options.
Veterans Benefits
For eligible veterans, the U.S. Department of Veterans Affairs (VA) offers several programs that can help cover the costs of home-based skilled nursing care, including aspects of private duty nursing. Programs like the Aid and Attendance benefit, or certain comprehensive home care programs, can provide financial aid for veterans who require assistance with daily living activities due to illness or disability. These benefits are means-tested and require specific eligibility criteria, but they represent a significant financial resource for a deserving population, enabling them to receive high-quality medical care in the comfort of their homes.
Private Duty Nursing as an Income Stream and Business Venture
Beyond its role as a critical service for clients, private duty nursing also represents a robust income stream for skilled nurses and a viable business venture for healthcare entrepreneurs.
Income Potential for Nurses
The income potential for private duty nurses is often attractive, offering competitive hourly rates compared to institutional settings. Factors influencing pay include:
-
Specialization and Certification: Nurses with highly sought-after skills (e.g., critical care, ventilator management, hospice care) or specialized certifications can command premium rates.
-
Experience Level: More experienced nurses typically earn more.
-
Geographic Demand: Areas with a high demand for private duty nursing and a lower supply of qualified nurses will often see higher rates.
-
Flexibility and Autonomy: While a benefit, working independently means self-managing taxes, insurance, and benefits, which must be factored into the overall compensation analysis.
-
Negotiation Skills: Independent nurses have the ability to negotiate their rates directly with clients or agencies.
Many nurses are drawn to private duty for the professional autonomy, the ability to build meaningful one-on-one relationships with clients, and the flexibility it can offer over traditional hospital shifts.
Entrepreneurship in Private Duty Nursing
For entrepreneurial nurses or business professionals, establishing a private duty nursing agency presents a significant opportunity. This involves:
-
Business Registration and Licensing: Navigating state and local regulations for healthcare agencies.
-
Staffing and Recruitment: Building a team of qualified RNs and LPNs.
-
Insurance and Bonding: Obtaining necessary professional liability, general liability, and workers’ compensation insurance.
-
Marketing and Client Acquisition: Developing strategies to reach potential clients and referral sources.
-
Financial Management: Managing payroll, billing, accounts receivable, and profitability.
-
Quality Assurance: Ensuring high standards of care and compliance with healthcare regulations.
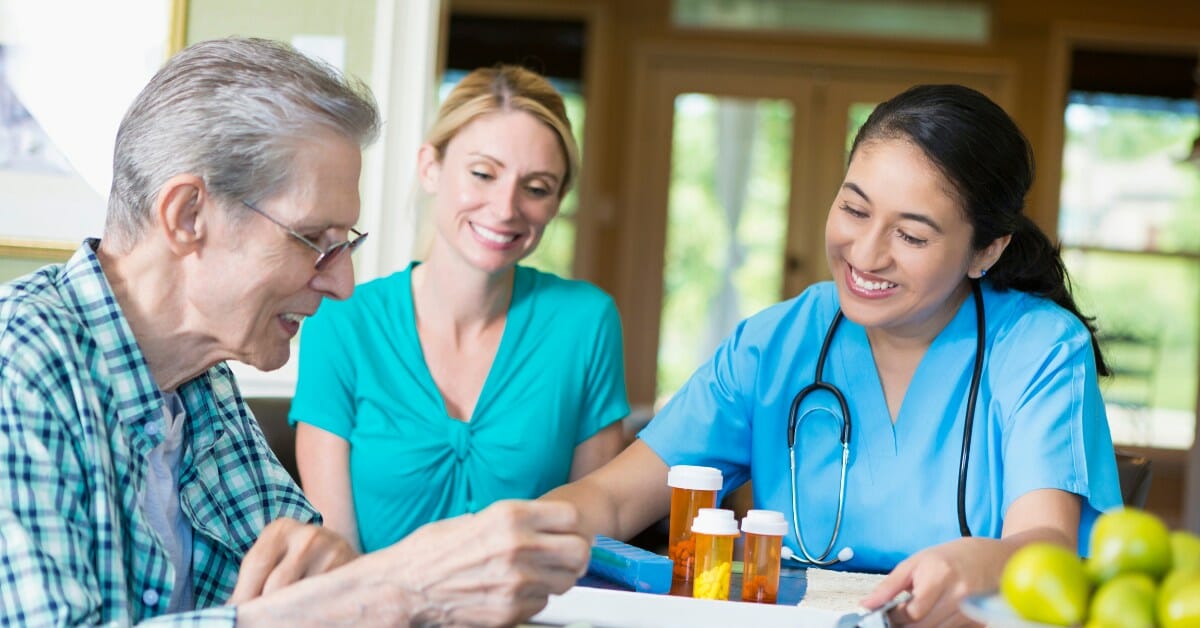
Successful agencies often differentiate themselves through specialized services, rigorous nurse vetting processes, exceptional client support, and transparent financial practices.
Pricing Strategies for Private Duty Nurses/Agencies
Effective pricing is crucial for both profitability and client acquisition. Strategies include:
-
Hourly Rates: The most common model, varying by nurse’s skill and care complexity.
-
Tiered Pricing: Offering different rates for RNs vs. LPNs, or for different levels of care.
-
Package Deals: Bundling services for long-term clients, such as a weekly number of hours at a slightly reduced rate.
-
Value-Based Pricing: Emphasizing the tangible benefits (reduced hospitalizations, improved health outcomes) that justify the cost.
-
Negotiation: Being open to discussing rates, especially for extended care, while ensuring the nurse’s professional value is maintained.
Transparency in pricing helps build trust with clients and avoids misunderstandings.
The Economic Impact on Healthcare
Private duty nursing plays a critical role in the broader healthcare economy. By providing personalized, high-level medical care in the home, it can:
-
Reduce Hospital Readmissions: Preventing acute exacerbations of chronic conditions and managing post-operative recovery effectively.
-
Decrease Healthcare Costs: By shifting care from more expensive institutional settings to the home.
-
Fill Gaps in Care: Addressing the needs of complex patients who might otherwise fall through the cracks of a fragmented system.
-
Support Caregivers: Alleviating the burden on family caregivers, allowing them to maintain employment and personal well-being, contributing indirectly to the economy.
Its growth signifies a broader trend towards home-based care models, driven by patient preference and economic efficiency.
Navigating the Financial and Regulatory Complexities
Operating within the private duty nursing sector requires a keen understanding of its specific financial and regulatory intricacies.
Contracts and Financial Agreements
Clear, comprehensive contracts are paramount for both clients and nurses/agencies. These documents should meticulously detail:
-
Scope of Services: Exact duties, medical interventions, and care plan.
-
Payment Terms: Hourly rates, billing cycles, payment methods, and late payment policies.
-
Cancellation Policies: Guidelines for rescheduling or terminating services.
-
Hours of Service: Agreed-upon schedule and provisions for changes.
-
Emergency Protocols: What happens in a medical emergency.
-
Confidentiality: Adherence to HIPAA and patient privacy.
Robust financial agreements protect both parties, setting clear expectations and mitigating potential disputes.
Tax Implications for Nurses and Agencies
The tax landscape for private duty nursing is complex.
-
Independent Contractors: Many private duty nurses operate as independent contractors, responsible for paying self-employment taxes (Social Security and Medicare), estimated quarterly taxes, and tracking all business expenses for deductions.
-
Agency Employees: Nurses employed by agencies typically have taxes withheld from their paychecks, and the agency handles payroll taxes.
-
Agencies: Agencies face employer payroll taxes, corporate income taxes, and potentially state-specific business taxes.
Understanding these distinctions is crucial for compliance and sound financial planning, often necessitating consultation with a tax professional.
Insurance and Liability (Financial Protection)
Adequate insurance is non-negotiable for both independent nurses and agencies:
-
Professional Liability Insurance (Malpractice Insurance): Protects nurses against claims of negligence or malpractice in their care.
-
General Liability Insurance: Covers risks associated with the business premises (if an agency) or incidents that might occur in the client’s home not directly related to medical care (e.g., property damage).
-
Workers’ Compensation: Agencies employing nurses are typically required to carry workers’ compensation insurance to cover employee injuries sustained on the job.
-
Cyber Liability Insurance: Increasingly important for agencies handling sensitive patient data.
These financial protections safeguard against significant financial losses stemming from unforeseen events or legal challenges.
Ethical Financial Practices
Maintaining ethical financial practices is fundamental to the integrity and sustainability of private duty nursing. This includes:
-
Transparency: Clearly communicating all costs, fees, and potential charges upfront.
-
Avoiding Conflicts of Interest: Ensuring that financial decisions are always in the best interest of the client, not driven by personal gain.
-
Fair Billing: Charging reasonable rates commensurate with the quality and complexity of care provided.
-
Confidentiality of Financial Information: Protecting clients’ financial details.
Ethical conduct builds trust, fosters long-term client relationships, and upholds the professional standing of private duty nursing.
The Future Financial Outlook of Private Duty Nursing
The trajectory for private duty nursing suggests continued growth, driven by demographic shifts, technological advancements, and evolving healthcare payment models, all of which have significant financial implications.
Demographic Shifts and Increasing Demand
The aging global population and the rising prevalence of chronic diseases are creating an unprecedented demand for home-based skilled nursing care. As individuals increasingly prefer to age in place, and as medical advancements allow for more complex care to be delivered outside of traditional institutions, the market for private duty nursing is set to expand significantly. This demographic imperative ensures a robust financial future for providers in this sector, as the need for specialized, personalized care intensifies.
Technological Integration (Financial Efficiencies)
While technology forms its own niche, its integration within private duty nursing has profound financial implications.
-
Scheduling and Billing Software: Streamlines administrative tasks, reduces human error, and optimizes staffing, leading to cost savings and improved revenue cycle management for agencies.
-
Telehealth and Remote Monitoring: Can enhance the efficiency of care delivery by allowing nurses to monitor clients remotely, potentially reducing the need for constant in-person visits for certain tasks, thereby managing costs while maintaining quality.
-
Electronic Health Records (EHRs): Improve documentation, reduce paperwork, and enhance communication, leading to greater efficiency and potentially better reimbursement accuracy.
These technological adoptions are not just about convenience; they are about achieving financial efficiencies and expanding service capabilities.
Evolving Payment Models and Policy Changes
The healthcare landscape is constantly shifting, with a move towards value-based care and alternative payment models. While private duty nursing is largely private-pay, future policy changes, particularly in long-term care insurance and certain government programs, could expand coverage or integrate home-based skilled nursing more directly into mainstream benefit structures. The financial future may see more innovative payment arrangements, such as bundled payments for specific episodes of care or greater integration with accountable care organizations (ACOs), opening new avenues for funding and reimbursement. Staying abreast of these changes will be critical for the financial viability and growth of private duty nursing practices and agencies.
In conclusion, “what is private duty nursing” is a question with a deeply financial answer. It is a sector driven by the direct exchange of highly skilled medical care for specific remuneration, funded by a mix of personal resources, specialized insurance, and targeted benefits. For clients, it’s an investment in quality of life and personalized health outcomes. For nurses and entrepreneurs, it’s a dynamic field offering significant income potential and business opportunities. Navigating its financial and regulatory complexities is key to success, as is anticipating its evolving future within the broader healthcare economy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.