
Understanding the true “worth” of a company like Nvidia goes far beyond merely looking at its current stock price. For investors, determining what Nvidia stock is truly worth involves a deep dive into its financial health, market position, technological dominance, growth prospects, and the broader economic landscape. As a bellwether for the artificial intelligence revolution and a titan in high-performance computing, Nvidia’s valuation is a complex, dynamic interplay of innovation and market expectations. This article will dissect these layers through a financial lens, strictly adhering to the “Money” category.
Understanding Nvidia’s Market Position and Valuation Drivers
Nvidia (NVDA) is not just a chipmaker; it’s an ecosystem provider that has strategically positioned itself at the nexus of several transformative technologies. Its market position is a primary driver of its valuation, reflecting its ability to generate substantial revenue and maintain high-profit margins.
Dominance in Core Markets
Nvidia’s foundational strength lies in its graphics processing units (GPUs). Initially designed for high-fidelity gaming, these GPUs have found an indispensable role in data centers for accelerating computationally intensive tasks, most notably artificial intelligence and machine learning workloads. This dual-use capability has cemented Nvidia’s leadership. In the gaming sector, Nvidia’s GeForce GPUs command a significant market share, driven by continuous innovation in graphics rendering, ray tracing, and AI-powered upscaling technologies like DLSS. However, it’s the data center segment that has propelled Nvidia into an unprecedented growth trajectory. Its A100 and H100 GPU accelerators are the de facto standard for training large language models (LLMs) and running complex AI algorithms, making Nvidia a critical infrastructure provider for cloud computing giants and enterprises globally. Beyond these, Nvidia is making significant inroads into professional visualization (Quadro GPUs), automotive (AI platforms for autonomous vehicles), and its metaverse-building platform, Omniverse, which hints at future growth vectors. This multi-pronged market dominance provides a robust foundation for its valuation.
Revenue Streams and Growth Vectors
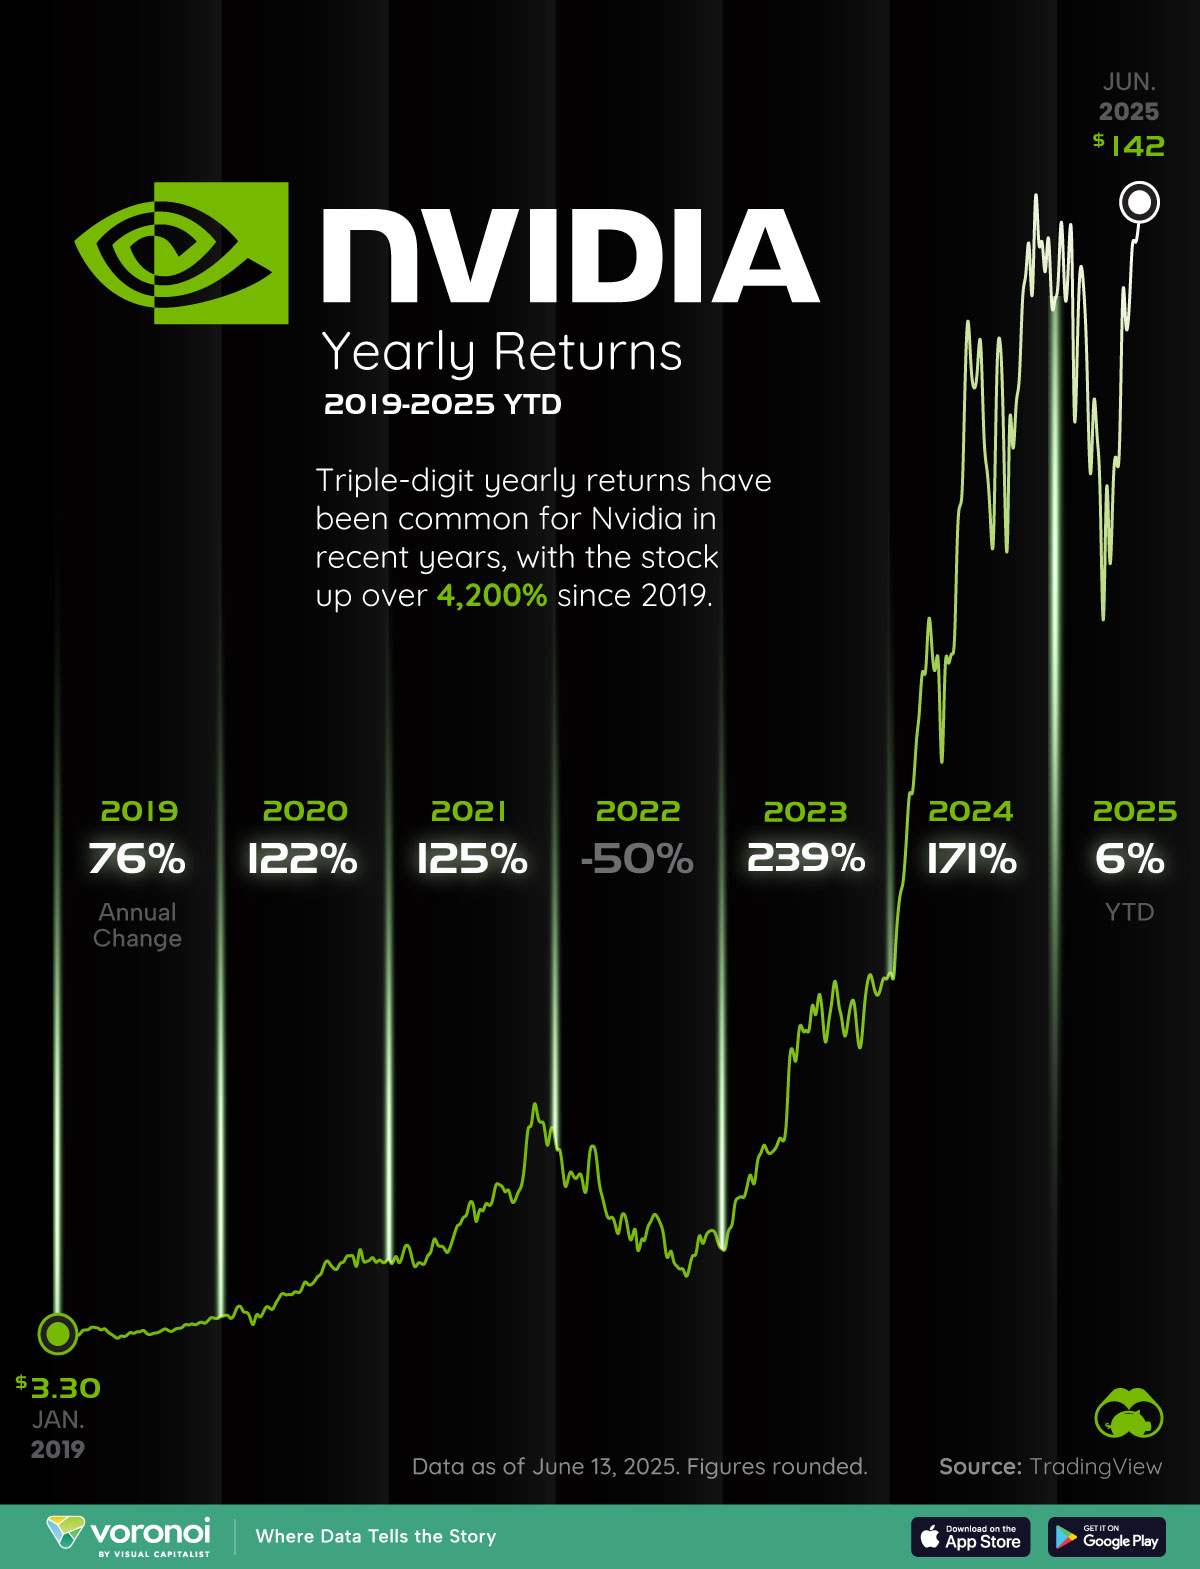
Nvidia’s financial worth is intrinsically tied to its diversified yet interconnected revenue streams. The Data Center segment has emerged as its most potent growth engine, consistently posting triple-digit percentage growth rates in recent periods. This growth is fueled by the insatiable demand for AI compute power from hyperscalers, enterprises building AI factories, and sovereign AI initiatives. The gaming segment, while more cyclical, provides a stable and substantial revenue base, benefiting from new product cycles and the enduring popularity of PC gaming. Crucially, Nvidia’s valuation isn’t solely based on hardware sales. Its comprehensive software platforms, such as CUDA (Compute Unified Device Architecture) and AI Enterprise, act as powerful multipliers. CUDA, in particular, is an unparalleled ecosystem that locks in developers and researchers, making it challenging for competitors to replicate. This full-stack approach – integrating hardware, software, and services – creates strong network effects and sticky customer relationships, allowing Nvidia to capture a larger share of the value chain and sustain premium pricing, which directly impacts its profitability and, consequently, its valuation.
Competitive Moats and Innovation Cycle
Nvidia’s “worth” is also protected by formidable competitive moats. Its technological superiority, born from decades of relentless research and development, is a primary barrier to entry. Nvidia consistently invests heavily in R&D, pushing the boundaries of chip design, packaging, and software optimization. This commitment results in new generations of GPUs that offer significant performance uplifts, justifying their premium cost. The CUDA ecosystem represents another powerful moat. With millions of developers trained in CUDA, and thousands of applications built upon it, the switching cost for customers to an alternative platform is exceedingly high. This ecosystem lock-in creates a powerful feedback loop: more developers build on CUDA, further entrenching Nvidia’s position. Furthermore, Nvidia operates on a consistent innovation cycle, regularly introducing new architectures and platforms that keep it ahead of competitors. This continuous innovation, coupled with strategic partnerships across various industries, ensures that Nvidia remains at the forefront of technological advancement, consistently delivering value that justifies its elevated market capitalization.
Key Financial Metrics for Valuing NVDA Stock
To ascertain what Nvidia stock is truly worth, investors must scrutinize a range of financial metrics that provide quantitative insights into its performance, efficiency, and future potential. These metrics are crucial for fundamental analysis and help in comparing Nvidia against its peers and historical performance.
Revenue and Earnings Growth
At the core of any growth stock’s valuation are its revenue and earnings growth rates. Nvidia has demonstrated exceptional growth, especially in its data center division, driven by the AI boom. Investors analyze historical growth trends to project future performance. High double-digit or even triple-digit quarterly and annual growth in revenue and earnings per share (EPS) signals a robust business with increasing demand for its products. However, it’s also important to consider the sustainability of such growth. Analysts often provide forward-looking estimates for revenue and EPS, which significantly influence investor sentiment and valuation models. It’s equally critical to understand the factors driving this growth—whether it’s market share gains, expansion into new markets, or the overall growth of its target industries. Furthermore, the cyclical nature of certain segments, such as gaming (influenced by console cycles and economic downturns) and crypto mining (which has historically provided unpredictable surges and collapses in demand for GPUs), can introduce volatility, making a smoothed average growth rate more indicative of underlying business health.
Profitability Margins
Profitability margins provide insight into how efficiently Nvidia converts revenue into profit. Key metrics include gross margin, operating margin, and net margin. Nvidia is renowned for its industry-leading gross margins, often exceeding 60%, which reflects its pricing power, technological differentiation, and efficient manufacturing processes. High gross margins indicate that the company sells highly valued products with significant markups over their cost of goods sold. Operating margin reveals the profitability of the core business operations after accounting for operating expenses like R&D, sales, and administrative costs. A strong operating margin demonstrates effective cost management and operational efficiency. Net margin, which represents the percentage of revenue left after all expenses, including taxes, is the ultimate measure of a company’s bottom-line profitability. Consistently high and stable (or improving) margins are a strong indicator of a financially healthy and well-managed company, directly contributing to its intrinsic worth by generating more earnings per share.
Valuation Multiples
Valuation multiples are comparative tools that assess a company’s worth relative to its financial performance. For Nvidia, as a high-growth technology stock, widely used multiples include:
-
Price-to-Earnings (P/E) Ratio: This measures the stock price relative to its annual earnings per share. A high P/E ratio, often seen in growth stocks like Nvidia, indicates that investors are willing to pay a premium for anticipated future earnings growth. It should be compared against industry peers and Nvidia’s historical average.
-
Price-to-Sales (P/S) Ratio: Useful for companies with fluctuating earnings or during high-growth phases where earnings might be temporarily depressed due to heavy reinvestment. It compares market capitalization to total revenue.
-
PEG Ratio (P/E to Growth): This refines the P/E ratio by factoring in earnings growth. A PEG ratio of 1.0 or less is often considered fair value for a growth stock. A high P/E accompanied by even higher growth could justify its valuation.
-
Enterprise Value to EBITDA (EV/EBITDA): This multiple considers the entire value of the company (market cap + debt – cash) relative to its earnings before interest, taxes, depreciation, and amortization, offering a more comprehensive view, especially for companies with significant debt or capital expenditures.
Analyzing these multiples in context—considering Nvidia’s growth trajectory, industry comparisons, and market sentiment—helps investors gauge whether the stock is undervalued, fairly valued, or overvalued at a given time.
Balance Sheet Strength and Cash Flow
A strong balance sheet and robust cash flow generation are critical for long-term sustainability and investor confidence. Investors look at Nvidia’s balance sheet for:
-
Cash Reserves: A substantial cash pile provides flexibility for R&D, acquisitions, and weathering economic downturns.
-
Debt Levels: Low debt-to-equity ratios indicate financial prudence and reduce risk.
-
Assets and Liabilities: A healthy balance sheet ensures the company has the resources to execute its strategy without excessive financial strain.
Free Cash Flow (FCF) is arguably one of the most important metrics, especially for high-growth, capital-intensive companies. FCF represents the cash a company generates after accounting for cash outflows to support its operations and maintain its capital assets. Strong and growing FCF allows Nvidia to reinvest in its business (capital expenditures, R&D), return capital to shareholders through share buybacks or dividends, and pursue strategic acquisitions. Consistent FCF generation underpins the intrinsic value of the company, as it represents the real cash available to stakeholders.
The Impact of Macro Trends and Competitive Landscape
Nvidia’s worth is not determined in a vacuum. It is profoundly influenced by broader macro-economic trends and the evolving competitive landscape within the technology sector. These external factors can significantly alter its growth trajectory and, consequently, its valuation multiples.
The Artificial Intelligence Revolution
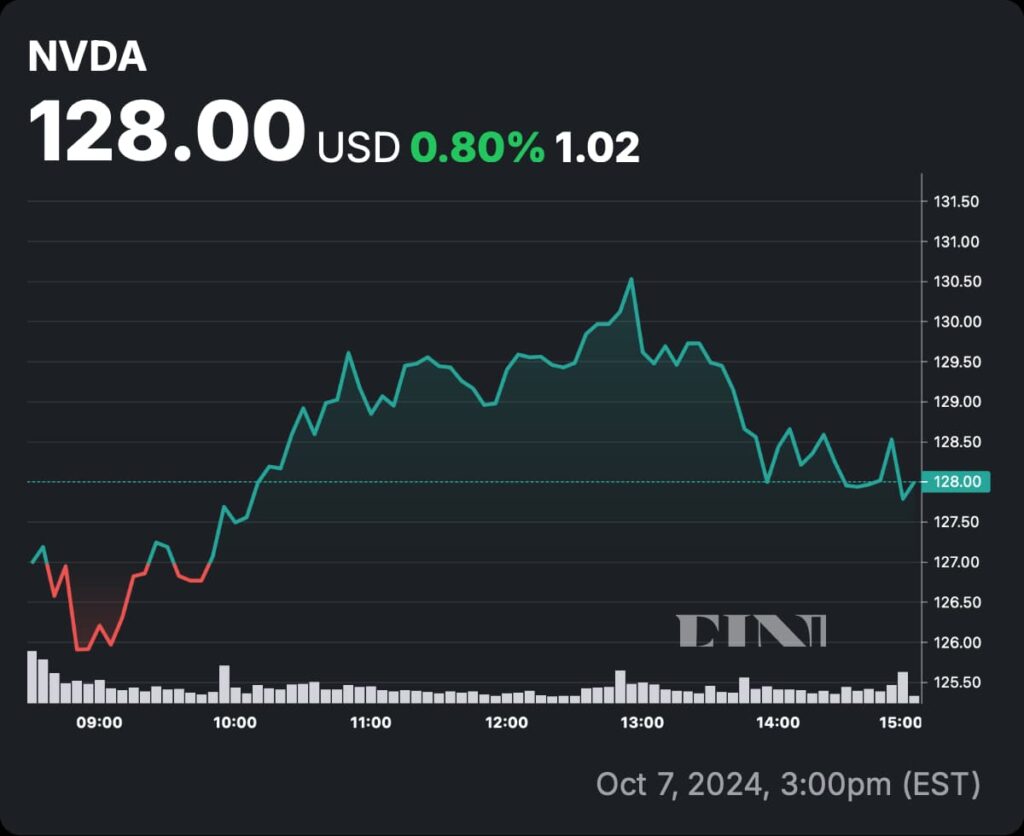
The single most significant macro trend impacting Nvidia’s valuation is the ongoing Artificial Intelligence (AI) revolution. Nvidia’s GPUs have become the foundational building blocks for training and deploying AI models, from large language models (LLMs) to advanced machine learning algorithms. The explosion of generative AI, exemplified by technologies like ChatGPT, has created unprecedented demand for Nvidia’s high-performance accelerators. This isn’t a transient trend; AI is poised to transform virtually every industry, ensuring a long-term structural growth driver for Nvidia. The company is positioned as a critical enabler of this transformation, meaning its “worth” is intrinsically linked to the continued expansion and deepening of AI adoption globally. As companies and nations race to build AI infrastructure, Nvidia’s hardware and software ecosystem become increasingly indispensable, solidifying its dominant position and justifying premium valuations.
Data Center Expansion and Cloud Adoption
Closely tied to the AI revolution is the continued expansion of data centers and the accelerating adoption of cloud computing. Hyperscale cloud providers like Amazon Web Services, Microsoft Azure, and Google Cloud are major customers for Nvidia, deploying vast fleets of its GPUs to power their AI services and general-purpose accelerated computing offerings. Enterprises are also increasingly building out their private AI infrastructure. This sustained demand for data center capacity, driven by the ever-increasing volume of data, complex computational needs, and the shift towards cloud-native architectures, provides a robust market for Nvidia’s products. The transition from traditional CPU-centric computing to GPU-accelerated computing in data centers is a fundamental shift, and Nvidia is at the forefront of this paradigm, ensuring a steady revenue stream and growth opportunities that underpin its valuation.
Geopolitical Factors and Supply Chain Resilience
Geopolitical factors, particularly trade tensions and intellectual property concerns, play a substantial role in assessing Nvidia’s worth. Export controls, particularly those imposed by the U.S. government on advanced AI chips to certain countries (like China), can impact Nvidia’s ability to sell its highest-performing products into significant markets. This introduces uncertainty and potential revenue limitations. Furthermore, the global semiconductor supply chain is complex and delicate. Dependencies on a few key foundries (like TSMC) for manufacturing can expose Nvidia to supply disruptions, capacity constraints, and rising production costs. Investors evaluate Nvidia’s supply chain resilience, its ability to navigate these geopolitical headwinds, and its strategic measures to diversify or secure production capacity. These factors directly influence revenue stability, profitability, and long-term growth forecasts.
Competitive Dynamics
While Nvidia holds a commanding lead, the competitive landscape is constantly evolving. Rival chipmakers like Advanced Micro Devices (AMD) are investing heavily in their own GPU lines, aiming to challenge Nvidia’s dominance in both gaming and data center markets with products like their Instinct MI series. Intel, historically a CPU powerhouse, is also making efforts in the discrete GPU space (Arc series) and specialized AI accelerators (Gaudi). Furthermore, some hyperscale cloud providers are developing their own custom AI chips (e.g., Google’s TPUs, AWS Trainium/Inferentia) to reduce reliance on third-party suppliers and optimize for their specific workloads. While these custom chips primarily target internal use, they represent a potential long-term threat to Nvidia’s market share in specific segments. Investors must assess Nvidia’s ability to maintain its technological lead, innovate faster, and defend its ecosystem against these formidable competitors to justify its high valuation. The strength of its competitive moat against these players directly contributes to its perceived long-term worth.
Investment Considerations and Future Outlook for NVDA
For potential investors, understanding “what Nvidia stock is worth” means synthesizing all the aforementioned financial and market factors into a coherent investment thesis. This involves weighing growth prospects against current valuation, considering both potential upsides and downsides.
Growth vs. Value Investment Perspective
Nvidia is predominantly viewed as a high-growth stock, often trading at premium valuation multiples compared to the broader market or even its industry peers. This premium is justified by its exceptional revenue and earnings growth rates, its leading position in transformative technologies like AI, and its strong competitive moats. Growth investors are typically willing to pay a higher price for a stock today in anticipation of significantly higher earnings in the future. However, this also means that Nvidia can be more susceptible to market corrections, as high P/E ratios leave less room for error. A slight slowdown in growth or a shift in market sentiment can lead to significant valuation compression. Value investors, conversely, might find Nvidia’s current valuation challenging, as their focus is often on stocks trading below their intrinsic value based on current assets and earnings. For Nvidia, the investment consideration leans heavily towards a growth-oriented approach, requiring a belief in its long-term technological leadership and market expansion.
Analyst Sentiment and Price Targets
Wall Street analyst sentiment plays a significant role in short-to-medium-term stock movements and can influence investor perception of a stock’s worth. A consensus of “Buy” or “Strong Buy” ratings, accompanied by rising price targets, often signals confidence in the company’s future prospects. Analysts employ various valuation methodologies, including discounted cash flow (DCF) analysis, comparative analysis (using P/E, P/S, EV/EBITDA multiples), and sum-of-the-parts analysis, to arrive at their price targets. These targets are often based on projected revenue growth, margin expansion, and anticipated market share. However, investors should use analyst reports as one input among many, understanding that price targets can be subject to market volatility, changes in economic conditions, and shifts in company performance. It’s crucial to look beyond the headline rating and understand the underlying assumptions and risks articulated in their research.
Potential Headwinds and Tailwinds
The future outlook for Nvidia is shaped by a balance of potential headwinds and tailwinds:
-
Headwinds: These include intensified competition (from AMD, Intel, and custom silicon developers), regulatory scrutiny (especially regarding market dominance or cross-border trade), demand volatility (e.g., gaming market fluctuations, enterprise spending slowdowns), and the risk of valuation compression if growth rates normalize or if there’s a broader market downturn affecting high-multiple stocks. Supply chain issues and geopolitical tensions also remain persistent risks.
-
Tailwinds: These are largely driven by the continued acceleration of AI adoption across all industries, expansion into new lucrative verticals (such as robotics, autonomous driving, digital twins/metaverse via Omniverse), sustained demand from cloud computing, and Nvidia’s consistent ability to innovate and expand its software ecosystem (CUDA, AI Enterprise). The long-term structural demand for accelerated computing and sophisticated AI infrastructure positions Nvidia favorably.
A comprehensive investment assessment involves carefully weighing the probability and impact of these opposing forces on Nvidia’s future financial performance.
Long-Term Vision and Strategic Positioning
Nvidia’s long-term worth is heavily influenced by the strategic vision of its leadership, particularly CEO Jensen Huang. The company’s consistent focus on delivering full-stack computing solutions—integrating hardware, software, and services—is a critical differentiator. This strategy aims to create powerful, vertically integrated platforms that are more than just individual chips. By investing heavily in software platforms like CUDA, and by expanding into new, high-growth areas like industrial metaverse (Omniverse) and robotics, Nvidia is positioning itself not just as a component supplier but as a foundational technology partner for the next generation of computing. This strategic foresight and execution capability enhance its perceived long-term value, as it suggests resilience and adaptability in a rapidly changing technological landscape. Investors are betting on this long-term vision to continue translating into market leadership and superior financial returns.
Concluding Thoughts on Valuing Nvidia
Nvidia’s journey from a niche graphics card manufacturer to an AI powerhouse underscores a profound transformation that makes its valuation a dynamic and multifaceted challenge. “What is Nvidia stock worth?” is a question whose answer is constantly evolving, reflecting both the company’s relentless innovation and the volatile global markets it operates within.
Dynamic Valuation in a High-Growth Sector
Nvidia operates at the cutting edge of technology, in a sector characterized by exponential growth and rapid technological obsolescence. Its worth is not static; it is a live calculation that factors in present financial performance, but crucially, heavily weights anticipated future growth in AI, data centers, and emerging technologies. This dynamic nature means that Nvidia’s stock price often anticipates future earnings and breakthroughs, leading to periods of high valuation multiples. Investors must appreciate that the “worth” reflects a complex interplay of current financial strength, market execution against formidable competitors, and the broader macroeconomic currents shaping demand for its groundbreaking products and platforms. It’s a valuation deeply rooted in potential and future innovation as much as proven track record.

The Investor’s Due Diligence
Ultimately, determining the “worth” of Nvidia stock, and whether it aligns with an individual’s investment goals, requires meticulous due diligence. It necessitates a thorough understanding of the company’s financial statements, a critical assessment of its market leadership and competitive threats, and an informed perspective on the macro trends (like AI adoption and geopolitical influences) that will shape its future. It also demands a realistic evaluation of one’s own risk tolerance, given the inherent volatility associated with high-growth technology stocks. Engaging with financial advisors and conducting independent research are indispensable steps for any investor considering an allocation to Nvidia. While Nvidia’s innovation and market position are undeniable, the ultimate measure of its worth lies in its ability to consistently translate these strengths into sustainable financial returns for its shareholders over the long term.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.