
For most individuals, a vehicle represents one of the most significant line items on a personal balance sheet, second only to real estate. However, unlike a home, which typically appreciates over time, a car is a depreciating asset. Understanding exactly what your car is worth to sell is not merely a matter of curiosity; it is a critical exercise in capital management. Whether you are looking to liquidate the asset to bolster your investment portfolio, clear high-interest debt, or roll the equity into a more efficient vehicle, a precise valuation is the cornerstone of a successful financial transaction.
Navigating the used car market requires a blend of data analysis, timing, and an understanding of macroeconomic trends. By treating your vehicle as a financial instrument rather than just a mode of transportation, you can maximize your return and ensure that you are leaving no money on the table.
Understanding the Financial Fundamentals of Vehicle Valuation
Before checking online appraisal tools, it is vital to understand the underlying economic principles that dictate your car’s current market value. In the realm of personal finance, a car is characterized by its residual value—the estimated value of the asset at the end of a specific period or mileage interval.
Depreciation Curves and Market Timing
Depreciation is the largest hidden cost of vehicle ownership. Typically, a new car loses approximately 20% of its value in the first year and continues to depreciate at a rate of 10% to 15% annually until it hits a “value floor.” Understanding where your vehicle sits on this curve is essential. If your car is three to five years old, it has likely survived its steepest drop in value, making it a prime asset for resale.
Furthermore, market timing can significantly impact your “Money” outcome. During periods of high inflation or supply chain disruptions in the new car sector, used car prices often skyrocket. Conversely, when interest rates rise, the cost of financing a used vehicle increases, which can dampen demand and lower the price a private buyer or dealer is willing to pay. Monitoring the Federal Reserve’s movements and the consumer price index (CPI) can actually provide clues as to the best month to list your vehicle for sale.
The Role of Supply and Demand in Used Car Pricing
Value is fundamentally driven by scarcity and utility. A fuel-efficient hybrid may see its valuation surge when gasoline prices are high, while a luxury SUV might hold its value better in a robust economy where discretionary spending is high. When asking “what is my car worth,” you must look beyond the make and model and evaluate the local market. A four-wheel-drive truck carries a higher premium in mountainous or rural regions than it does in a dense urban center. By identifying the specific demographic that finds your vehicle most useful, you can target your sale to capture the highest possible price.
Essential Tools and Methods for Precise Appraisal
In the digital age, a “ballpark figure” is no longer sufficient for serious financial planning. You need hard data to back up your asking price and to negotiate effectively with professional buyers.
Digital Valuation Platforms vs. Physical Appraisals
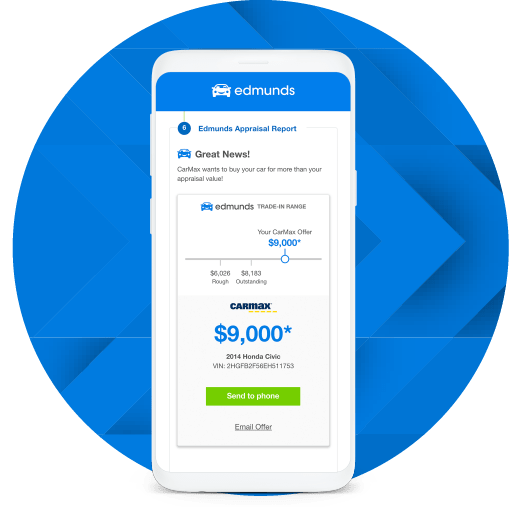
There are several industry-standard tools used to calculate vehicle equity. Platforms like Kelley Blue Book (KBB), Edmunds, and NADA Guides utilize vast databases of historical sales data to provide a range of values. When using these tools, it is imperative to be brutally honest about the condition of the vehicle. Most owners mistakenly categorize their cars as “Excellent,” whereas the financial reality is that very few used cars meet this rigorous criteria. Categorizing your car as “Good” or “Fair” provides a more realistic baseline for your financial projections.
For a more concrete figure, obtaining a “buy-bid” from a national car retailer can serve as a guaranteed floor for your valuation. These companies provide a written offer that is valid for a set number of days, giving you a risk-free benchmark. If a private buyer offers you less than this bid, the transaction makes no financial sense.
Decoding the Difference Between Trade-In and Private Party Value
One of the most common mistakes in personal finance is confusing trade-in value with private party value.
-
Trade-In Value: This is the price a dealership will pay you. It is essentially a wholesale price. The dealer must factor in their overhead, the cost of reconditioning, and their desired profit margin when they eventually resell the car.
-
Private Party Value: This is the price you can expect when selling to an individual. It is almost always higher than the trade-in value—often by 15% to 25%—because you are capturing the “retail” margin for yourself.
From a wealth-building perspective, selling privately is usually the superior choice, provided you have the time to manage the logistics. However, one must also consider the “tax shield” offered by trade-ins in many jurisdictions. If your state allows you to subtract your trade-in value from the purchase price of your next car before calculating sales tax, the 7% to 9% tax savings might bridge the gap between the trade-in and private sale price.
Key Factors That Influence Your Car’s Market Liquidity
Liquidity refers to how quickly an asset can be converted into cash without a significant loss in value. In the automotive market, certain factors act as multipliers or detractors for your car’s worth.
Mileage and Condition: The Primary Value Drivers
In the financial world, mileage is the odometer of an asset’s remaining life. There are psychological “cliffs” at 36,000, 60,000, and 100,000 miles. Crossing these thresholds often triggers a significant drop in valuation because they often coincide with the expiration of manufacturer warranties or the requirement for major scheduled maintenance (like timing belt replacements).
Condition is equally vital. A vehicle with interior odors, stained upholstery, or neglected paint requires the next owner to invest capital to restore it. To maximize your “worth to sell,” you should perform a cost-benefit analysis on minor repairs. Spending $200 on a professional detail might add $600 to the final sale price—a 200% return on investment that is hard to find in the stock market.
Documentation and Maintenance Records as Value Multipliers
Transparency reduces risk for the buyer, and in finance, lower risk commands a higher price. A vehicle with a comprehensive folder of maintenance receipts is worth more than an identical vehicle with no history. These records prove that the asset has been maintained, reducing the likelihood of catastrophic failure for the buyer. If you have been diligent with your record-keeping, you are effectively selling “peace of mind,” which is a premium commodity in the used car market.
Strategic Selling: How to Optimize Your Return on Investment
Once you have established the value, the next step is the execution of the sale. This is where your marketing strategy and negotiation skills come into play to protect your equity.
Preparing the Asset for Sale: Cost-Benefit Analysis
Treat the preparation of your car like a “flip” in real estate. Focus on high-impact, low-cost improvements.
-
Mechanical Transparency: If the car has a known issue, get a quote for the repair. You can then choose to fix it or disclose it and deduct the cost from your asking price. This builds trust and prevents the deal from falling through during a pre-purchase inspection.
-
Curb Appeal: First impressions dictate the emotional anchor of the negotiation. A clean car suggests a disciplined owner, which translates to a well-maintained machine in the mind of the buyer.
Choosing the Right Sales Channel for Your Financial Goals
The “best” way to sell depends on your liquidity needs:
-
Instant Cash Offers: Best for those who need immediate liquidity to cover a debt or a time-sensitive investment opportunity.
-
Consignment: Good for high-value or specialty vehicles where a professional can negotiate a higher price on your behalf for a percentage fee.
-
Private Listings: Best for maximizing the total dollar amount returned to your pocket. Utilizing platforms like Facebook Marketplace or specialized automotive forums allows you to bypass the middleman entirely.
Post-Sale Financial Management: Reinvesting Your Equity
The transaction isn’t over when the keys are handed over; it ends when the proceeds are effectively integrated into your broader financial plan.
Tax Implications and Capital Gains Considerations
In most cases, selling a personal vehicle does not result in a taxable event because you are selling the asset for less than you originally paid (a capital loss). Since personal losses are generally not tax-deductible, there is no direct tax benefit. However, if you are selling a classic or collector car that has appreciated in value, you may be liable for capital gains tax. Consult with a tax professional to ensure you are reporting the sale correctly and to see if there are ways to offset these gains.
Strategic Reallocation of Vehicle Proceeds
What you do with the cash from the sale can have a long-term impact on your net worth.
-
Debt Elimination: If you have high-interest credit card debt, using car sale proceeds to pay it down offers a guaranteed “return” equal to the interest rate you were paying.
-
Emergency Fund: If your liquidity is low, placing the funds into a High-Yield Savings Account (HYSA) provides a safety net that prevents future high-interest borrowing.
-
Market Investment: If the car was an extra asset, moving that money into a low-cost index fund allows a previously depreciating asset to begin generating compound interest.
-
Down Payment Optimization: If you are replacing the vehicle, using the equity to minimize the loan amount on your next car reduces your monthly “burn rate” and saves thousands in interest over the life of the new loan.
By meticulously answering the question “what is my car worth to sell” through a financial lens, you transform a routine transaction into a strategic wealth-management move. Every dollar saved in negotiation or gained through proper market timing is a dollar that can be put to work in more productive areas of your financial life.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.