
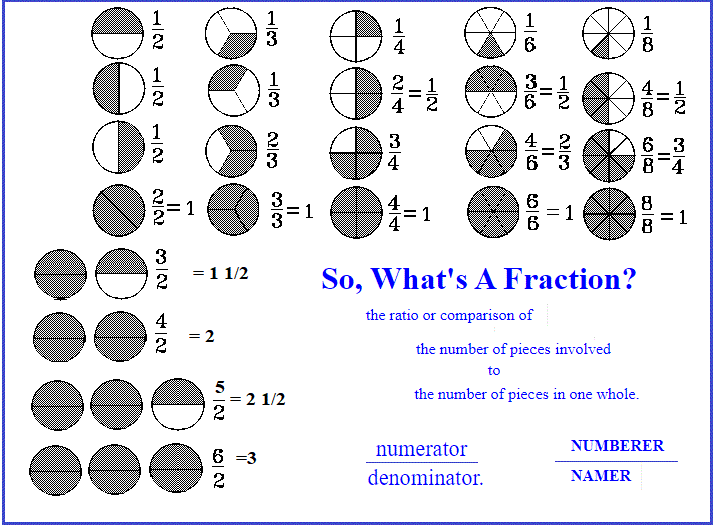
The question “what is half of 1/4 in a fraction?” might seem like a simple arithmetic problem from a grade school textbook. The answer, straightforwardly, is 1/8. However, beneath the surface of this seemingly basic query lies a profound truth: a solid understanding of fundamental mathematical concepts, particularly fractions, is not just academic — it is an indispensable cornerstone for robust financial literacy and effective money management.
In the complex world of personal finance, investing, and business, numbers tell a story. They dictate our budgets, shape our investment returns, define our debts, and measure our wealth. Without a firm grasp of how these numbers, often expressed as fractions or percentages, interact, individuals are left navigating a critical aspect of life with a significant handicap. This article delves into why mastering concepts like “half of 1/4” is far more than a mathematical exercise; it’s a vital step towards financial empowerment, savvy investing, and sustainable wealth creation.
The Foundational Role of Fractions in Personal Finance
Every decision involving money, from buying groceries to planning for retirement, implicitly or explicitly involves mathematical operations. Fractions, in particular, provide a framework for understanding proportions, divisions, and shares – concepts central to managing personal finances effectively.
Budgeting and Allocating Funds
At the heart of personal finance is budgeting – the meticulous allocation of income across various categories like savings, expenses, debt repayment, and discretionary spending. Fractions are inherently embedded in this process. For instance, common budgeting rules like the 50/30/20 rule (50% for needs, 30% for wants, 20% for savings and debt repayment) are direct applications of fractional thinking. If you earn $4,000 per month, understanding that 1/4 (or 25%) goes to rent means you can quickly calculate $1,000. If your goal is to save 1/10 of your income, you need to confidently calculate that amount. Misunderstanding how to divide your income into fractional parts can lead to overspending, insufficient savings, and a perpetual struggle to meet financial goals. The ability to calculate what is half of a quarter of your income, for example, directly translates to the precision needed when dividing a bonus or unexpected windfall.
Understanding Discounts and Sales
The retail world constantly employs fractions and percentages to entice consumers. “50% off!” “Buy One Get One Half Price!” “Save 1/3 on your next purchase!” These are not just marketing slogans; they are mathematical statements that require interpretation. To make informed purchasing decisions and truly understand the value proposition, one must be able to calculate these discounts accurately. If an item is $100 and it’s 1/4 off, understanding that you save $25 (1/4 of $100) is crucial. If the offer is “half of the original price,” you need to know how to calculate that. Without this basic fractional fluency, consumers risk miscalculating actual savings, leading to either missed opportunities or the perception of a deal that isn’t as good as it seems.
Debt Management and Interest Rates
Debt, whether in the form of credit cards, mortgages, or student loans, is a significant part of many individuals’ financial landscape. Interest rates, often expressed as percentages, are essentially fractions of the principal amount owed. Understanding how interest accrues, how minimum payments are calculated, and how early repayments can save money, all hinge on fractional understanding. A 10% interest rate means you pay 1/10 of the principal annually in interest, ignoring compounding for simplicity. Knowing that “half of 1/4” means 1/8 allows you to conceptualize how an interest rate might be split over different periods or how a fractional reduction in your interest rate can impact your total payments over time. This foundational math empowers individuals to make strategic decisions about borrowing, identify predatory lending, and effectively plan their debt repayment strategies.
Fractions in the World of Investing and Business
Moving beyond daily personal finance, fractions become even more critical in the realms of investing and business, where proportional ownership, returns, and distributions are fundamental concepts.
Stock Ownership and Dividends
When you buy a share of stock, you own a fraction of a company. Companies often distribute a portion of their profits to shareholders in the form of dividends, which are usually expressed as a certain amount per share or a fraction of the stock’s price (dividend yield). Understanding that if a company has 100 million shares outstanding and you own 1 million, you own 1/100 of the company, is basic fractional logic. Calculating dividend yields, understanding stock splits (e.g., a 2-for-1 split means you get two shares for every one you owned, effectively doubling your fractional ownership with a reduced per-share price), and comprehending how your fractional ownership translates to voting rights or profit sharing are all applications of fraction mastery.
Investment Returns and Portfolio Allocation

Investors regularly evaluate the performance of their investments. Calculating returns as a percentage (which is a fraction out of 100) or a fraction of the original investment is standard practice. If an investment of $1,000 grows to $1,250, the gain is $250, representing 1/4 of the original investment. This understanding allows for clear comparison across different investment vehicles. Furthermore, portfolio allocation involves deciding what fraction of your total investment capital to dedicate to different asset classes—stocks, bonds, real estate, etc. A common strategy might be to allocate “half of your portfolio to stocks and a quarter to bonds,” which immediately becomes “1/2 to stocks and 1/4 to bonds.” The remaining “1/4” could be allocated to other assets, or “half of that remaining quarter” (which is 1/8) could go to a specific alternative investment. These decisions are inherently fractional and crucial for diversification and risk management.
Business Ownership and Profit Sharing
In business partnerships or ventures, ownership stakes are almost always expressed as fractions or percentages. If two partners start a business and agree to a 50/50 split, they each own 1/2. If a third partner joins and they decide to split the remaining portion evenly, they might then own 1/3 each (or if the original partners retain 1/2 combined, then the third takes a fraction of that, e.g., if one partner gives up 1/4 of their share to the new partner, that’s “1/4 of 1/2” or 1/8). Profit sharing follows the same fractional logic. Accurate calculation of these fractions is vital for equitable distribution of profits, liabilities, and decision-making power. A simple miscalculation, like misunderstanding what half of a quarter share represents, could lead to significant financial disputes and inequities in a business context.
Overcoming “Math Phobia” for Financial Empowerment
Many individuals harbor a long-standing aversion to mathematics, often stemming from negative experiences in early education. This “math phobia” can be a significant barrier to achieving financial literacy and independence. However, understanding that financial math is rarely abstract and almost always practical can help bridge this gap.
Practical Application over Abstract Theory
The key to overcoming math phobia in a financial context is to shift the focus from abstract equations to real-world applications. Instead of pondering “what is half of 1/4” as an isolated problem, frame it within scenarios: “If I have 1/4 of a pie, and I give half of that to my friend, how much does my friend get?” or “If I allocate 1/4 of my income to savings, and then decide to move half of that amount into a specific investment, what fraction of my income is now in that investment?” By contextualizing these problems within personal finance narratives, the relevance and utility of the math become immediately apparent, making it less intimidating and more engaging. This approach transforms seemingly complex calculations into tangible steps toward achieving financial goals.
Leveraging Financial Tools and Technology (Responsibly)
Today, countless apps, software programs, and online calculators simplify complex financial calculations. While these tools are invaluable for efficiency and accuracy, they should complement, not replace, a foundational understanding of the underlying math. Relying solely on technology without comprehending the principles can lead to blindly accepting potentially flawed calculations or misinterpreting results. For example, a budget app might show you how much you’ve spent, but understanding why that number is concerning (e.g., it represents a disproportionately large fraction of your income for a particular category) requires fractional thinking. Knowing what half of a quarter is, even if a calculator tells you it’s 0.125, gives you a conceptual understanding that empowers you to critically evaluate the outputs of financial tools and ensure they align with your financial objectives.
Beyond the Basics: Advanced Financial Concepts Rooted in Fractions
The importance of fractional understanding extends into more sophisticated financial concepts, underpinning models and strategies used by seasoned investors and financial professionals.
Compound Interest and Growth Rates
Compound interest, often hailed as the “eighth wonder of the world,” relies heavily on the concept of fractional growth. It’s not just about earning interest on your initial principal but also on the accumulated interest. The growth rate, expressed as a percentage (a fraction), is applied iteratively. Understanding how a small fraction of growth, compounded over many periods, can lead to substantial wealth accumulation requires a deep appreciation for exponential functions, which are fundamentally built upon repeated fractional multiplication. Visualizing how “half of 1/4” of growth on an investment, compounded over time, can contribute to significant long-term returns, is a powerful motivator for early and consistent investing.

Risk Assessment and Diversification Ratios
In investment management, assessing risk often involves calculating ratios and proportions. Diversification strategies dictate how different asset classes should be weighted within a portfolio to mitigate risk. For instance, value-at-risk (VaR) models quantify potential losses as a fraction of total portfolio value. Understanding concepts like beta (a measure of a stock’s volatility relative to the overall market) involves fractional comparisons of price movements. These advanced metrics, while complex, are fundamentally rooted in the proportional thinking that fractions instill. The ability to break down a total risk into fractional components, and then to reallocate these fractions to optimize risk-adjusted returns, is a hallmark of sophisticated financial planning.
In conclusion, the seemingly simple question “what is half of 1/4 in a fraction?” serves as a potent reminder of the critical role of basic mathematics in our financial lives. From everyday budgeting and understanding discounts to complex investment strategies and business ownership, fractional thinking is an indispensable skill. It empowers individuals to make informed decisions, avoid common financial pitfalls, and ultimately achieve greater financial independence and prosperity. Embracing and mastering these foundational mathematical concepts is not merely an academic pursuit; it is a fundamental step toward building a secure and flourishing financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.