
The act of selling a house is rarely a singular event; rather, it is a multifaceted financial maneuver that carries different titles depending on your role in the transaction, your professional licensure, and your underlying investment strategy. For some, selling a house is a career path defined by commissions and brokerage; for others, it is a high-stakes investment vehicle designed to generate rapid capital gains or long-term wealth.
Understanding the nomenclature of selling property is the first step in navigating the complex landscape of real estate finance. Whether you are looking to earn a side income, launch a full-scale business, or optimize your personal portfolio, identifying the specific “what” and “how” of the selling process is essential for financial success.
The Professional Path: Real Estate Agency and Brokerage
When most people ask what it is called when you sell houses, they are referring to the professional role of a Real Estate Agent or Broker. This is a service-based business model where the primary product is expertise, negotiation skills, and access to the Multiple Listing Service (MLS).
Earning Commissions and the Fee Structure
In the world of professional agency, you aren’t selling a house you own; you are facilitating the sale of an asset owned by a client. This is called “listing” a property. The financial reward for this service is the commission. Typically, a commission represents a percentage of the total sale price—often ranging between 5% and 6% in the United States, which is then split between the listing agent’s brokerage and the buyer’s agent’s brokerage.
From a business finance perspective, being an agent is a high-margin, low-overhead endeavor, provided the agent can maintain a consistent pipeline of leads. However, it is important to distinguish between a Real Estate Agent and a Realtor®. While the terms are used interchangeably, a Realtor® is a member of the National Association of Realtors (NAR) and adheres to a specific code of ethics. Financially, the “sale” for an agent is the closing of the deal, which triggers the payout of the commission.
The Brokerage Model and Residual Income
As professionals advance, they often transition from being an agent to becoming a Real Estate Broker. Selling houses as a broker involves a different financial tier. A broker can own a firm and oversee other agents. In this scenario, “selling houses” becomes a form of passive or semi-passive income through “brokerage splits.” The broker takes a portion of every commission earned by the agents under their supervision. This shifts the focus from individual sales to corporate scaling and brand management.
House Flipping: The Capital Gains Strategy
If you are buying properties with the intent to renovate and resell them for a profit, the practice is called “House Flipping.” This is a sophisticated form of real estate investing that relies on the principle of “forced appreciation.”
Understanding Forced Appreciation
Unlike a standard homeowner who waits for the market to rise (organic appreciation), a flipper actively increases the value of the asset through strategic capital improvements. The financial goal is to purchase a distressed or undervalued property, invest a specific amount in renovations, and sell the property at a price point that covers the purchase price, the renovation costs, the holding costs (taxes, insurance, interest), and the selling costs, while still leaving a significant net profit.
In the realm of personal finance, flipping is considered a high-risk, high-reward “active” investment. It requires a deep understanding of After Repair Value (ARV). Investors often use the “70% Rule,” which suggests that an investor should pay no more than 70% of the ARV of a property, minus the estimated cost of repairs. This provides a financial buffer to ensure the “sale” results in a gain rather than a loss.
Risk Mitigation and Carrying Costs
A critical financial aspect of flipping houses is the management of carrying costs. Every day a house sits on the market without being sold, it costs the investor money in the form of loan interest, utilities, and opportunity cost. Professionals in this niche focus heavily on “days on market” (DOM) as a key performance indicator. The faster the sale, the higher the annualized Return on Investment (ROI).
Wholesaling: The Art of Contract Assignment
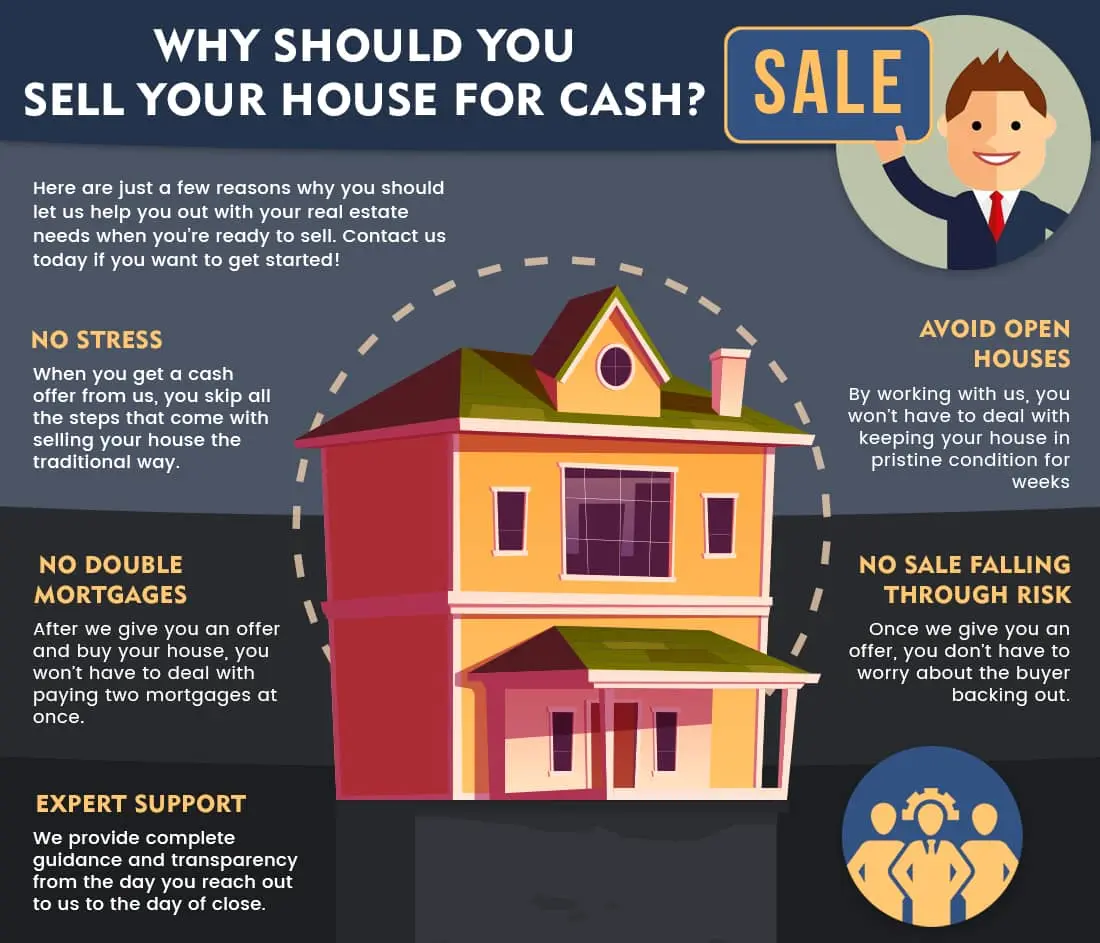
For those who want to sell houses without actually owning them or having a real estate license, the practice is known as “Wholesaling.” This is often described as the “entry-level” strategy for real estate entrepreneurs because it requires very little capital.
Generating Cash Flow with Minimal Capital
In a wholesale transaction, the wholesaler finds a motivated seller (usually someone with a distressed property or a need for a quick exit) and puts the house under contract. However, instead of buying the house themselves, the wholesaler “assigns” that contract to an end buyer—typically a house flipper or a long-term landlord—for an “assignment fee.”
From a financial standpoint, the wholesaler is selling the equitable interest in a legal contract rather than the physical bricks and mortar. The fee is usually a spread between the price negotiated with the seller and the price paid by the investor. For example, if a wholesaler secures a contract for $200,000 and finds an investor willing to pay $215,000, the wholesaler earns a $15,000 assignment fee at closing.
The Role of the Equitable Interest
Wholesaling is a pure volume play. Because the wholesaler does not take title to the property (in most cases), they avoid the costs associated with renovations, property taxes, and mortgage interest. The “sale” here is the transfer of rights. It is a business finance model built on lead generation, marketing, and negotiation rather than asset management.
Real Estate Development and Speculative Building
At the highest end of the “selling houses” spectrum is Real Estate Development. This involves purchasing raw land, obtaining the necessary entitlements (zoning and permits), and constructing new homes to sell to the public.
Scaling from Residential to Commercial
Developers operate on a much larger financial scale than flippers or wholesalers. They must manage construction loans, architectural designs, and municipal bureaucracy. When a developer sells a house, they are selling a “new build.” This niche is highly sensitive to interest rates and macroeconomic trends. When rates are low, developers can move inventory quickly; when rates rise, the “sale” becomes more difficult as buyer affordability shrinks.
Speculative vs. Custom Building
There are two primary financial models in this category:
- Speculative (Spec) Building: The developer builds a house without a specific buyer in mind, betting that the market will support the price point upon completion.
- Custom Building: The developer (often acting as a general contractor) builds a specific home for a client who already owns the land or has secured a construction-to-permanent loan.
In speculative building, the developer bears all the financial risk but stands to gain the highest profit margins. In custom building, the developer earns a “builder’s fee,” which is a more predictable, lower-risk revenue stream.
Navigating the Financial Lifecycle of a Sale
Regardless of what you call the act of selling houses, the financial implications are governed by the same set of economic principles. Understanding these factors is what separates a casual seller from a sophisticated financial actor.
Tax Implications and Capital Gains
When you sell a house for more than you paid for it, the profit is generally considered a capital gain. In the United States, the tax treatment of this gain depends on how long you held the asset.
- Short-term Capital Gains: If you held the property for less than a year (common in flipping and wholesaling), the profits are taxed as ordinary income, which can be as high as 37%.
- Long-term Capital Gains: If you held the property for more than a year, you qualify for lower tax rates (0%, 15%, or 20%), which is a primary reason why many investors transition from flipping to “buy and hold” strategies.
For primary residences, homeowners can often exclude up to $250,000 (single) or $500,000 (married filing jointly) of gain from their income, provided they meet residency requirements. This “sale” is one of the most powerful tax-advantaged wealth-building events available to the average person.
Leveraging the 1031 Exchange for Wealth Preservation
For professional investors, “selling a house” is often just a transition into a larger asset through a 1031 Exchange. Named after Section 1031 of the Internal Revenue Code, this allows an investor to defer paying capital gains taxes on the sale of an investment property if they reinvest the proceeds into a “like-kind” property of equal or greater value.
This strategy is the engine behind massive real estate empires. By continually selling smaller houses and buying larger multi-family units or commercial buildings, an investor can compound their wealth indefinitely without the “tax drag” that occurs when a sale is fully liquidated.
The Role of Equity and Liquidity
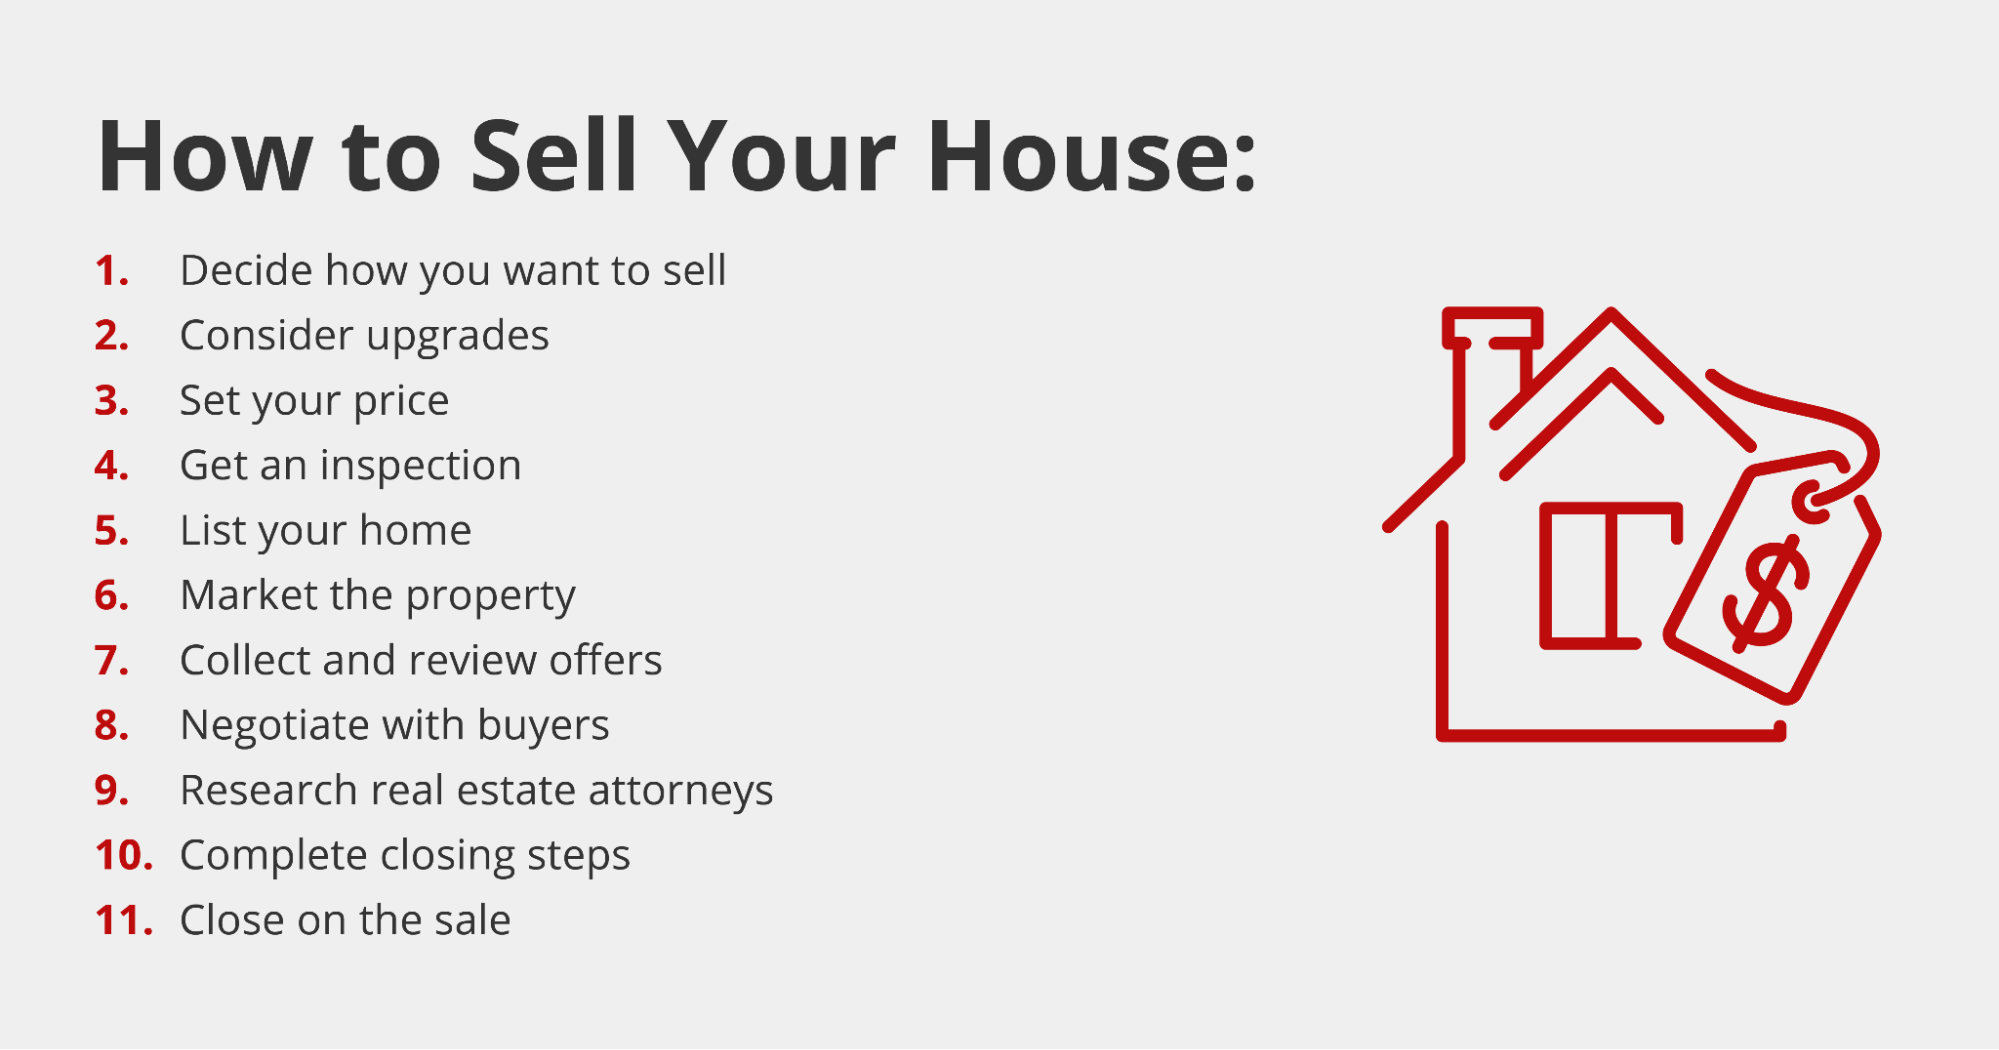
Finally, it is essential to understand that selling a house is an act of “releasing equity.” Real estate is an inherently illiquid asset. Unlike stocks, which can be sold in seconds, a house can take months to liquidate. Therefore, the decision to sell is often a strategic move to move capital from an illiquid, static state into a liquid state for reinvestment, debt reduction, or lifestyle funding.
Whether you are a real estate agent earning a commission, a flipper seeking capital gains, or a wholesaler collecting assignment fees, “selling houses” is fundamentally about the movement of capital. By mastering the terminology and the financial mechanics behind these various roles, you can better position yourself to profit from one of the world’s most enduring and lucrative asset classes.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.