
In the global financial marketplace, understanding the distinction between a religious framework and its practitioners is more than a matter of semantics; it is a critical requirement for investors, entrepreneurs, and financial strategists. When we look at the title “What is Islam vs Muslim” through the lens of modern finance, we are essentially distinguishing between a systemic economic framework—Islamic Finance—and the demographic behavior of the global Muslim consumer market.
Islam, as a faith, provides a comprehensive set of ethical and legal guidelines known as Sharia, which dictates how money should be earned, invested, and spent. On the other hand, the term Muslim refers to the individuals who navigate these rules within the modern economy. For those looking to capitalize on the multi-trillion dollar “Halal Economy,” understanding this nuance is the difference between a failed marketing campaign and a successful, high-yield investment strategy.

The Framework of Islam: Understanding Sharia-Compliant Finance
When we discuss “Islam” in a financial context, we are referring to the ethical architecture of Sharia-compliant finance. This system is one of the fastest-growing sectors in the global financial industry, consistently outperforming traditional benchmarks in various emerging markets. Unlike conventional finance, which is primarily driven by interest-based lending, Islamic finance is rooted in risk-sharing and asset-backed transactions.
The Prohibitions: Riba, Gharar, and Maysir
To understand the “Islam” side of the financial equation, one must grasp the three core prohibitions that define the system:
- Riba (Interest): The most well-known tenet is the prohibition of usury or interest. In this framework, money is seen as a medium of exchange, not a commodity that can generate more money on its own. This leads to the creation of profit-and-loss sharing (PLS) models.
- Gharar (Uncertainty): This prohibits contracts with excessive uncertainty or ambiguity. From a financial planning perspective, this often excludes complex derivatives and certain types of speculative insurance, pushing investors toward more transparent, tangible assets.
- Maysir (Gambling): Speculation that borders on gambling is forbidden. This encourages long-term value investing rather than high-frequency day trading or speculative bubbles.
The Instruments of Islamic Finance
Because of these prohibitions, the “Islam” side of the market has developed unique financial instruments that serve the same purpose as traditional ones but through different legal structures.
- Sukuk: Often referred to as “Islamic Bonds,” these represent ownership in a tangible asset rather than a debt obligation.
- Takaful: A co-operative form of insurance where members contribute to a pool to protect one another against loss, avoiding the traditional “betting against risk” model.
- Murabaha: A cost-plus financing structure used in real estate and trade, where the bank buys an asset and sells it to the client at a transparent profit margin, avoiding interest.
The Demographic Reality: Analyzing the Muslim Consumer Market
If “Islam” provides the rules of the game, “Muslims” are the players. Understanding the Muslim consumer is vital for any brand or investor looking at the “Money” niche. This demographic is not a monolith; it spans across continents, cultures, and income levels, yet it is unified by a shared set of consumption values that drive billions of dollars in annual spending.
The Power of the “Halal Economy”
The global Muslim population is expected to reach nearly 3 billion by 2050. This demographic shift has birthed the “Halal Economy,” which extends far beyond food. For a financial strategist, this represents a massive opportunity in sectors like:
- Modest Fashion: A multi-billion dollar industry that has seen mainstream adoption by brands like Nike and Uniqlo.
- Halal Travel: A niche focused on family-friendly environments and religious accommodations, representing a significant portion of global tourism spend.
- Digital Economy: The rise of “Muslim Tech,” including apps for prayer, Zakat (charity) calculation, and Sharia-compliant stock screening tools.
Spending Behavior and Economic Influence
Muslim consumers are increasingly young, tech-savvy, and brand-conscious. In the context of personal finance, this generation is seeking “Ethical Wealth Creation.” They are not just looking for a place to put their money; they are looking for investments that align with their identity. This has led to the rise of fintech platforms like Wahed Invest and Sarwa, which provide automated, Sharia-compliant portfolios. Understanding the Muslim consumer means recognizing that their financial decisions are often filtered through a lens of “Halal” (permissible) and “Tayyib” (wholesome/ethical).
Bridging the Gap: Strategic Investing and Wealth Management
The intersection of “Islam vs Muslim” is where the most sophisticated financial strategies are formed. It is the point where the rigid rules of the faith meet the fluid needs of the modern investor. For those looking to grow their wealth or enter this market, the strategy must be two-fold: adherence to the system (Islam) and engagement with the community (Muslim).
Sharia-Compliant Equity Investing
For the individual investor, distinguishing between these two terms allows for a more focused approach to the stock market. You are not just looking for “Muslim-owned” companies; you are looking for “Islam-compliant” companies. This involves a rigorous screening process:
- Business Activity Screen: Ensuring the company does not deal in prohibited industries like alcohol, tobacco, gambling, or conventional finance.
- Financial Ratio Screen: Analyzing the company’s balance sheet to ensure its debt-to-equity ratio is low and its interest-bearing income is minimal (usually less than 5%).
ETFs such as the SP Funds S&P 500 Mask Sharia Index ETF (SPUS) or the Wahed FTSE USA Sharia ETF (HLAL) have allowed mainstream investors—Muslim and non-Muslim alike—to access these high-quality, low-debt portfolios. Interestingly, these funds often perform well during economic downturns because they naturally exclude over-leveraged companies.
The Role of Zakat in Economic Circulation
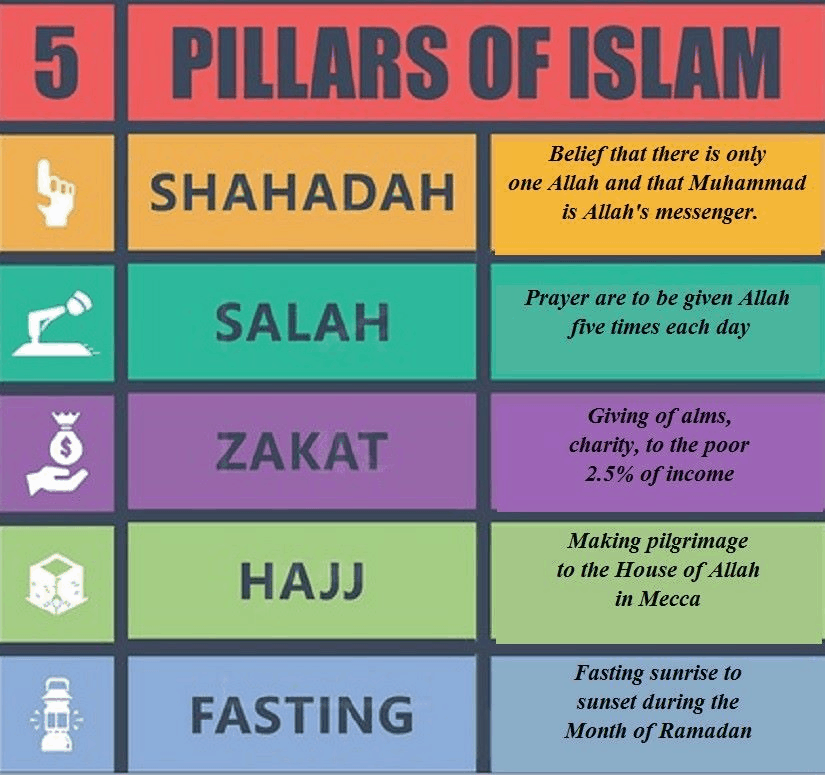
A unique aspect of the Muslim financial world is Zakat—the mandatory charitable contribution of 2.5% of one’s surplus wealth. From a macro-economic perspective, Zakat acts as a wealth redistribution tool that ensures liquidity within the economy. For the individual, it is a core component of “Personal Finance.” Calculating Zakat requires a deep understanding of one’s assets, from gold and cash to stocks and real estate. In the modern era, “Zakat Tech” has become a burgeoning sub-sector of the fintech world, helping Muslims automate their social impact and wealth purification.
The Future of Global Finance: Why the Distinction Matters
As we look toward the future of global money, the distinction between the system (Islam) and the people (Muslim) becomes even more critical for corporate strategy and personal wealth. We are seeing a convergence between Islamic Finance and ESG (Environmental, Social, and Governance) investing. Both frameworks prioritize ethical impact, transparency, and social responsibility over raw profit at any cost.
Opportunities for Entrepreneurs and Brands
For entrepreneurs, the “Muslim” side of the title represents a loyal and underserved market. However, success requires more than just a “Halal” sticker. It requires an understanding of the “Islam” side—the underlying ethics. Brands that succeed are those that integrate Sharia principles into their corporate identity, such as interest-free employee financing or ethical sourcing of materials.

Conclusion: A Unified Approach to Faith and Finance
To answer “What is Islam vs Muslim” in a financial context is to recognize the synergy between a rigorous ethical system and a dynamic global population. For the investor, Islam offers a blueprint for stability and ethical growth. For the marketer, the Muslim consumer offers one of the most significant growth opportunities of the 21st century.
By understanding the rules (Islam) and the people (Muslims), financial professionals can navigate a landscape that is not just about profit, but about purpose. Whether it is through Sharia-compliant ETFs, the booming Halal lifestyle market, or the integration of Zakat into digital banking, the fusion of faith and finance is reshaping the global economic order. The savvy participant in today’s economy knows that these two concepts, while distinct, are the twin engines driving a new era of ethical, high-growth wealth management.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.