
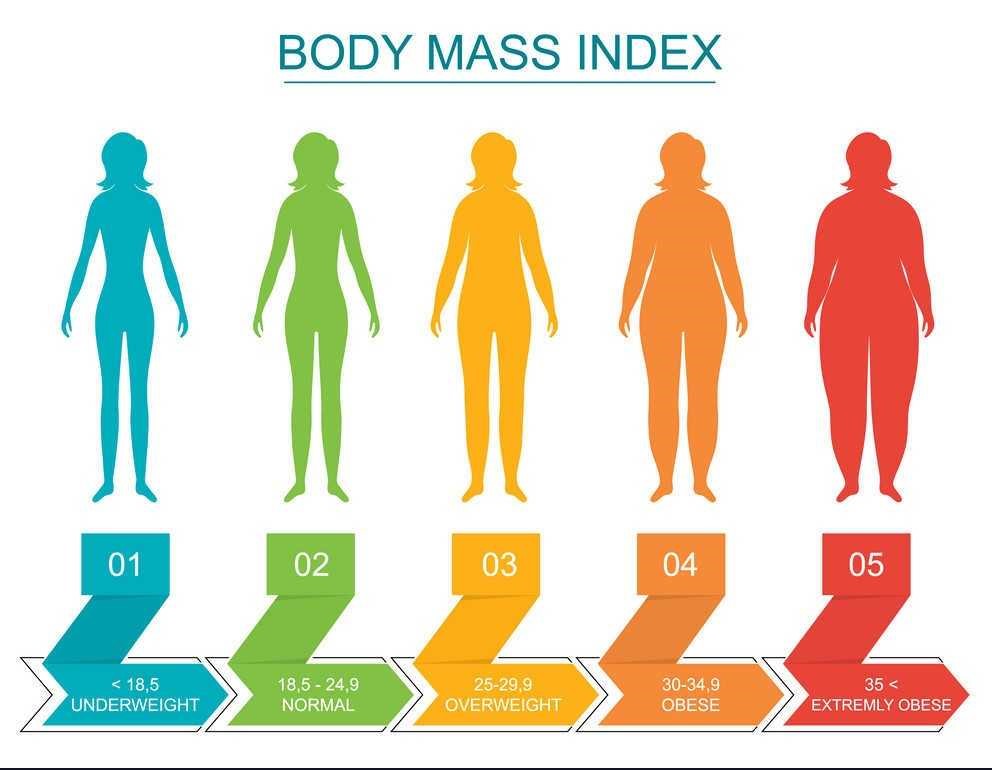
In the ecosystem of personal finance and institutional investing, the term “weight” transcends its physical definition, becoming a cornerstone of risk management and capital growth. When we ask “what is healthy weight,” we are inquiring into the optimal distribution of assets within a portfolio to ensure long-term sustainability, growth, and resilience against market volatility. Just as biological health requires a balance of nutrients, financial health demands a precise calibration of asset classes, sectors, and individual securities. A “healthy weight” is not a static number but a dynamic equilibrium tailored to an investor’s goals, time horizon, and risk tolerance.
Understanding this concept is essential for anyone looking to navigate the complexities of the modern market. Whether you are a retail investor managing a retirement account or a corporate treasurer overseeing a balance sheet, the “weighting” of your assets determines your exposure to both reward and ruin.
The Anatomy of Asset Allocation: Defining Weight in a Portfolio
At its simplest level, “weight” refers to the percentage of a total portfolio that a specific security or asset class represents. For example, if you have a $100,000 portfolio and $20,000 is invested in technology stocks, your “weight” in tech is 20%. Determining what constitutes a “healthy” version of these percentages is the primary objective of strategic asset allocation.
The Core Pillars: Stocks, Bonds, and Cash
A healthy financial weight usually starts with the three primary asset classes. Historically, a “balanced” portfolio followed the 60/40 rule—60% equities for growth and 40% fixed income for stability. However, in an era of fluctuating interest rates and high inflation, the definition of a healthy weight has shifted. Investors must now consider the “weight” of their cash reserves, ensuring they have enough liquidity to handle emergencies without being so “heavy” in cash that inflation erodes their purchasing power.
The Rise of Alternative Weighting
Modern financial health often requires looking beyond traditional stocks and bonds. A healthy weight in today’s market might include a 5% to 15% allocation to alternatives such as real estate (REITs), commodities, or private equity. These assets provide a “counterweight” to stock market volatility, ensuring that when one area of the portfolio loses mass, another gains or remains stable.
Market-Cap vs. Equal Weighting
Professional investors often debate the health of market-capitalization weighting versus equal weighting. In a market-cap-weighted index (like the S&P 500), the largest companies carry the most weight. While this captures the momentum of winners, it can lead to an “unhealthy” concentration in a few mega-cap tech stocks. An equal-weighted approach, where every company carries the same percentage regardless of size, can sometimes offer a healthier, more diversified exposure, albeit with different risk profiles.
Determining Your Healthy Weight: Factors and Constraints
There is no “one-size-fits-all” answer to what a healthy weight looks like. It is a highly personalized metric influenced by several critical factors. Identifying these constraints is the first step in building a robust financial “body.”
Time Horizon and the “Age Rule”
One of the oldest metrics for determining a healthy equity weight is subtracting your age from 100 (or 110/120 in modern contexts) to find your ideal stock percentage. A 30-year-old might have a “healthy weight” of 80% in equities, whereas a 70-year-old might find a 30% weight more appropriate. The longer your time horizon, the more “weight” you can afford to carry in volatile, high-growth assets.
Risk Tolerance and Volatility Thresholds
A healthy weight is one that allows the investor to sleep at night. If a 10% drop in the market causes panic selling, the weight of equities in that portfolio is objectively unhealthy for that specific individual. Stress-testing a portfolio involves simulating market downturns to see if the current weighting aligns with the investor’s psychological capacity to endure loss.
Income Requirements and Yield
For retirees or those seeking passive income, “healthy weight” is defined by yield. These portfolios are often “heavy” in dividend-paying stocks, bonds, and real estate. The goal here is to create a self-sustaining financial organism where the weight of the assets produces enough “energy” (cash flow) to cover living expenses without depleting the principal.
The Dangers of Malnutrition: Overweighting and Underweighting Risks

Just as being under- or overweight can lead to health complications in a person, improper weighting in a portfolio leads to financial fragility. Recognizing the signs of an unbalanced portfolio is crucial for long-term survival.
The Silent Killer: Concentration Risk
Overweighting occurs when a single asset or sector takes up a disproportionate amount of the portfolio. This often happens “accidentally” through capital appreciation. If you bought an AI stock early and it quadrupled in value, it might now represent 40% of your net worth. While this feels like success, it is a high-risk state. A single regulatory change or competitive shift in that industry could devastate your entire financial standing. A healthy weight requires the discipline to “trim” winners to maintain balance.
Underweighting and Opportunity Cost
Underweighting is the financial equivalent of malnutrition. If an investor is too “light” on equities during a bull market, they suffer from opportunity cost. They are not growing their wealth fast enough to outpace inflation or meet future goals. Many conservative investors, scarred by past market crashes, maintain a weight that is too heavy in cash or low-yield bonds, failing to realize that the lack of growth is a risk in itself.
Sector Bias and Correlation
A portfolio can appear diversified while being dangerously overweight in a specific theme. For instance, if an investor owns five different technology companies, a payment processor, and a digital advertising firm, they might believe they are diversified. However, these assets are often highly correlated. In a high-interest-rate environment, all these “weights” will likely drop simultaneously. A healthy weight ensures that assets are non-correlated, meaning they move independently of one another.
Rebalancing: The Routine “Exercise” for Financial Health
Achieving a healthy weight is not a one-time event; it is a continuous process of rebalancing. Rebalancing is the act of selling assets that have become too heavy and buying those that have become too light to return to your original target allocation.
Threshold-Based Rebalancing
This strategy involves setting a “tolerance band.” For example, if your target weight for emerging markets is 10%, you might decide that a healthy range is between 8% and 12%. If the weight hits 13% due to a market surge, you sell the excess and redistribute it. This mechanical approach removes emotion from the decision-making process, forcing the investor to “sell high and buy low.”
Periodic Rebalancing
Many financial advisors recommend a semi-annual or annual “check-up.” On a set date each year, the investor reviews their current weights against their targets. This serves as a “reset” for the portfolio, ensuring that the drift caused by market movements is corrected before it becomes a systemic risk.
The Tax Implications of Rebalancing
Maintaining a healthy weight has costs, particularly capital gains taxes. In taxable accounts, selling a “heavy” asset to rebalance can trigger a tax bill. Sophisticated investors use “tax-loss harvesting” or direct new contributions toward the underweight assets to bring the portfolio back into balance without triggering sales. This “nutrient timing” of capital inflows is one of the most efficient ways to maintain a healthy financial weight.
The Psychological Weight: Mental Models for Wealth Management
Finally, the concept of “healthy weight” extends to the psychological burden of managing wealth. Financial health is not just about the spreadsheet; it is about the relationship between the investor and their capital.
The Weight of Debt
In personal finance, debt is a “negative weight” that must be managed. A healthy financial structure prioritizes the elimination of high-interest “bad weight” (like credit card debt) while strategically using “good weight” (like low-interest mortgages or business loans) to leverage growth. The ratio of debt-to-equity is perhaps the most vital “vital sign” of corporate and personal financial health.
Decision Fatigue and Complexity
An “overweight” portfolio in terms of complexity can lead to paralysis. If an investor owns 50 different mutual funds and 100 individual stocks, the weight of monitoring those assets becomes a liability. A healthy weight often favors simplicity—using broad-market index tools to achieve the desired exposure with minimal maintenance.
The Role of Professional Guidance
Just as a nutritionist helps an individual find their ideal physical weight, a financial advisor helps define a healthy weight for a portfolio. They provide an objective perspective, preventing the emotional biases that lead to “binge-buying” during market bubbles or “starving” a portfolio during crashes.
In conclusion, “what is healthy weight” in the context of money and investing is the optimal distribution of resources that maximizes the probability of reaching a goal while minimizing the risk of a catastrophic loss. It requires constant monitoring, the discipline to rebalance, and the wisdom to understand that balance is a moving target. By focusing on asset allocation, risk management, and the avoidance of concentration, investors can ensure their portfolios remain “fit” for whatever challenges the market may present.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.