
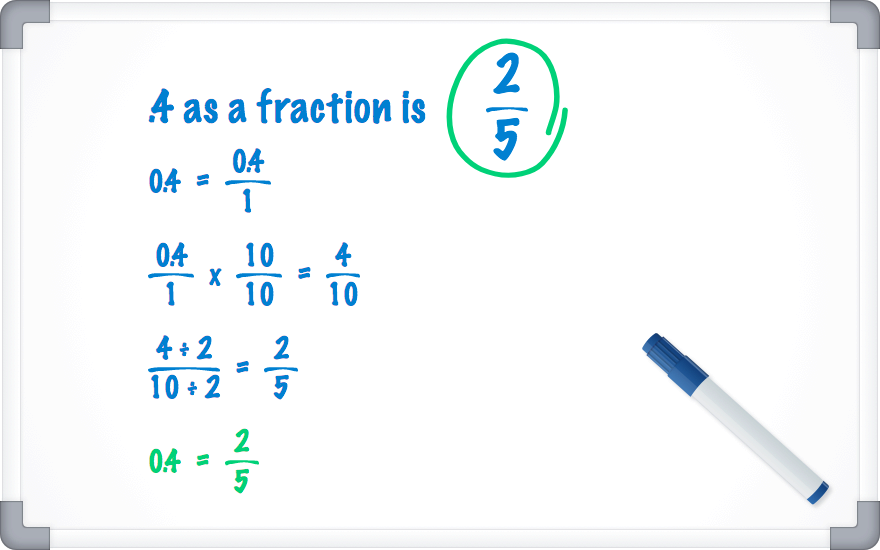
Understanding fundamental mathematical concepts is often overlooked in personal finance, yet their mastery can unlock significant insights and empower better decision-making. The seemingly simple question, “what is 4 in fraction,” serves as a potent metaphor for delving into the ubiquitous role of fractions, percentages, and proportions in managing money, making investments, and building wealth. At its core, expressing “4 as a fraction” means representing it as a part of a whole, typically with a denominator. For instance, 4 can be written as 4/1, 8/2, or 16/4. This basic conversion lays the groundwork for comprehending how financial assets are divided, how returns are calculated, and how budgets are meticulously allocated.
The Foundational Role of Fractions in Financial Literacy
Fractions are not merely abstract mathematical constructs; they are the bedrock of financial literacy, underpinning almost every aspect of personal and business finance. From calculating interest rates to understanding investment diversification, the ability to conceptualize and manipulate parts of a whole is indispensable.
Demystifying Whole and Part in Financial Contexts
In finance, “the whole” often represents your total income, your entire investment portfolio, or your complete savings. “The fraction” then signifies how these wholes are distributed, utilized, or grown. For example, if your total income is represented by the number “4” (say, $4,000 per month), then budgeting involves dividing this “4” into various fractional components: 1/4 for housing, 1/10 for savings, 1/8 for transportation, and so forth. Each fraction represents a specific allocation, ensuring that your financial resources are systematically managed.
Ignoring the fractional nature of financial data can lead to skewed perspectives and poor choices. Without understanding that a 25% debt-to-income ratio is essentially 1/4 of your income dedicated to debt payments, the gravity of financial obligations might be underestimated. Similarly, grasping that a quarterly return of 4% on an investment is just a fraction of the annual potential helps temper expectations and informs long-term planning. The question “what is 4 in fraction” thus evolves from a basic arithmetic problem into a powerful reminder of how every whole number, every dollar amount, can be dissected and understood in its constituent parts within the financial ecosystem.
Fractional Investing: Maximizing Every Dollar
The advent of fractional investing platforms has revolutionized access to markets, making the concept of “4 in fraction” profoundly tangible for everyday investors. No longer does one need to purchase an entire share of a high-priced stock; instead, a fraction of that share can be acquired, allowing smaller sums to participate in potentially lucrative opportunities.
Investing in Fractions of High-Value Assets
Consider a scenario where a single share of a leading technology company trades for $400. For an individual with limited capital, investing in such a stock might seem out of reach. However, with fractional investing, that same individual can choose to invest $4, thereby owning 1/100th of that share. This directly embodies the idea of “what is 4 in fraction” – taking a smaller sum ($4) and applying it as a fraction of a larger, desirable asset.
This approach democratizes investing, enabling individuals to:
-
Diversify portfolios with smaller capital: Instead of concentrating $400 into one share, an investor can spread $400 across 100 different stocks by investing $4 in each, significantly reducing risk.
-
Access blue-chip stocks: High-value companies previously inaccessible due to their per-share price are now within reach.
-
Start investing early and consistently: Even small, regular contributions (e.g., $4 every week) can be efficiently deployed into fractional shares, leveraging the power of dollar-cost averaging and compounding over time.
Fractional investing extends beyond stocks to include real estate through REITs (Real Estate Investment Trusts) or crowdfunding platforms, and even alternative assets like fine art or collectibles. In each case, an investor owns a proportion or “fraction” of a larger asset, allowing diversified exposure and efficient use of capital.
Budgeting and Allocation: Dividing Your “4” into Actionable Fractions
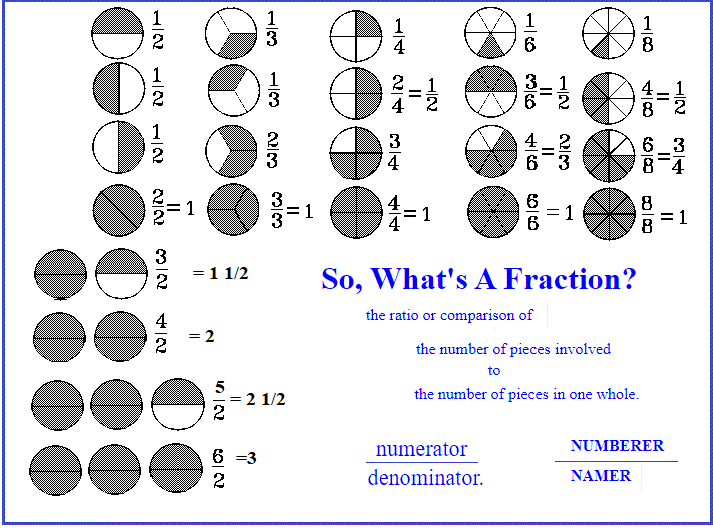
Effective personal finance hinges on astute budgeting, which is fundamentally an exercise in dividing a whole into appropriate fractions. Your total disposable income (the “4” in our analogy) must be strategically segmented to meet various financial goals, from daily expenses to long-term savings.
The Power of Proportional Spending
When you earn “4” units of currency, the challenge is to allocate these units in a way that aligns with your financial priorities. This often involves applying established budgeting rules or creating a customized fractional breakdown.
-
The 50/30/20 Rule: A popular guideline suggests allocating 50% (1/2) of your after-tax income to needs, 30% (3/10) to wants, and 20% (1/5) to savings and debt repayment. Each percentage is a fraction of your total income.
-
Zero-Based Budgeting: This method ensures every “fraction” of your income is assigned a specific job, leaving no unallocated funds. If you earn $4,000, you might assign $1,000 (1/4) to rent, $600 (3/20) to groceries, $800 (1/5) to debt, and so on, until your allocations total the entire $4,000.
Understanding how to convert these percentages back to absolute dollar amounts (e.g., 20% of $4,000 is $800) is a direct application of fraction conversion. By meticulously assigning each dollar (or “fraction” of your total income), you gain control over your spending, identify areas for optimization, and progress towards financial independence. This proportional spending ensures that your financial resources are not just spent, but strategically deployed.
Understanding Financial Ratios and Percentages: The Language of Opportunity
Fractions are the backbone of financial ratios and percentages, which serve as critical tools for evaluating financial health, investment performance, and economic trends. Interpreting “what is 4 in fraction” in this context reveals how seemingly simple ratios provide profound insights.
Interpreting Financial Health Through Ratios
Financial ratios are essentially comparisons expressed as fractions, simplifying complex data into digestible metrics.
-
Debt-to-Income (DTI) Ratio: This ratio compares your total monthly debt payments to your gross monthly income. If your debt payments are $1,000 and your income is $4,000, your DTI is $1,000/$4,000, which simplifies to 1/4 or 25%. A lower DTI (smaller fraction) is generally better, indicating lower financial risk.
-
Savings Rate: This is the fraction of your income that you save. If you save $800 from a $4,000 income, your savings rate is $800/$4,000, or 1/5 (20%). A higher savings rate signifies a greater fraction of your income is being directed towards future wealth.
-
Return on Investment (ROI): When you invest $4,000 and gain $400, your ROI is $400/$4,000, which is 1/10 or 10%. This fraction indicates the profitability of your investment relative to its initial cost.
These ratios transform raw numbers into meaningful benchmarks, allowing individuals to assess their financial standing against personal goals and industry standards. They empower informed decisions about borrowing, spending, and investing by clearly illustrating the proportional relationships between different financial elements.
Strategic Wealth Building Through Fractional Growth
The concept of “4 in fraction” also extends to the long-term journey of wealth accumulation, where consistent, fractional contributions, fueled by compound interest, can lead to substantial financial growth. It’s about understanding that even small fractions of your current income, consistently invested, can become a significant whole over time.
The Compounding Effect of Small, Consistent Contributions
Imagine committing a small fraction of your income—say, 1/10 or even 1/20 (e.g., $400 from a $4,000 income)—to an investment account each month. Over decades, this consistent application of a “fraction” of your earnings, combined with the power of compound interest, can grow exponentially. The interest earned on your principal also begins to earn interest, creating a snowball effect where fractions continuously multiply.
This strategy underscores several key principles:
-
Early Start: The earlier you begin contributing even small fractions, the more time compounding has to work its magic. A $400 monthly investment started at age 25 will yield significantly more than the same investment started at age 35, purely due to the extra decade of fractional compounding.
-
Consistency: Regularly setting aside that “fraction” of your income, regardless of market fluctuations, ensures continuous participation in growth opportunities.
-
Patience: Wealth building is not about striking it rich overnight but about the diligent accumulation of fractional gains over an extended period.
In essence, “what is 4 in fraction” becomes a powerful financial mantra: understand your whole, divide it strategically, and allow those fractions to grow exponentially. This foundational mathematical concept, when applied diligently to personal finance, becomes a potent tool for achieving financial security and building lasting wealth.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.