
In the world of personal finance and corporate accounting, success is rarely a matter of simple addition. Instead, wealth is built through the mastery of compounding, leverage, and the strategic division of assets. To answer the mathematical question “What is 3/5 of 2/3?” is to arrive at the figure of 2/5, or 40%. However, in the context of money management, this equation represents something far more significant: the reality of fractional ownership, the impact of taxation on gross margins, and the mechanics of equity dilution.
Understanding how to calculate a fraction of a fraction is a foundational skill for any investor or entrepreneur. Whether you are looking at the net take-home pay from a gross profit margin or determining your remaining stake in a startup after multiple funding rounds, the ability to visualize and calculate these “layers” of value is what separates sophisticated financial planners from the amateur.

The Financial Significance of Compound Fractions
In finance, we rarely deal with whole numbers. Interest rates, tax brackets, and management fees are all expressed as percentages or fractions of a larger whole. When we ask what 3/5 of 2/3 is, we are essentially performing a calculation of “net realization.”
Understanding the 40% Threshold
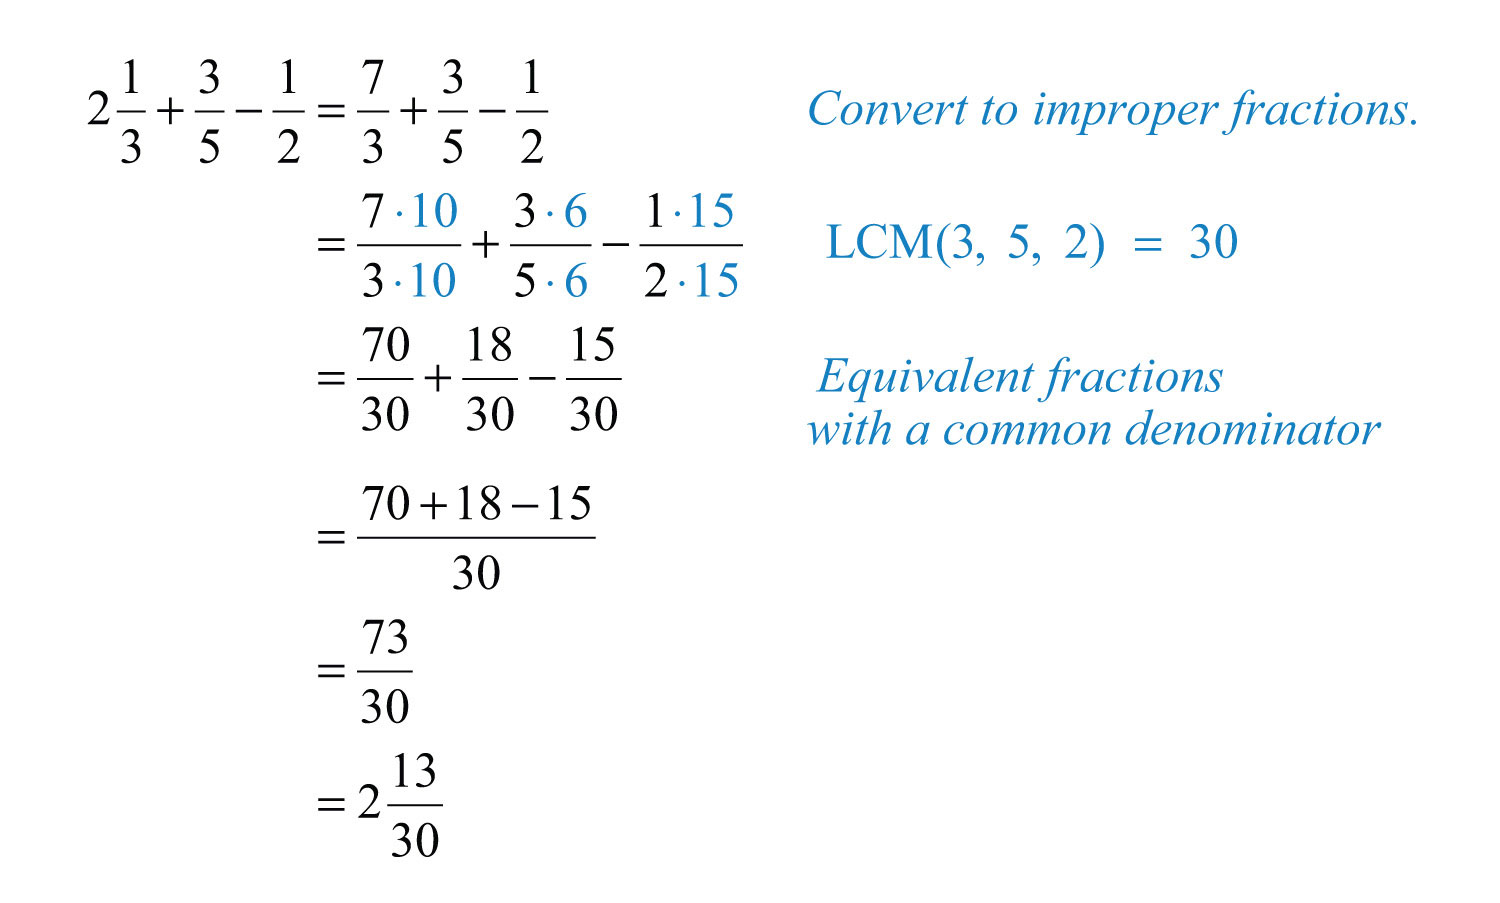
Mathematically, multiplying 3/5 by 2/3 results in 6/15, which simplifies directly to 2/5. In decimal terms, this is 0.40, or 40%. In the business world, 40% is often cited as a critical “Rule of 40” for software-as-a-service (SaaS) companies, where the sum of a company’s growth rate and profit margin should ideally exceed 40%.
When an investor analyzes a business that retains 2/3 of its market share but only converts 3/5 of that revenue into actual profit, they are looking at a 40% net efficiency rate. This logical progression is vital for evaluating the health of an enterprise. It demonstrates that the “top line” (the 2/3) is only as good as the “middle line” (the 3/5) that filters it.
Why Fractions of Fractions Drive Wealth Creation
Wealth creation is often the result of “nested” percentages. Consider a real estate investment trust (REIT) that owns a 2/3 stake in a multi-family housing development. If you, as an individual investor, own a 3/5 stake in a private fund that holds that REIT, your actual exposure to the physical asset is 40%.
Successful investors use this fractional logic to diversify. They understand that by taking small slices (3/5) of various larger opportunities (2/3), they can mitigate risk while maintaining exposure to high-growth sectors. This is the essence of portfolio theory: managing the fractions to ensure the whole remains robust.
Equity and Ownership: The Venture Capital Perspective
The calculation of 3/5 of 2/3 is perhaps most relevant in the high-stakes world of venture capital and startup equity. Founders rarely own 100% of their companies for long. As capital is raised, the “pie” is sliced repeatedly, and understanding the resulting fractions is essential for long-term financial survival.
The Cap Table Reality: Dilution and Down-Rounds
Imagine a founder who has successfully navigated early-stage seed funding and retains 2/3 of the company’s total equity. This is a strong position. However, to scale the business to a global level, they may need to sell 3/5 of their remaining stake to a Tier-1 venture capital firm.
The resulting 40% total ownership is a classic example of how “owning a smaller piece of a bigger pie” works in practice. While the percentage has decreased, the valuation of the underlying asset has likely grown exponentially. However, without a firm grasp of fractional math, a founder may not realize how quickly a 66% stake can be whittled down to a minority position through successive rounds of dilution.
Holding Companies and Multi-Layered Ownership
Large-scale business finance often utilizes holding companies to manage liabilities and tax exposure. If a parent corporation owns 2/3 of a subsidiary, and a secondary investor buys 3/5 of that parent company’s interest in the subsidiary, the secondary investor effectively controls 40% of the subsidiary’s assets.
This structure is common in international business and private equity. It allows for the movement of capital across borders and industries while maintaining specific levels of control. For the savvy investor, identifying these fractional layers is the key to uncovering hidden value or identifying where a majority shareholder might be losing their grip on an asset.
Net Returns: The Erosion of Gross Profitability
One of the most painful lessons in personal finance is the difference between gross returns and net returns. The “3/5 of 2/3” analogy is a perfect framework for understanding how inflation, taxes, and fees erode your wealth.
The Tax Collector’s Slice
Suppose you have an investment that yields a 2/3 (66.6%) return—an extraordinary performance by any standard. However, that is the gross return. Before you can spend or reinvest that money, the government and the market take their shares. If you are in a high tax bracket and are subject to capital gains taxes, you might only keep 3/5 of those gains.
Your “real” return is not the 66.6% you see on your brokerage statement; it is the 40% that actually hits your bank account. Professional wealth management is focused almost entirely on optimizing this second fraction. By using tax-loss harvesting, 401(k) contributions, or offshore entities, investors try to move that 3/5 fraction closer to 1/1 (100%), ensuring they keep more of the 2/3 they earned.
Management Fees and the Hidden Cost of Investing
In the world of mutual funds and hedge funds, the “expense ratio” is the silent killer of compounding. If a fund generates 2/3 of the market’s total upside, but the management takes a significant cut of those profits (the carry) plus a management fee, the investor’s portion might be reduced to 3/5 of that performance.
Over a 30-year horizon, the difference between keeping 2/3 of your returns versus keeping 3/5 of 2/3 (40%) can result in a difference of hundreds of thousands, or even millions, of dollars. This is why low-cost index funds have become the preferred tool for the modern investor; they aim to keep the first fraction as large as possible by minimizing the second “fee” fraction.
Strategic Asset Allocation in a Fragmented Economy
As we move further into a digital-first economy, the ways we generate income are becoming increasingly fragmented. Side hustles, gig work, and fractional real estate platforms allow us to earn money in “slices.”
The Rule of 40% in Personal Income
Many financial advisors suggest the “40% Rule” for discretionary income. If you earn a significant bonus or a windfall from a side business, the logic follows that you should treat that income as a fraction of a fraction. If 2/3 of your income goes to essential living expenses and debt service, the remaining 1/3 is your “opportunity fund.”
However, within that opportunity fund, you must be disciplined. If you take 3/5 of that remaining third and put it into long-term investments, you are creating a sustainable cycle of wealth. The 3/5 of 2/3 calculation encourages a mindset of “allocation before consumption.”
Optimizing the Side Hustle
For those managing online income or freelance portfolios, the 3/5 of 2/3 rule can be applied to time management. If 2/3 of your clients provide the bulk of your professional satisfaction, but only 3/5 of those clients are truly profitable after accounting for the time spent on revisions and communication, then you are only operating at 40% efficiency.
Identifying this 40% core allows you to fire low-value clients and double down on the high-value “fractions” of your business. In the world of money, time is the ultimate currency, and fractional math is the tool we use to budget it.

Risk Mitigation and the Fractional Mindset
Finally, understanding 3/5 of 2/3 is about risk management. In finance, “exposure” is rarely 1:1. When you invest in a derivative, a leveraged ETF, or a margin-backed stock, you are playing with fractions that can move against you just as quickly as they move for you.
A fractional mindset allows an investor to see the “cascading” risk. If a bank has a 2/3 exposure to the real estate market, and 3/5 of those loans are subprime or high-risk, the bank’s total high-risk exposure is 40%. This might seem manageable until a market correction occurs. By breaking down large, intimidating numbers into these component fractions, investors can more accurately assess the “Value at Risk” (VaR) in their portfolios.
Whether you are calculating the simplified math of 2/5 or applying that 40% figure to your next corporate merger, the lesson remains the same: in the realm of money, it is not what you make, but what you keep after the fractions have been cleared. Mastering the relationship between 3/5 and 2/3 is the first step toward a more sophisticated, analytical, and ultimately more profitable financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.