
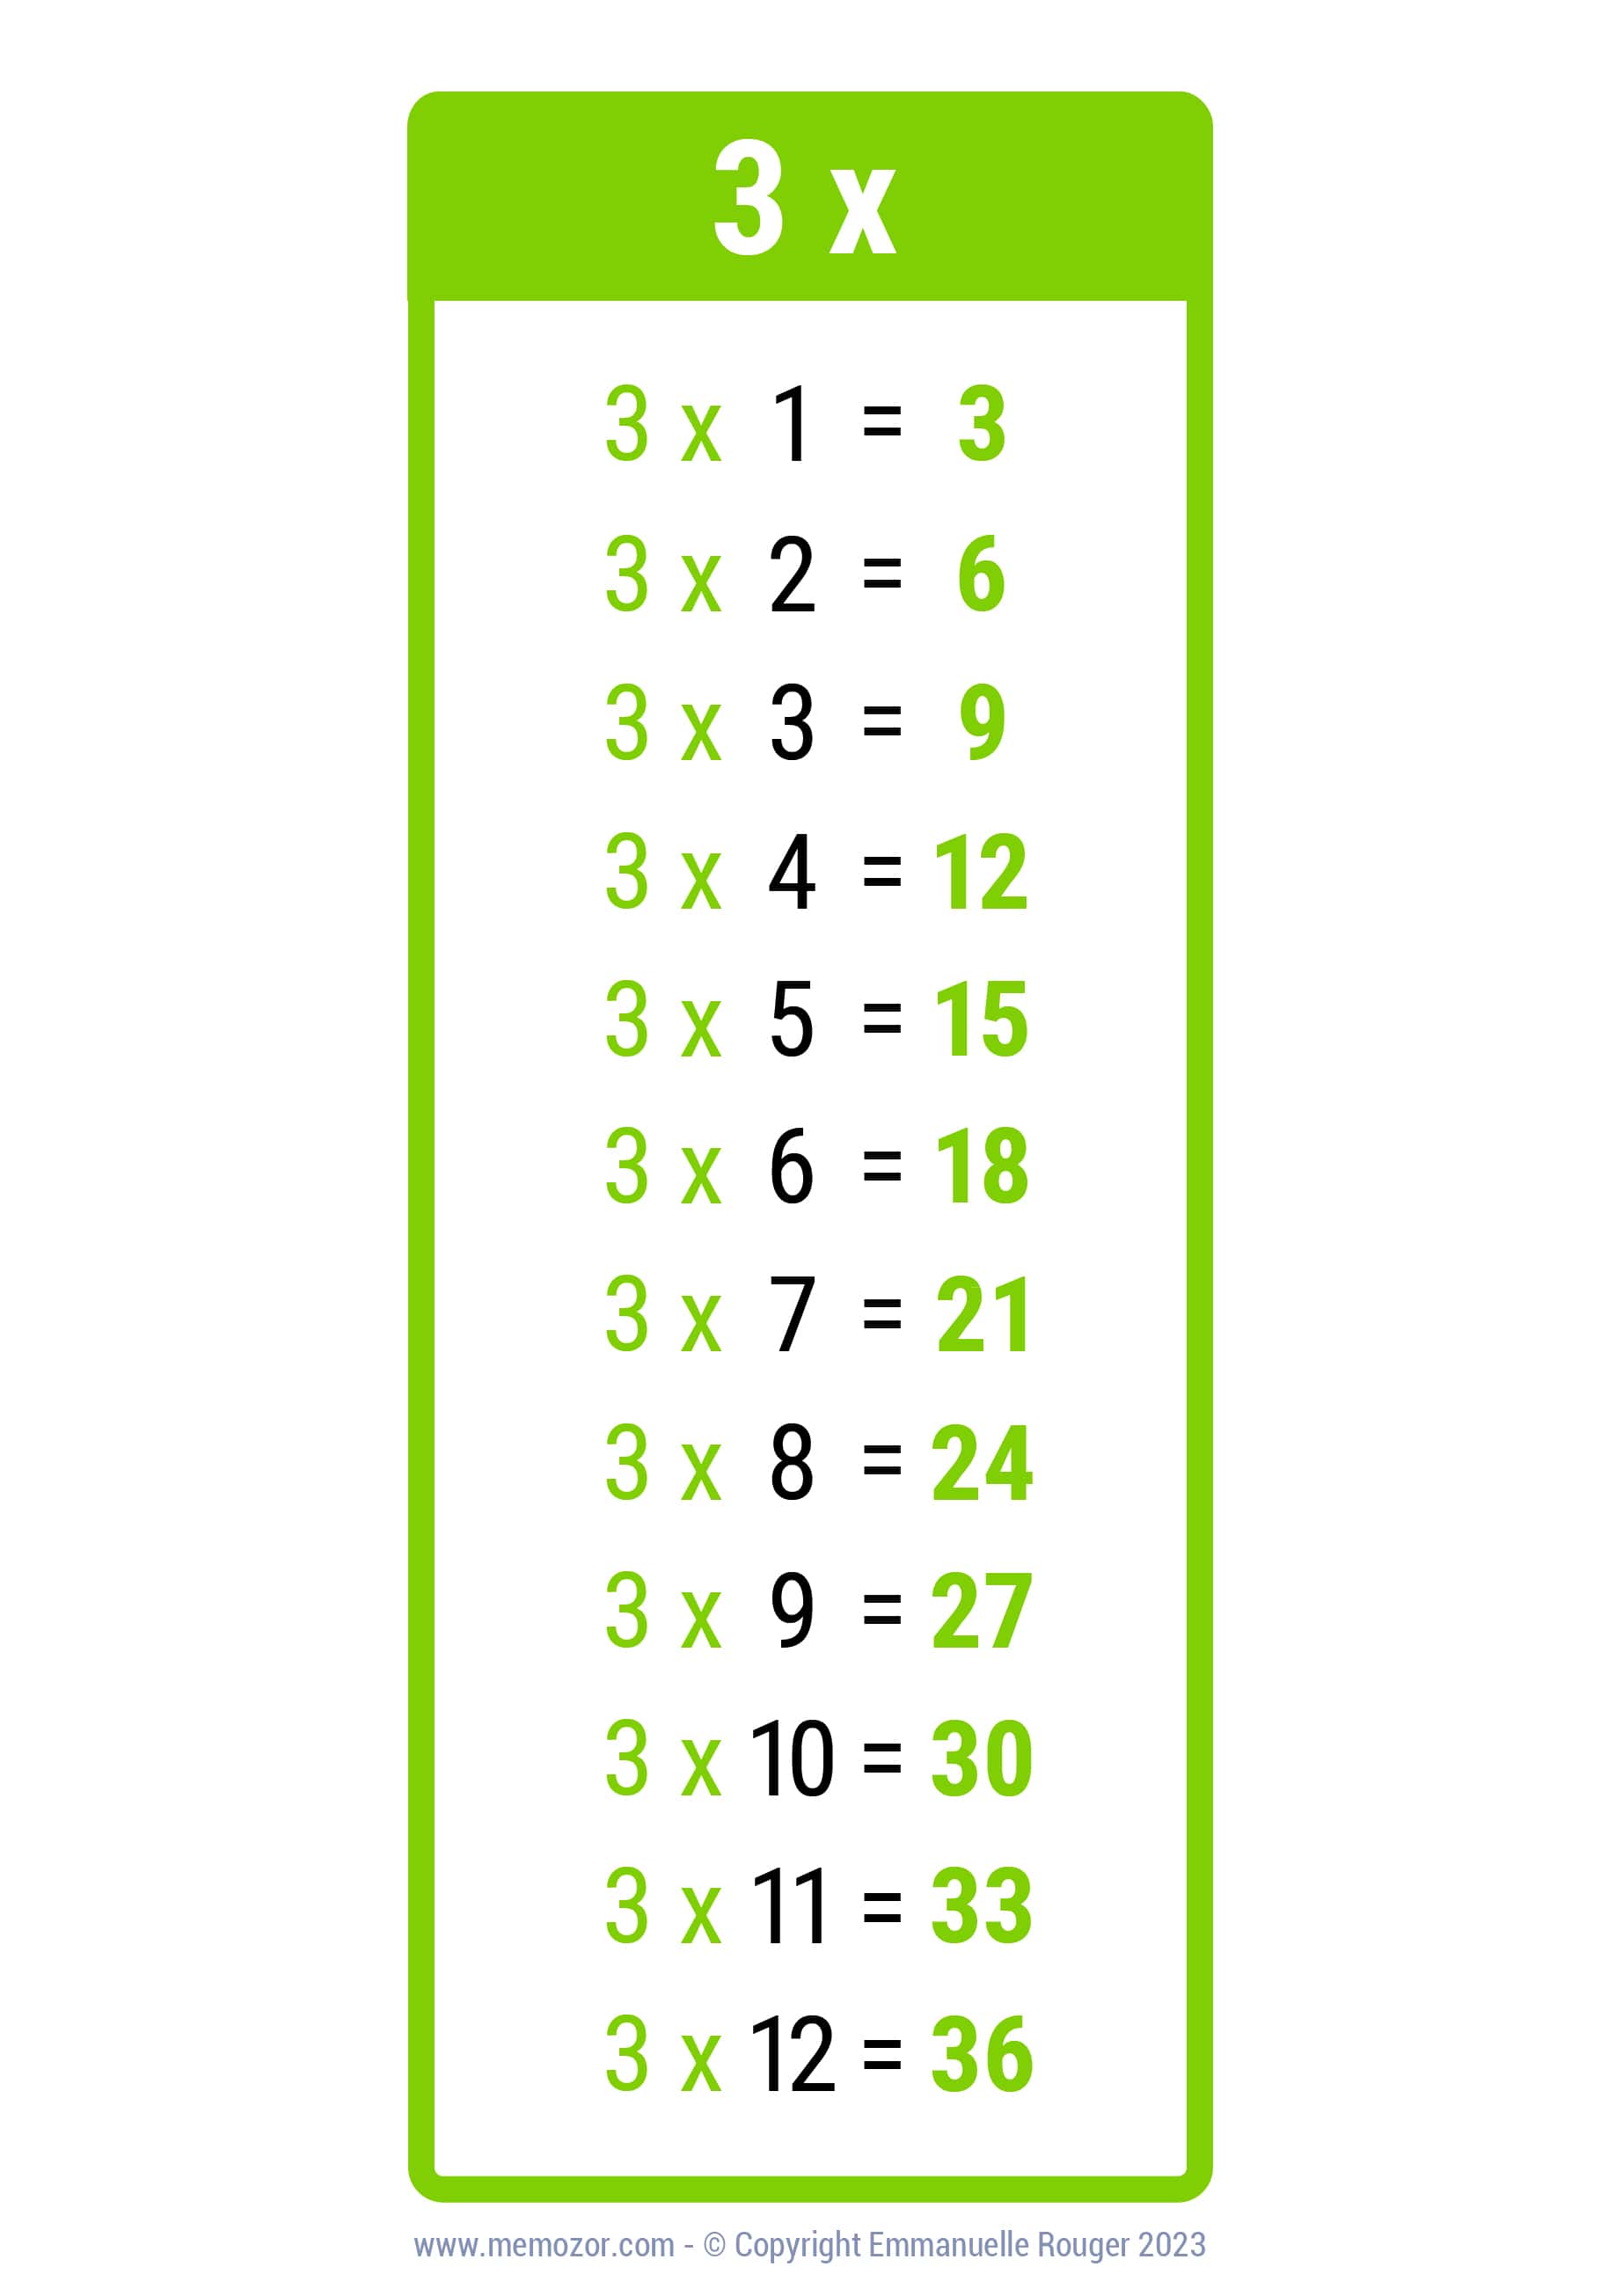
At first glance, the question “what is 3 times 4” appears deceptively simple, a relic from elementary school arithmetic, yielding an unequivocal answer: 12. Yet, for those navigating the intricate landscape of personal finance, investing, and business strategy, this fundamental calculation represents far more than a mere numerical exercise. It embodies the very bedrock of financial literacy, a foundational principle that, when understood deeply, unlocks insights into wealth creation, debt management, and the nuanced operations of the global economy. In the realm of money, every significant financial outcome, every strategic decision, and every long-term plan is ultimately built upon a series of basic mathematical operations, where the simplicity of “3 times 4” scales into the complexity of millions and billions. Ignoring these basic truths, or failing to grasp their profound implications, can lead to costly errors and missed opportunities.

Beyond Basic Arithmetic: The Multiplicative Power of Financial Decisions
The answer “12” to “what is 3 times 4” is a fact, but in finance, it’s a starting point. Every financial choice, no matter how small, carries a multiplicative effect that can compound over time, shaping one’s financial destiny. Understanding this principle is crucial for building robust financial health.
The Daily Budget: Where Every Penny Multiplies
Consider the seemingly innocuous daily expenditures. A $4 coffee purchased three times a week might not seem significant in isolation. However, applying the “3 times 4” principle reveals an annual impact. Three coffees at $4 each is $12 per week. Multiplied by 52 weeks in a year, this equates to $624 annually. This single, small habit, when consistently applied, multiplies into a substantial sum that could otherwise be allocated to savings, debt reduction, or investment. The act of budgeting is precisely this: understanding how recurring small “multiplications” accumulate into larger annual totals, whether they are discretionary spending, subscription services, or essential utilities. It demands a mindful approach, where every dollar is assigned a purpose, preventing the erosion of wealth through unchecked, seemingly minor outflows.
Compound Interest: The Eighth Wonder of the World, Mathematically Explained
Perhaps the most potent illustration of the power of multiplication in finance is compound interest. Often dubbed “the eighth wonder of the world,” compound interest allows an investment to grow exponentially, as interest is earned not only on the initial principal but also on the accumulated interest from previous periods. Imagine a starting principal of $1,000 earning 3% interest, compounded annually. In year one, it grows by $30 (3% of $1,000). In year two, however, the 3% is applied to $1,030, yielding $30.90, and so on. Over decades, this seemingly modest “3 times 4” (a small interest rate applied over multiple periods) transforms into substantial wealth accumulation. Conversely, neglecting the power of compound interest through delayed savings can result in significant opportunity costs, where the multiplicative benefit of early investment is permanently lost.
Debt: The Inverse Multiplier
While compound interest works in favor of the investor, compound debt operates as an inverse multiplier, eroding wealth rapidly. Credit card interest rates, for instance, often hover around 15-25% annually. A balance of $1,000 at 20% interest, making only minimum payments, can quickly balloon. The “3 times 4” here might represent 3 months of carrying a $1,000 balance at 4% monthly interest (roughly 4% of $1,000 is $40), quickly turning a manageable sum into a growing burden. Each month, the interest is calculated on the remaining principal plus the accrued interest, creating a compounding effect that can trap individuals in a cycle of ever-increasing financial obligations. Understanding the arithmetic of debt, how interest rates and minimum payments multiply to prolong repayment and increase total costs, is as critical as understanding the arithmetic of savings.
From Simple Sums to Strategic Investments: Building a Robust Financial Future
Moving beyond personal budgeting, the capacity to perform and comprehend basic numerical relationships is indispensable for effective investment. Strategic investment decisions are not based on guesswork but on a solid foundation of mathematical analysis.
Valuing Investments: P/E Ratios and Beyond
Professional investors consistently use ratios and metrics that are essentially sophisticated applications of fundamental arithmetic. The Price-to-Earnings (P/E) ratio, for example, is a cornerstone of stock valuation. If a company’s stock trades at $12 per share and it earns $3 per share annually, its P/E ratio is 4 ($12/$3). This simple division offers a quick insight into how much investors are willing to pay for each dollar of earnings. Similarly, calculations for dividend yield, return on investment (ROI), and earnings per share (EPS) are all direct descendants of basic multiplication and division. Without a firm grasp of these straightforward calculations, interpreting financial statements, comparing investment opportunities, or assessing a company’s fundamental health becomes an insurmountable task. The “3 times 4” concept here is about understanding how these simple ratios provide profound insights into complex financial instruments.
Understanding Returns and Risk: The Language of Numbers
Every investment carries a degree of risk and an expectation of return. Both are quantified using numerical expressions derived from basic statistical and arithmetic principles. Expected returns are often presented as percentages, requiring an understanding of how these percentages translate into actual dollar gains over time. Risk, too, is quantified through metrics like standard deviation or Beta, which measure volatility. While these concepts might seem advanced, their underlying calculation often boils down to summing, subtracting, multiplying, and dividing data points. Investors must be able to comprehend that if an asset has historically returned 10% per year, but with a high standard deviation, it implies that the actual returns could fluctuate significantly around that average. The ability to interpret these numbers, rather than just accepting them at face value, empowers investors to make informed decisions that align with their risk tolerance and financial goals.
Diversification: Multiplying Your Security, Not Just Your Assets
Diversification is a core tenet of prudent investing, advising against putting all your eggs in one basket. This strategy is inherently mathematical. It’s not just about owning multiple assets, but understanding how those assets behave in relation to each other. By investing in three or four different, uncorrelated asset classes—stocks, bonds, real estate, commodities—an investor mathematically reduces overall portfolio risk. When one asset performs poorly, another might perform well, balancing out returns. This strategy leverages the multiplicative principle: instead of having one large risk exposure (e.g., “1 times 12” as one large investment), it distributes that exposure across multiple, smaller, less correlated risks, effectively multiplying your security and stability, even if individual asset returns are “3 times 4” in isolation.
The Entrepreneur’s Equation: Calculating Success in Business Finance
For entrepreneurs and business leaders, the ability to translate strategic vision into tangible financial outcomes rests heavily on mastering basic numerical operations. Every operational decision, from pricing a product to expanding into new markets, has a “3 times 4” at its core.
Profit Margins and Break-Even Points: The Core Business Multipliers
Businesses thrive on profitability, which is measured by profit margins. Gross profit margin (Gross Profit / Revenue) and net profit margin (Net Income / Revenue) are fundamental ratios calculated through simple division. They tell a story about a company’s efficiency and pricing power. Similarly, determining the break-even point—the sales volume at which total revenues equal total costs—is a critical calculation. It involves dividing fixed costs by the per-unit contribution margin (price per unit minus variable costs per unit). An entrepreneur needs to know, for example, that if their profit per unit is $3, they need to sell 4 units to generate $12 in profit, or how many units they must sell to cover their fixed costs. These simple equations dictate the viability and potential for growth of any enterprise.
Scaling Operations: When 3 Times 4 Becomes 300 Times 400
Growth, or scaling, is the aspiration of most businesses. However, scaling without sound unit economics can multiply losses instead of profits. If the cost to acquire one customer is $3 and the lifetime value of that customer is $4, the business has a healthy customer acquisition strategy ($3 invested yields $4). But if that ratio is inverted, scaling means multiplying losses. Understanding the “3 times 4” of unit economics—the revenue and cost associated with a single unit of product or service—is vital before multiplying those operations by factors of hundreds or thousands. A simple positive ratio at a small scale ensures that when operations expand from “3 times 4” to “300 times 400,” the business multiplies its success, not its inherent inefficiencies.
Cash Flow Management: The Lifeblood of Your Enterprise
Cash flow is the oxygen of any business. Managing it effectively requires a constant awareness of inflows and outflows, a continuous exercise in addition and subtraction. Cash flow projections involve estimating future revenues and expenses over specific periods. These projections are essentially large-scale “3 times 4” calculations, where “3” might represent recurring monthly expenses and “4” the number of months in a quarter. Businesses must ensure they have enough liquid funds to cover operational costs, invest in growth, and manage unforeseen circumstances. A firm grip on cash flow ensures that the business can always meet its obligations, avoiding liquidity crises that can cripple even fundamentally profitable ventures.
Leveraging Financial Tools: Smarter Calculations, Better Outcomes
In the digital age, sophisticated financial software and AI tools abound, promising to simplify complex calculations. While these tools are invaluable, they do not negate the need for a fundamental understanding of the underlying mathematics.
The Calculator as a Strategic Partner
From a basic handheld calculator to advanced spreadsheet software like Excel, financial tools automate arithmetic. However, their efficacy is entirely dependent on the quality of the input and the user’s understanding of what they are calculating. If an individual inputs “3 times 5” when they meant “3 times 4,” the calculator will dutifully produce “15,” leading to an erroneous conclusion. The tool simply executes the command; the strategic thinking, the contextual understanding, and the initial setup of the problem (knowing whether to multiply, divide, or sum) remain human responsibilities. The calculator is a powerful partner, but it cannot compensate for a lack of conceptual clarity regarding the “what is 3 times 4” level of financial operations.
Demystifying Algorithms: From Simple Sums to Complex Models
Modern financial systems, from automated trading platforms to personal finance apps, rely on complex algorithms. These algorithms, however, are ultimately built upon foundational mathematical principles. They perform countless calculations—multiplications, divisions, additions, subtractions—at lightning speed, often with multiple variables. Understanding the basics of how these operations combine allows users to better interpret the outputs of these complex models. It moves beyond blindly trusting a “black box” solution and empowers individuals to question, validate, and leverage these tools more effectively. The “why” behind an algorithmic recommendation often traces back to a series of “3 times 4” operations performed millions of times.

The Human Element: Why Intuition Still Needs Calculation
Financial decisions are rarely purely mathematical; they often involve elements of intuition, risk assessment, and behavioral psychology. However, even the sharpest intuition benefits immensely from being grounded in solid numerical analysis. A gut feeling about an investment opportunity or a business venture should be rigorously stress-tested with “3 times 4” level calculations: What are the potential returns? What are the associated costs? How will various scenarios impact cash flow? Combining human insight and judgment with precise numerical calculation leads to the most robust and defensible financial strategies.
In conclusion, “what is 3 times 4” transcends its simple answer, serving as a powerful metaphor for the absolute necessity of financial numeracy. From managing a personal budget and navigating the complexities of compound interest and debt, to making strategic investment decisions and running a profitable business, the ability to understand, apply, and interpret basic mathematical operations is the bedrock of financial competence. In a world saturated with complex financial products and data, mastering these fundamental calculations is not merely an academic exercise, but a vital skill for achieving economic security and prosperity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.