
At first glance, the question “what is 20 in fraction?” might seem like a simple mathematical query, perhaps even elementary. The immediate answer is straightforward: 20 can be expressed as 20/1. While numerically trivial, the underlying concept of representing a whole number as a fraction, and understanding the inverse – how fractions represent parts of a whole – is profoundly significant, especially when navigating the intricate world of personal finance and investing. This fundamental grasp of fractions isn’t just about passing a math test; it’s the bedrock upon which sound financial literacy is built, enabling individuals to make informed decisions about their money.

From budgeting and saving to understanding interest rates, investment returns, and tax implications, fractions and their close relatives, percentages, are the universal language of finance. Without a solid foundation in these basic mathematical principles, financial concepts can remain abstract, confusing, and intimidating. This article delves into why understanding “20 in fraction” – and the broader implications of fractional thinking – is not merely a mathematical exercise but an indispensable tool for achieving financial mastery.
The Indispensable Role of Basic Math in Financial Literacy
Financial literacy isn’t about being a human calculator; it’s about comprehending the relationships between different monetary values and how they impact your overall financial health. At its core, this understanding relies heavily on basic arithmetic, including the concept of fractions. Just as an architect needs to understand basic geometry to design a building, a financially savvy individual needs to understand fractions to build and manage their wealth effectively.
From Integers to Intricate Financial Scenarios
Every financial transaction, from buying a coffee to investing in a stock, involves numbers. While many of these are presented as whole numbers (e.g., $5, $1000), their true impact and relationship often become clear only when viewed through the lens of fractions or percentages. For instance, a pay raise of $100 might seem significant, but its actual value is relative to your total income, a relationship best expressed as a fraction or percentage. If your income is $2000, that’s a 100/2000 = 1/20 = 5% raise. If your income is $10,000, it’s a 100/10000 = 1/100 = 1% raise. The numerical value is the same, but its proportional impact is vastly different, a nuance revealed by fractional thinking.
This foundational understanding extends to more complex scenarios. When you read about inflation rates, economic growth, market share, or portfolio diversification, you’re constantly encountering concepts that are inherently fractional. Ignoring or misunderstanding these foundational mathematical relationships is akin to trying to read a foreign language without knowing its alphabet; you might recognize some words, but true comprehension will be elusive.
The Fundamental Logic of 20/1 and Beyond
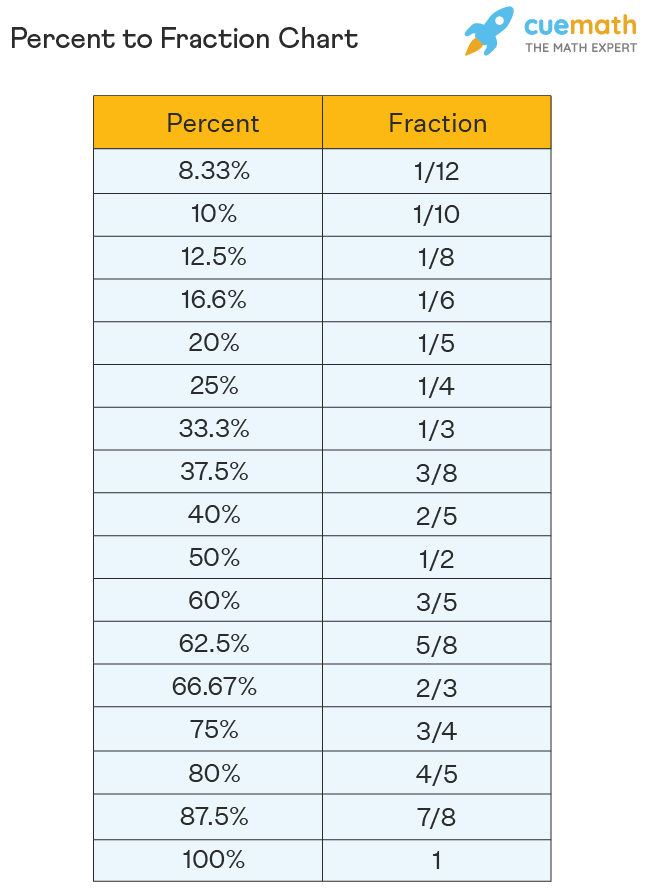
The conversion of 20 to 20/1 is the simplest form of fractional representation. It signifies that 20 units are being considered as a whole, undivided entity. However, the power of fractions truly emerges when we consider parts of a whole. If we were to ask, “what is 20 percent as a fraction?”, the answer would be 20/100, which simplifies to 1/5. This simple conversion is where the financial magic begins.
Consider a scenario where you want to save 20% of your income. Understanding that 20% is 1/5 of your income instantly provides a clearer mental model. If you earn $2,500, you know you need to save $500 (1/5 of $2,500). This isn’t just a calculation; it’s a conceptual framework that allows you to visualize and allocate your resources with greater clarity. It empowers you to break down large financial goals into manageable fractional parts, making them seem less daunting and more achievable. This fundamental logic, starting from the simple 20/1, is the gateway to understanding proportionality and distribution in finance.
Fractions: The Unsung Heroes of Personal Finance
While often overshadowed by the seemingly more sophisticated tools of financial analysis, fractions are the unsung heroes that underpin almost every aspect of personal finance. They provide a clear, concise way to express relationships between different financial components, making complex information digestible and actionable.
Deconstructing Discounts, Interest, and Tax Rates
Think about the ubiquitous presence of discounts. A “20% off” sale is a direct application of fractional thinking. It means you’re paying 80% (or 4/5) of the original price, and saving 20% (or 1/5). Without understanding this, the concept of a discount remains superficial. Similarly, interest rates on loans or savings accounts are always expressed as percentages, which are essentially fractions out of 100. A 5% annual interest rate means you’ll pay or earn 5/100 (or 1/20) of the principal amount over a year. Understanding this allows you to compare different loan offers, calculate the real cost of borrowing, or project the growth of your savings.
Tax rates, whether for income, sales, or capital gains, are another prime example. Knowing that your income is subject to a 20% tax bracket means that 1/5 of that specific portion of your earnings will go towards taxes. This fractional awareness is crucial for accurate financial planning, budgeting for tax season, and understanding your net income.
Budgeting and Asset Allocation: A Fractional Perspective
One of the most powerful applications of fractional understanding is in budgeting and asset allocation. Budgeting is inherently about dividing your total income into various categories: housing, food, transportation, savings, and discretionary spending. Many popular budgeting methodologies, such as the 50/30/20 rule, are explicitly fractional. This rule suggests allocating 50% of your income to needs, 30% to wants, and 20% to savings and debt repayment. Each of these percentages is a fraction (1/2, 3/10, 1/5 respectively) of your total income. By understanding these as fractions, you can easily calculate how much money goes into each bucket, providing a clear roadmap for managing your cash flow.
In investing, asset allocation involves deciding how to divide your investment portfolio among different asset classes like stocks, bonds, and real estate. An investor might decide to put 60% of their portfolio in stocks, 30% in bonds, and 10% in real estate. This is a fractional distribution (3/5, 3/10, 1/10) that reflects their risk tolerance and financial goals. A clear understanding of these fractions helps investors maintain their desired allocation, rebalance their portfolio periodically, and manage risk effectively.
Measuring Investment Performance and Risk
When evaluating investments, metrics are often presented as returns over a period. A 20% annual return means your investment grew by 1/5 of its original value in that year. This fractional increase is vital for projecting future growth and comparing different investment vehicles. Furthermore, risk is often quantified in fractional or percentage terms, such as the probability of a market downturn or the volatility of a particular stock. Grasping these fractional representations of risk allows investors to make more prudent decisions aligned with their personal risk appetite. For example, understanding that a certain investment carries a 20% chance of a significant loss helps an investor weigh potential rewards against acceptable risks.
The Ubiquity of Percentages: 20% and Its Financial Significance
While fractions are the foundational concept, percentages are their practical, often-used counterpart in finance. A percentage is simply a fraction where the denominator is always 100. Thus, understanding “20 in fraction” naturally extends to “20% in finance,” which is one of the most frequently encountered financial metrics. The number 20, in its percentage form, pops up everywhere from financial news to personal financial planning.
Unpacking Growth Rates, Returns, and Expense Ratios
When a company announces 20% revenue growth, it means their income increased by one-fifth. When your investment portfolio yields a 20% return, it signifies a substantial growth of one-fifth of your capital. Conversely, an expense ratio of 0.20% (or 20/10000 = 1/500) on an investment fund might seem small, but understanding its fractional nature reveals it as a persistent drag on your returns over time. Every percentage point, when converted to its fractional equivalent, provides a clearer perspective on its magnitude and impact.
This understanding is critical for comparing different financial products. Is a savings account offering 0.5% interest really that different from one offering 0.6%? While the percentage difference seems small, understanding it as 0.5/100 vs. 0.6/100 helps contextualize the marginal gain. In investment, a consistent 20% annual return is exceptional and understanding it as a 1/5 increase each year helps appreciate the power of compounding.
The Transformative Power of Compound Interest
Perhaps no financial concept illustrates the power of fractions and percentages better than compound interest. Often dubbed the “eighth wonder of the world,” compound interest refers to earning interest not only on the initial principal but also on the accumulated interest from previous periods. If you invest $1,000 at a 20% annual interest rate, in the first year you earn $200 (1/5 of $1,000). In the second year, you earn 20% on $1,200 (your original principal plus the first year’s interest), which is $240. This seemingly small fractional increase each year leads to exponential growth over time.
Without a solid grasp of how percentages (and thus fractions) work, the concept of compound interest remains abstract. But by seeing it as a repeated fractional multiplication, one can visualize the accelerating growth curve. This insight is crucial for understanding the long-term benefits of early saving and investing, the costs of carrying debt, and the financial implications of delaying financial planning. It underscores why even a seemingly simple mathematical concept like “20 in fraction” can unlock profound financial wisdom.
Empowering Financial Decisions with Fractional Understanding
Ultimately, the goal of financial literacy is to empower individuals to make sound financial decisions that lead to security, growth, and independence. Understanding fractions and percentages is not just academic; it’s a practical skill that translates directly into better financial outcomes.
Strategic Saving: Visualizing Your Wealth Accumulation
When you decide to save 20% of your paycheck, you are essentially dedicating one-fifth of your earnings to future wealth accumulation. This fractional commitment becomes a powerful mental model. You can visualize your savings growing incrementally with each paycheck. This makes setting and achieving savings goals more concrete. Whether it’s saving for a down payment on a house (a fraction of its total cost), retirement (a fraction of your working life’s income), or an emergency fund (a fraction of your monthly expenses), fractional thinking helps you break down large financial aspirations into manageable, measurable steps. It allows you to see the progress in terms of parts of a whole, motivating you to stay on track.
Managing Debt: Breaking Down the Repayment Journey
Debt can be overwhelming, but fractional understanding provides a roadmap for managing it. When you have a loan with a 20% interest rate, you know that a significant portion (one-fifth) of your payments will go towards interest rather than the principal, especially in the early stages. This awareness can motivate you to pay down high-interest debt aggressively. Similarly, understanding what fraction of your income is consumed by debt payments (e.g., 20% of your monthly income goes to credit card payments) highlights the impact on your disposable income and can spur you to seek strategies for reduction. Debt snowball or avalanche methods, for instance, are essentially fractional strategies to prioritize and eliminate portions of your debt.
Assessing Financial Products and Making Informed Choices
From comparing different credit card offers with varying interest rates to evaluating investment funds with different expense ratios, fractional understanding is your compass. A financial advisor might present a complex investment strategy, but being able to break down its components into percentages or fractions of your portfolio allows you to grasp its implications. You can question why a certain fraction of your portfolio is allocated to a particular asset or understand the real cost of a financial service presented in seemingly small percentages. This critical perspective transforms you from a passive recipient of financial advice into an active, informed decision-maker, capable of scrutinizing options and choosing those that best align with your financial goals and risk tolerance.
In conclusion, while “what is 20 in fraction?” may appear to be a trivial mathematical question, its true significance in the financial realm cannot be overstated. From the simplest budgeting decisions to the most complex investment strategies, the ability to think in terms of fractions and percentages is an indispensable skill. It demystifies financial concepts, empowers informed decision-making, and ultimately paves the way for greater financial literacy and economic well-being. By embracing this fundamental mathematical concept, individuals can gain the confidence and clarity needed to navigate their financial journey successfully.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.