
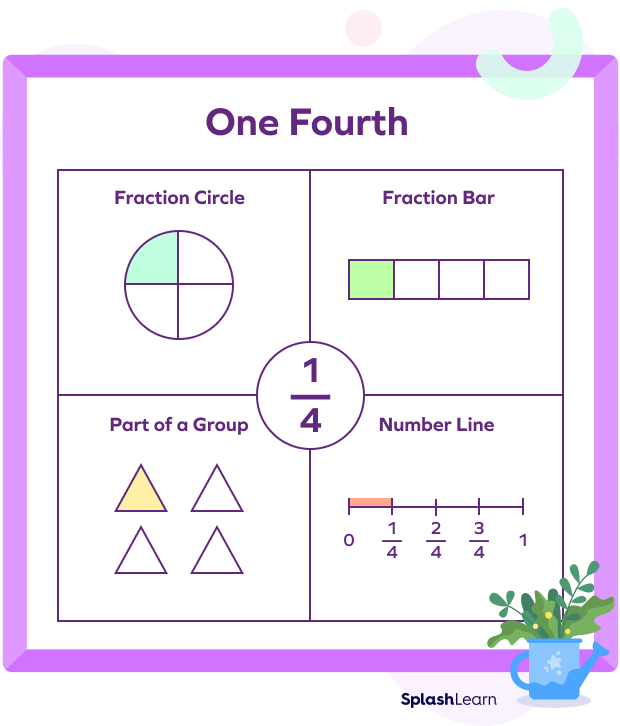
In mathematics, 1/4th is simply a fraction – a quarter, one part of four equal divisions. But in the intricate world of finance, this seemingly simple fraction transcends its numerical definition, evolving into a powerful benchmark, a strategic allocation, and a fundamental principle that can shape personal wealth, investment portfolios, and business success. Far from being an abstract concept, “a quarter” in financial terms represents a tangible segment with profound implications, dictating everything from budget allocations and investment diversification to corporate reporting cycles and strategic financial planning.
Understanding “what is 1/4th” in a monetary context is to unlock a critical lens through which to view your financial decisions. It’s about recognizing the outsized impact that 25% can have, whether it’s 25% of your income saved, 25% of your portfolio allocated to a specific asset class, or the 25% market share a company commands. This article will delve into the multifaceted role of 1/4th in personal finance, investing, and business, illustrating how embracing this concept can lead to more disciplined management, strategic growth, and ultimately, greater financial prosperity.
Beyond the Fraction: 1/4th as a Financial Benchmark
The concept of a quarter permeates the financial landscape, appearing in various forms and serving as a critical unit of measure for performance, progress, and planning. It’s more than just a mathematical operation; it’s a conceptual framework that helps individuals and institutions organize, analyze, and optimize their financial endeavors.
The Ubiquitous Quarter in Finance: Budgeting, Investing, Reporting
From the moment we begin managing our money, the idea of a quarter implicitly or explicitly guides our decisions. In personal budgeting, the 50/30/20 rule, a popular guideline for income allocation, suggests dedicating 20% (very close to 1/4th) to savings and debt repayment. Other strategies might advocate for a fixed 25% of disposable income to be channeled directly into investment vehicles. For homeowners, the recommendation that housing costs should not exceed 25-30% of gross income is another prime example of the quarter’s influence.
In the realm of investing, a quarter often defines diversification strategies. An investor might decide to allocate 25% of their portfolio to equities, 25% to bonds, 25% to real estate, and 25% to alternative assets to achieve a balanced risk profile. This strategic slicing of a portfolio into quarters is a foundational element of modern portfolio theory, aiming to mitigate risk while optimizing returns.
Perhaps most prominently, the financial world operates on a quarterly cycle. Companies report their earnings every three months (a quarter of a year), providing investors with crucial insights into their performance, growth, and profitability. Economic data, from GDP growth to unemployment rates, is frequently analyzed on a quarterly basis, offering snapshots of the broader economic health. This standardized reporting structure makes “a quarter” a fundamental unit for performance evaluation and future forecasting.
Shifting Perception: From Math to Monetary Strategy
The journey from viewing 1/4th as a simple fraction to recognizing it as a powerful monetary strategy requires a shift in mindset. It’s about understanding that every dollar, every investment, every financial decision, contributes to a larger whole, and that a quarter of that whole can represent a significant, often decisive, portion. This perception shift encourages a more intentional and disciplined approach to financial management. Instead of seeing your income as a single lump sum, you begin to see it as divisible segments, each with a specific purpose. This segmentation, often in quarters, facilitates clearer goal setting, easier tracking, and more effective course correction. It transforms an abstract numerical concept into a practical, actionable framework for building and preserving wealth.
Budgeting with Precision: The 1/4th Allocation Principle
One of the most immediate and impactful applications of the “1/4th” principle is in personal budgeting. By consciously allocating a quarter of your financial resources towards specific goals, you can build a robust foundation for financial security and future prosperity. This isn’t about rigid deprivation but about smart, strategic distribution.
The 25% Rule: A Foundation for Financial Health
While rules of thumb vary, dedicating a specific quarter of your income to critical financial areas can dramatically improve your financial health. For instance, committing 25% of your net income to savings and investments is an ambitious yet achievable goal for many, accelerating wealth accumulation significantly. This 25% isn’t just for a rainy day; it’s for retirement, a down payment on a home, funding a child’s education, or building an emergency fund. The consistency of setting aside this quarter empowers exponential growth over time, thanks to the magic of compounding.
Alternatively, some budget models focus on capping certain expenses to a quarter of your income. For example, keeping housing costs (rent/mortgage, taxes, insurance) below 25-30% of your gross income prevents you from becoming “house poor,” freeing up funds for other financial priorities. Similarly, if 25% of your income is consistently being eaten up by high-interest debt payments, it’s a stark indicator that a significant financial recalibration is needed. The “25% rule” acts as a powerful diagnostic tool and a guiding principle for maintaining fiscal equilibrium.
Identifying Your “Quarter” Commitments: Housing, Savings, Debt Reduction
To effectively apply the 1/4th principle, you must identify where your “quarters” are going. Start by analyzing your income and expenses. Are you dedicating a quarter to essential living costs, another quarter to debt repayment, a third quarter to discretionary spending, and a fourth quarter to savings and investments? Or are some quarters disproportionately large, signaling an imbalance?
-
Housing: As mentioned, housing often consumes a significant quarter (or more) of an individual’s income. Understanding this allocation is crucial for deciding on affordability and location.
-
Savings & Investments: This quarter is arguably the most vital for long-term wealth creation. It’s the engine that drives financial independence.
-
Debt Reduction: If you’re carrying significant debt, dedicating a specific quarter to aggressively paying it down can free up future cash flow and reduce interest burden.
-
Discretionary Spending: This quarter often covers lifestyle choices – entertainment, dining out, hobbies, and travel. While important for quality of life, it’s also the most flexible quarter for adjustments.
By categorizing your spending into these conceptual quarters, you gain clarity and control, allowing you to reallocate resources strategically to align with your financial goals.
The Impact of a Single Quarter: Compounding Your Savings
The true power of allocating a quarter of your income to savings and investments lies in the principle of compounding. It’s not just about the amount you save today, but what that amount earns over time, and what those earnings then earn. Setting aside even a modest 25% consistently each pay period, and investing it wisely, can lead to substantial wealth accumulation.
Imagine investing $1,000 every quarter (roughly $333 per month) into an account earning an average of 7% annual returns. After 10 years, you would have contributed $40,000, but your money would have grown to over $57,000. After 30 years, your total contributions would be $120,000, but your investment could be worth upwards of $400,000. This exponential growth is the direct result of consistently committing “a quarter” of your financial capacity over the long term, demonstrating that small, regular contributions can yield extraordinary results.
Strategic Investing: Diversifying with a Quarter Slice
In the volatile world of investing, the concept of 1/4th is indispensable for managing risk, optimizing returns, and making informed decisions. It influences how portfolios are constructed, how performance is measured, and how opportunities are evaluated.
Portfolio Allocation: Balancing Risk and Reward with 25% Tranches
Modern portfolio theory emphasizes diversification as a key strategy to mitigate risk without sacrificing potential returns. This often involves dividing an investment portfolio into various asset classes, with “quarters” frequently serving as guiding allocations. For example, a moderately aggressive investor might aim for a portfolio that is 25% in large-cap stocks, 25% in small-cap stocks, 25% in international equities, and 25% in fixed-income securities or real estate. This balanced approach ensures that if one sector or asset class underperforms, the impact on the overall portfolio is limited.
The 25% allocation isn’t a rigid rule, but a flexible guideline. It forces investors to think critically about how much exposure they have to different market segments and risk profiles. For instance, younger investors with a longer time horizon might allocate a higher “quarter” to growth-oriented assets, while those nearing retirement might shift a larger quarter into more conservative, income-generating investments. The ability to rebalance these quarters periodically is also crucial, ensuring the portfolio remains aligned with financial goals and risk tolerance.
The Power of Incremental Growth: Quarterly Contributions and Rebalancing
Just as with personal savings, consistent quarterly contributions to an investment portfolio can harness the power of dollar-cost averaging. By investing a fixed amount every three months, you buy more shares when prices are low and fewer when prices are high, averaging out your purchase price over time and reducing the risk of making a single, poorly timed investment. This disciplined approach prevents emotional decision-making and fosters steady, incremental growth.
Furthermore, quarterly rebalancing is a critical task for maintaining a target asset allocation. If, for example, your equity quarter has surged in value and now represents 35% of your portfolio, while your bond quarter has lagged, you would sell a portion of your equities and buy more bonds to bring both back to their target 25% allocation. This systematic approach ensures that your risk exposure remains consistent with your financial plan and forces you to “buy low and sell high” (or at least trim the winners and add to the laggards).
Understanding Quarterly Reports: A Window into Corporate Health
For stock investors, understanding “what is 1/4th” is paramount when analyzing company performance. Publicly traded companies are legally obligated to release financial reports every quarter (Form 10-Q in the U.S.), detailing their revenues, expenses, profits, and cash flows for that three-month period. These quarterly reports are a treasure trove of information, providing investors with timely updates on a company’s operational efficiency, market position, and overall financial health.
Savvy investors don’t just look at the current quarter’s numbers in isolation. They compare them to previous quarters (quarter-over-quarter growth) and to the same quarter in the previous year (year-over-year growth) to identify trends, seasonality, and long-term trajectory. A company consistently growing its revenue and earnings by a significant quarter (e.g., 25%) year-over-year is often a strong indicator of robust performance and potential for future appreciation. Conversely, a consistent decline of 25% in key metrics quarter after quarter signals deep-seated problems.
Business & Entrepreneurship: The Quarter in Commercial Ventures
Beyond personal finance and investing, the concept of 1/4th plays a pivotal role in the operational and strategic aspects of businesses, from ownership structures to performance management.
Equity and Ownership: The Significance of a 25% Stake
In the world of entrepreneurship and business, owning “a quarter” (25%) of a company is often a highly significant milestone. While not a majority stake, a 25% ownership typically confers substantial influence and often veto power over major corporate decisions, especially if the remaining ownership is fragmented. It can signify a crucial partnership, a substantial seed investment, or the equity awarded to a key co-founder. For many startups, securing an investor who takes a 25% stake provides essential capital and strategic guidance, while still leaving the founders with majority control (or at least significant collective influence). Understanding the rights and responsibilities associated with a 25% equity stake is critical for both investors and founders.
Quarterly Performance Metrics: Driving Business Decisions
For businesses, the quarter is the fundamental unit of performance measurement and strategic planning. Sales targets are set quarterly, marketing campaigns are often launched and evaluated on a quarterly cycle, and operational efficiencies are continually assessed over three-month periods. These quarterly reviews allow businesses to:
-
Track Progress: Are we on track to meet our annual goals?
-
Identify Trends: Are sales increasing or decreasing quarter-over-quarter?
-
Make Adjustments: If a marketing strategy isn’t yielding results, can we pivot in the next quarter?
-
Allocate Resources: Which departments or projects need more funding for the upcoming quarter?
The ability to analyze performance in 1/4th segments allows for agility and responsiveness, enabling businesses to adapt quickly to changing market conditions and customer demands.
Strategic Planning: Focusing on Quarterly Milestones
Long-term business visions are often broken down into actionable quarterly milestones. A five-year strategic plan, for example, might be distilled into 20 distinct quarterly objectives. This approach makes large, ambitious goals feel more manageable and provides regular checkpoints for evaluation. Each quarter becomes a mini-campaign, with specific deliverables, budgets, and teams assigned to achieve a fraction of the overall vision. For startups, reaching certain “quarterly numbers” (e.g., 25% user growth, 25% revenue increase) can be critical for securing subsequent rounds of funding, demonstrating traction and viability to potential investors.
Mastering Your Financial “Quarters”: A Blueprint for Prosperity
The journey to financial mastery is not about grand, sweeping gestures but about consistent, disciplined actions, often measured in quarters. From your daily spending habits to your long-term investment strategy, the concept of 1/4th provides a powerful, practical framework for making informed decisions and building sustainable wealth.
Practical Steps to Integrate the 1/4th Mindset
To harness the power of the quarter in your financial life, consider these actionable steps:
-
Budget by Quarters: Start by dividing your net income into conceptual quarters. For example, 50% for needs, 25% for wants, and 25% for savings/debt repayment. Adjust these percentages to fit your unique situation, but maintain the disciplined segmentation.
-
Automate Your Savings: Set up automatic transfers each payday to move a dedicated “quarter” of your income directly into a savings or investment account. This removes the temptation to spend it.
-
Review Quarterly: Schedule a quarterly financial review. Check your budget, analyze your investments, review your debt progress, and adjust your goals as needed. This regular checkpoint ensures you stay on track.
-
Diversify with Intent: If you’re investing, consciously think about your portfolio in quarters. Are you adequately diversified across different asset classes? Do you need to rebalance to maintain your target allocations?
-
Set Quarterly Goals: Break down large financial goals (e.g., saving for a down payment, paying off a student loan) into smaller, achievable quarterly milestones. This makes the journey less daunting and provides a sense of accomplishment with each completed quarter.

The Long-Term Vision: Quarter by Quarter Progress
True financial prosperity is rarely achieved overnight. It is the culmination of countless small, consistent decisions made over time. By embracing the “1/4th” mindset, you commit to a disciplined, strategic approach that acknowledges the power of incremental progress. Each quarter becomes an opportunity to refine your budget, optimize your investments, reduce your debt, and move closer to your long-term financial aspirations.
Whether it’s the 25% of your income you save, the 25% of your portfolio you allocate to a specific growth sector, or the quarterly reports that guide your investment decisions, the humble fraction of “1/4th” is a cornerstone of intelligent financial management. By understanding and strategically applying its principles, you empower yourself to build a resilient financial future, one quarter at a time.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.