
In the intricate world of personal and business finance, numbers tell a story. But raw numbers alone often lack the context needed for truly insightful decision-making. This is where percentages step in, transforming absolute values into relatable proportions and growth metrics. Understanding “how to get percent of two numbers” isn’t just a mathematical exercise; it’s a vital skill that underpins everything from budgeting your household income to evaluating complex investment opportunities. Without a firm grasp of percentages, navigating financial landscapes can feel like sailing without a compass.
From analyzing interest rates on a loan, calculating discounts during a sale, to understanding the return on investment for your portfolio, percentages provide clarity, comparability, and a universal language for financial performance. They allow us to see not just what happened, but by how much and in proportion to what. This article will demystify percentage calculations, placing them squarely within the context of money management, investing, and business finance, ensuring you can leverage this powerful tool to make smarter financial choices.
The Indispensable Role of Percentages in Personal Finance
Personal finance is the bedrock of individual wealth and stability, and percentages are its foundational language. Every decision, from daily spending to long-term savings, benefits from a clear understanding of proportional relationships.
Budgeting and Expense Tracking: Understanding Your Spending Ratios
A budget is more than just a list of income and expenses; it’s a strategic allocation of your financial resources. Percentages allow you to visualize where your money truly goes, helping you identify areas for optimization. For instance, if your rent is $1,500 and your monthly income is $5,000, you can calculate that your rent consumes (1500 / 5000) * 100 = 30% of your income. This simple calculation helps you align with budgeting rules like the 50/30/20 rule (50% for needs, 30% for wants, 20% for savings/debt repayment) or customize your own spending ratios. Tracking expenses as a percentage of your total income provides an immediate, digestible snapshot of your financial health, making it easier to spot overspending in categories like dining out or entertainment. It shifts the focus from raw dollar amounts, which can vary wildly with income, to proportional impact, which offers more consistent insight into your financial habits.
Savings and Debt Management: Progressing Towards Financial Freedom
Whether you’re aggressively paying down debt or diligently building an emergency fund, percentages are crucial for tracking progress and motivation. Imagine you have a $10,000 credit card debt and pay off $500 in a month. You’ve reduced your debt by (500 / 10000) * 100 = 5%. This concrete percentage shows tangible progress, keeping you engaged in your financial goals. Similarly, if you aim to save 20% of every paycheck, calculating this percentage helps ensure you hit your target consistently. For debt, understanding the annual percentage rate (APR) is paramount; it tells you the true cost of borrowing and helps prioritize which debts to tackle first, usually those with the highest APR. Comparing interest rates on different savings accounts, loans, or mortgages is solely done through percentages, enabling informed decisions about where to park your money or secure financing.
Understanding Discounts, Sales, and Price Changes: Maximizing Your Buying Power
From holiday sales to clearance racks, retail environments are rife with percentages. A “25% off” sale means you’re saving a quarter of the original price. Knowing how to quickly calculate that discount in your head or with a calculator allows you to instantly determine the final price and assess the true value of the deal. If an item costs $80 and is 25% off, you save (25 / 100) * 80 = $20, meaning you pay $60. This skill extends beyond simple discounts; it’s essential for understanding price increases, inflation, and even currency exchange rate fluctuations, all of which impact your purchasing power and budget. Being adept at these calculations empowers you to make smarter consumer choices and avoid overpaying.
Tax Implications and Withholdings: Navigating Your Earnings
Taxes are an unavoidable part of financial life, and they are almost universally expressed as percentages. Income tax rates, sales tax, property tax rates, and capital gains tax rates all dictate how much of your earnings or assets go to the government. Understanding your effective tax rate – the actual percentage of your total income you pay in taxes – provides a clearer picture than just looking at your tax bracket. Furthermore, your payroll withholdings for income tax, social security, and Medicare are calculated as percentages of your gross pay. Being able to verify these calculations helps ensure accuracy and allows for informed adjustments, such as modifying your W-4 form to optimize your take-home pay versus your tax refund.
Percentages in the World of Investing and Wealth Growth
Investing is inherently quantitative, and percentages are the primary language used to measure performance, risk, and diversification. Without them, comparing different investment opportunities would be nearly impossible.
Calculating Investment Returns: ROI, Annualized Gains, and Losses
The most common application of percentages in investing is the calculation of returns. Return on Investment (ROI) is a fundamental metric that measures the profitability of an investment. If you invest $1,000 and it grows to $1,200, your gain is $200. Your ROI is (200 / 1000) * 100 = 20%. This provides a clear, comparable metric across different investments, regardless of their initial cost. Beyond simple ROI, investors often look at annualized returns, which adjust the return to a yearly basis, allowing for comparison of investments held for different durations. Understanding percentage gains and losses is critical for assessing portfolio performance, making rebalancing decisions, and setting realistic expectations for future growth.
Understanding Interest Rates: Loans, Savings Accounts, and Credit Cards
Interest rates are almost exclusively expressed as percentages and are central to both borrowing and saving. When you take out a loan, the annual interest rate (APR) determines the cost of borrowing. A 5% interest rate on a $10,000 loan means you’ll pay $500 in interest for that year (excluding compounding effects for simplicity). Conversely, a savings account or certificate of deposit (CD) offers an Annual Percentage Yield (APY), which tells you the percentage return you’ll earn on your deposits. For credit cards, understanding variable interest rates and how they impact your balance is crucial for avoiding escalating debt. Comparing these percentages allows investors to seek the highest returns on their savings while minimizing the costs of their loans.
Diversification and Asset Allocation: Structuring Your Portfolio
A cornerstone of sound investing is diversification – spreading investments across different asset classes (stocks, bonds, real estate, etc.) to mitigate risk. Asset allocation is the process of deciding what percentage of your portfolio to dedicate to each class. For example, a common rule of thumb suggests that your stock allocation should be roughly “100 minus your age” as a percentage. So, a 30-year-old might allocate 70% of their portfolio to stocks and 30% to bonds. These percentages are dynamic and should be rebalanced periodically to maintain the desired risk profile. Without understanding and applying these percentages, investors risk an imbalanced portfolio that is either too conservative or too aggressive for their financial goals and risk tolerance.
Inflation and Purchasing Power: The Hidden Cost of Waiting
Inflation is the rate at which the general level of prices for goods and services is rising, and subsequently, purchasing power is falling. It is always expressed as a percentage. If inflation is 3% annually, it means that what cost $100 last year now costs $103. This percentage directly impacts the real return on your investments and the value of your savings. Understanding inflation percentages helps investors set realistic return expectations and choose investments that are likely to outpace inflation, thereby preserving and growing their real wealth over time. It highlights the importance of not letting money sit idle, as its purchasing power diminishes with each passing year due to inflationary pressures.
Business Finance: Leveraging Percentages for Profitability and Growth
For businesses, from startups to multinational corporations, percentages are more than just metrics; they are essential tools for strategic planning, operational efficiency, and evaluating overall financial health.
Profit Margins: Gross, Operating, and Net Profit Analysis
Profit margins are among the most critical percentages in business finance, offering a quick snapshot of a company’s profitability at different stages.
-
Gross Profit Margin: (Gross Profit / Revenue) * 100. This tells you how much profit a company makes from its sales after accounting for the direct costs of production. A high gross margin indicates efficient production.
-
Operating Profit Margin: (Operating Income / Revenue) * 100. This shows how much profit a company makes from its core operations before interest and taxes. It reflects operational efficiency.
-
Net Profit Margin: (Net Income / Revenue) * 100. This is the ultimate measure of profitability, indicating what percentage of revenue is left after all expenses, including taxes and interest, have been paid.
Analyzing these margins over time and comparing them to industry benchmarks helps businesses identify strengths, weaknesses, and areas for improvement, such as cost cutting or pricing adjustments.
Sales Growth and Market Share: Measuring Business Performance
Businesses thrive on growth, and percentages are the standard for measuring it.
-
Sales Growth Rate: ((Current Period Sales – Previous Period Sales) / Previous Period Sales) * 100. This percentage indicates how rapidly a company’s sales are increasing or decreasing. Positive growth is a sign of a healthy, expanding business.
-
Market Share: (Company Sales / Total Market Sales) * 100. This percentage reveals a company’s portion of the total sales within its industry. Increasing market share is often a strategic goal, indicating competitive advantage and market dominance.
These percentages are crucial for setting sales targets, evaluating marketing effectiveness, and understanding a company’s competitive position within its industry.
Discounting and Pricing Strategies: Optimizing Revenue

Setting the right price for products and services is an art and a science, heavily reliant on percentages. Businesses often employ various discounting strategies – offering 10% off for first-time customers, 20% off for bulk purchases, or seasonal sales. Calculating the impact of these discounts on revenue and profit margins is essential. Furthermore, understanding the “cost-plus” pricing method often involves adding a target profit margin (e.g., 30%) to the cost of goods to determine the selling price. Sensitivity analysis, which examines how changes in pricing percentages affect sales volume and total revenue, is a critical component of strategic pricing decisions.
Financial Ratios: Quick Insights into Company Health
Financial ratios are a set of percentages derived from a company’s financial statements that provide quick, insightful metrics into its health, efficiency, and solvency.
-
Debt-to-Equity Ratio: (Total Debt / Shareholder Equity) * 100. This percentage indicates the proportion of equity and debt used to finance a company’s assets. A higher ratio might signal higher risk.
-
Current Ratio: (Current Assets / Current Liabilities) * 100. While not strictly a percentage, it’s often interpreted in percentage terms or compared against a benchmark (e.g., a current ratio of 2:1, meaning current assets are 200% of current liabilities, is often considered healthy). It measures a company’s ability to pay off its short-term obligations.
-
Inventory Turnover Ratio: (Cost of Goods Sold / Average Inventory). This tells you how many times a company has sold and replaced inventory during a period, often expressed as a percentage of the total inventory value.
These ratios, and many others, provide stakeholders (investors, lenders, management) with a concise, comparative view of a company’s financial performance and risk profile.
Demystifying the Math: How to Calculate Percentages Effectively
While the applications are vast, the underlying mathematical principles for calculating percentages are straightforward. Mastering these basics will empower you to apply them across all financial scenarios.
The Basic Formula: Part/Whole * 100
The core of any percentage calculation involves two numbers: the “part” and the “whole.”
Percentage = (Part / Whole) * 100
- Example: If you spent $300 on groceries (the part) from your $2,000 monthly income (the whole), your grocery spending is ($300 / $2,000) * 100 = 15%.
This formula helps you express any component as a proportion of a larger total.
Finding a Percentage of a Number: The “Of” Means Multiply
Often, you’ll need to find what a certain percentage of a number is. The word “of” in this context mathematically means multiplication. First, convert the percentage into a decimal by dividing it by 100.
Amount = (Percentage / 100) * Whole Number
-
Example: You want to calculate a 15% tip on a $60 restaurant bill.
-
Convert 15% to a decimal: 15 / 100 = 0.15
-
Multiply by the whole: 0.15 * $60 = $9.
-
So, your tip is $9.
-
This is useful for calculating discounts, sales tax, commissions, or interest payments.
Calculating Percentage Increase or Decrease: Measuring Change Over Time
Measuring change over time is crucial for tracking financial progress, market movements, or business growth.
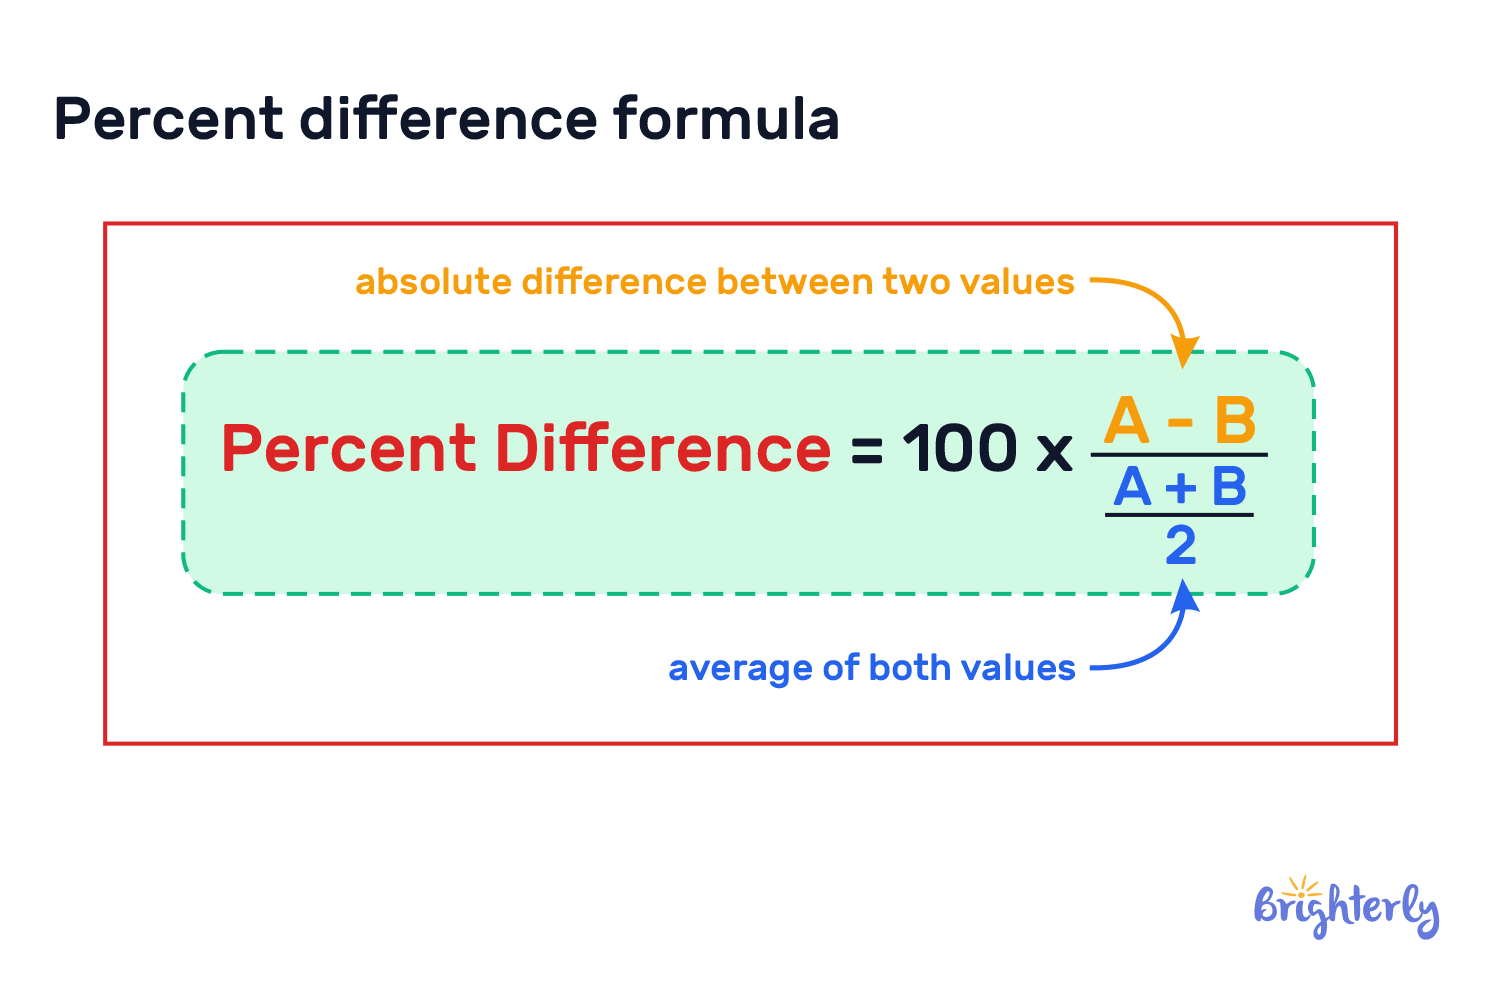
Percentage Change = ((New Value – Old Value) / Old Value) * 100
-
Example (Increase): Your investment grew from $5,000 to $5,500.
-
Change = $5,500 – $5,000 = $500
-
Percentage Increase = ($500 / $5,000) * 100 = 10%.
-
-
Example (Decrease): The value of a stock dropped from $120 to $108.
-
Change = $108 – $120 = -$12 (the negative indicates a decrease)
-
Percentage Decrease = (-$12 / $120) * 100 = -10% (or a 10% decrease).
-
This formula is indispensable for analyzing investment performance, inflation rates, sales growth, and personal income changes.
Practical Applications: Examples in Everyday Financial Scenarios
Let’s put it all together with a few quick examples:
-
Sales Tax: If you buy an item for $50 and the sales tax is 8%, the tax amount is (8 / 100) * $50 = $4. Your total is $54.
-
Rent as a Portion of Income: Your rent is $1,800, and your gross monthly income is $6,000. Your rent is ($1,800 / $6,000) * 100 = 30% of your income.
-
Investment Loss Recovery: If your stock drops by 20% (e.g., from $100 to $80), it doesn’t mean it needs to increase by 20% to get back to $100. It needs to increase by (($100 – $80) / $80) * 100 = 25% from its new lower value. This illustrates the importance of understanding the base for percentage calculations.
Tools and Tips for Accurate Percentage Calculations
While the underlying math is simple, efficiency and accuracy are key in financial applications. Leveraging the right tools and being mindful of common pitfalls can save you time and prevent costly errors.
Utilizing Spreadsheets (Excel/Google Sheets) for Automation
For anything beyond a one-off calculation, spreadsheets like Microsoft Excel or Google Sheets are indispensable. They allow you to set up formulas once and apply them across vast datasets, automating percentage calculations.
-
Basic Percentage: If cell A2 contains the “part” and B2 contains the “whole,” you can simply type
= (A2/B2)*100into cell C2 to get the percentage. -
Percentage of a Number: If A2 has the percentage (e.g., 15) and B2 has the whole number (e.g., 60), you can use
= (A2/100)*B2. -
Percentage Change: If A2 is the old value and B2 is the new value, use
= ((B2-A2)/A2)*100.
Spreadsheets are particularly powerful for budgeting, investment tracking, and business financial analysis, allowing for quick adjustments and scenario planning.
Financial Calculators and Online Tools
Beyond basic calculators, dedicated financial calculators (both physical and online) are invaluable. Many online percentage calculators can perform specific functions like calculating percentage increase/decrease, finding what percentage one number is of another, or adding/subtracting a percentage. For more complex financial calculations like loan amortizations or future value of investments, specialized financial calculators often have built-in functions that utilize percentages behind the scenes. These tools simplify complex calculations and reduce the chance of manual errors.
Common Pitfalls and How to Avoid Them
Even seasoned professionals can stumble with percentage calculations if not careful.
-
Incorrect Base: This is the most frequent error. Always ensure you are dividing by the correct “whole” or “old value.” As seen in the investment loss example, a 20% drop requires a 25% gain from the new lower value to recover. The base number matters significantly.
-
Rounding Errors: Rounding too early in multi-step calculations can lead to significant inaccuracies, especially in large financial sums. It’s best to retain precision until the final step.
-
Misinterpreting “Percentage Points” vs. “Percentage Change”: If an interest rate goes from 5% to 6%, that’s a 1 percentage point increase. However, the percentage change in the rate itself is ((6-5)/5)*100 = 20%. Understanding this distinction is crucial for clear communication in finance.
-
Decimal vs. Percentage Format: Remember to convert percentages to decimals (divide by 100) before multiplying them in formulas, and to multiply by 100 if you want to express a decimal as a percentage.
By being mindful of these pitfalls and utilizing the appropriate tools, you can ensure your percentage calculations are consistently accurate and reliable.

Conclusion
The ability to accurately calculate and interpret percentages is not merely an academic exercise; it is a critical life skill that empowers individuals and businesses alike to make informed financial decisions. From the granular details of personal budgeting and debt repayment to the expansive horizons of investment analysis and corporate strategy, percentages provide the context, clarity, and comparability needed to navigate the complexities of the monetary world.
By mastering the basic formulas for finding a percentage of two numbers, calculating percentage increases and decreases, and understanding their practical applications across personal finance, investing, and business operations, you unlock a deeper understanding of financial dynamics. Armed with this fundamental knowledge and leveraging modern tools like spreadsheets, you are better equipped to manage your money effectively, grow your wealth strategically, and ultimately achieve greater financial success. In finance, numbers truly speak volumes, and percentages are their most eloquent expression.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.