
At first glance, the question “what is 1/4 of 1/3?” appears to be a simple arithmetic problem, a relic from elementary school mathematics. The answer, a straightforward 1/12, might seem trivial. However, within the intricate landscape of finance, this seemingly basic calculation unlocks a powerful framework for understanding complex financial concepts, making informed decisions, and navigating the nuances of personal wealth management, investing, and business finance. Far from being merely academic, comprehending fractional relationships is fundamental to dissecting everything from investment portfolio allocations and real estate ownership structures to budgeting strategies and risk assessment. It teaches us how to break down large, intimidating financial challenges into manageable, proportional pieces, revealing the underlying mechanics of monetary flow and value distribution.
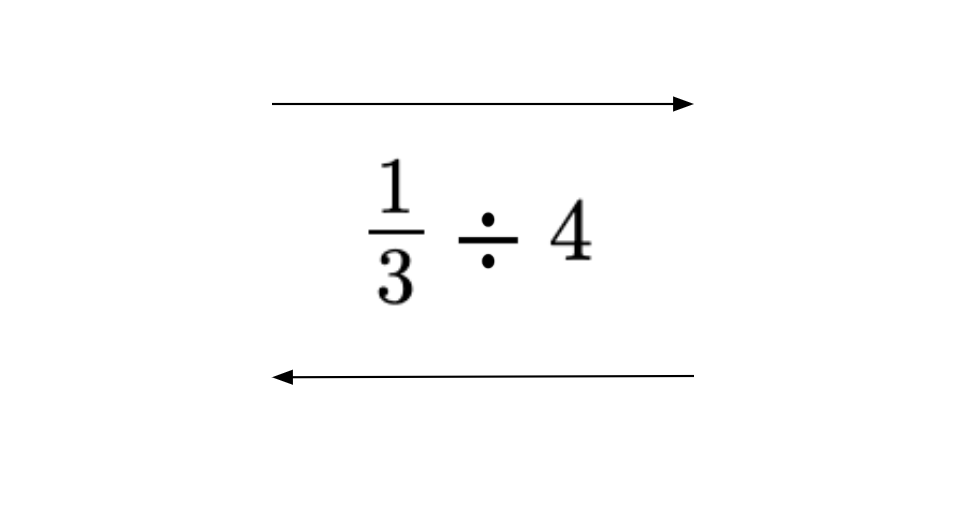
The Foundational Math Behind Financial Proportions
The ability to work with fractions is more than just a mathematical skill; it’s a foundational element of financial literacy. In a world where financial instruments, ownership stakes, and distribution models are rarely whole, understanding how to calculate a “part of a part” is indispensable.
Deciphering the Core Calculation: 1/4 of 1/3
Let’s begin with the explicit calculation. To find “1/4 of 1/3,” we multiply the two fractions:
1/4 × 1/3 = (1 × 1) / (4 × 3) = 1/12
This result signifies that if you take a whole, divide it into three equal parts, and then take one of those parts (1/3), and subsequently divide that part into four equal pieces, the portion you now hold is 1/12 of the original whole. While mathematically simple, this concept finds deep resonance in various financial scenarios, allowing for precise quantification of smaller interests within larger holdings or distributions. It’s the simplest expression of how one proportion can further subdivide another, creating a new, smaller proportion relative to the original whole.
Why Basic Fractions Are Indispensable in Financial Literacy
The elegance of fractions lies in their ability to represent proportional relationships concisely. In finance, these relationships are everywhere:
-
Percentages: Often, fractions are easily converted to percentages (e.g., 1/4 = 25%, 1/3 = 33.33%, 1/12 = 8.33%). These percentages form the basis of interest rates, returns on investment, tax rates, and budget allocations.
-
Ratios: Financial ratios (like debt-to-equity or current ratios) are essentially comparisons expressed as fractions, providing critical insights into a company’s health or an individual’s financial standing.
-
Distributions: Profits, losses, dividends, and inherited assets are frequently distributed in fractional shares among stakeholders.
-
Allocations: Investment portfolios are constructed by allocating various fractions of capital to different asset classes, sectors, or individual securities.
Understanding fractions allows an individual to move beyond just the numbers and grasp the underlying proportional impact of various financial decisions. It provides a more intuitive grasp of how changes in one part of a financial system affect the whole, enabling more robust planning and forecasting.
Fractional Ownership and Investment Strategies
One of the most direct and impactful applications of “1/4 of 1/3” thinking in finance is in the realm of ownership and investment. Modern investment landscapes increasingly offer opportunities for individuals to own slices of assets rather than the entire entity.
Real Estate Syndication: Owning a Piece of the Pie
Real estate syndication is a prime example. Here, multiple investors pool their capital to acquire larger, often commercial, properties that would be unattainable for a single individual. Let’s say a syndication owns a large office building. Investor A might own 1/4 of the entire syndication fund. If that fund, in turn, owns 1/3 of the office building outright (perhaps through a joint venture with another fund), then Investor A effectively owns:
1/4 (of the fund) × 1/3 (of the building) = 1/12 of the office building.
This calculation is critical for determining Investor A’s share of profits, rental income, appreciation, and even potential liabilities. Without this fractional understanding, investors might misinterpret their true exposure and potential returns, highlighting the need for clarity in complex ownership structures.
Diversifying Portfolios: Allocating Capital Across Asset Classes
Diversification is a cornerstone of sound investment strategy, aiming to reduce risk by spreading investments across various asset types. Fractional thinking is at the heart of this process. An investor might decide to allocate 1/4 of their entire portfolio to bonds. Within that bond allocation, they might further decide that 1/3 of those bonds should be in municipal bonds, known for their tax advantages.
Therefore, the portion of their total portfolio dedicated to municipal bonds would be:
1/4 (of total portfolio in bonds) × 1/3 (of bonds in municipal bonds) = 1/12 of the total portfolio.
This granular approach allows investors to fine-tune their exposure to different market segments, manage risk, and align their portfolio with specific financial goals and risk tolerance. It demonstrates how layered decisions about asset allocation are fundamentally fractional calculations.
The Rise of Micro-Investing and Fractional Shares
The advent of micro-investing platforms has made it possible for individuals to invest in “fractional shares” of high-priced stocks, ETFs, and even alternative assets like fine art or rare collectibles. Instead of needing enough capital to buy an entire share of a company like Amazon or Google, an investor can purchase a portion, perhaps as little as $5 worth. While the “1/4 of 1/3” directly applies less to buying a fraction of a single share (you just buy 1/X of a share), the spirit of fractional thinking is identical. It democratizes access to investments by allowing smaller, proportional investments in assets that were once exclusive to those with significant capital. This fosters a mindset where every dollar, no matter how small, can be a part of a larger investment strategy, accumulating wealth over time through consistent, albeit fractional, contributions.
Budgeting, Savings, and Income Distribution
Beyond investments, fractional thinking is indispensable for personal finance, particularly in budgeting and savings. It provides a structured way to allocate income and manage expenses effectively.
The Anatomy of a Budget: Allocating Your Income
Budgeting is essentially the art of allocating fractions of your income to different categories. A popular rule is the 50/30/20 rule: 50% for needs, 30% for wants, and 20% for savings/debt repayment. This is a direct application of fractional allocation.
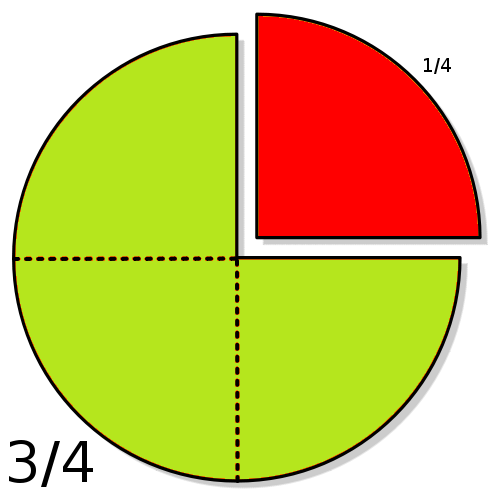
Let’s apply our “1/4 of 1/3” logic. Imagine you’ve allocated 1/4 of your discretionary “wants” budget to entertainment. Within that entertainment budget, you decide that 1/3 of it will be specifically for dining out. The actual portion of your total “wants” budget that goes to dining out is:
1/4 (of wants for entertainment) × 1/3 (of entertainment for dining out) = 1/12 of your “wants” budget.
This level of detail helps individuals understand exactly where their money is going, identify areas for adjustment, and ensure their spending aligns with their financial priorities.
Calculating Savings Goals and Retirement Contributions
Setting and achieving savings goals also benefits immensely from fractional calculations. Many financial advisors recommend saving a certain percentage (a fraction) of each paycheck. If an individual decides to contribute 1/4 of their annual bonus to their retirement account, and further earmarks 1/3 of that retirement contribution for a specific high-growth, high-risk fund within their 401(k), they are engaging in multi-layered fractional thinking.
The portion of the annual bonus going into that specific fund would be:
1/4 (of bonus to retirement) × 1/3 (of retirement to high-growth fund) = 1/12 of the annual bonus.
This method allows for precise planning of how different income streams contribute to various long-term financial objectives, ensuring that diversified savings strategies are not only planned but also executed with precision.
Understanding Expense Ratios and Management Fees
Investment funds, particularly mutual funds and ETFs, charge expense ratios and management fees, which are typically expressed as a small fraction or percentage of the assets under management. These fees accumulate over time and can significantly impact long-term returns. If a fund charges an annual expense ratio of 1/4 of 1% (or 0.25%), and within that, a particular sub-fund or underlying investment vehicle has an embedded fee that represents 1/3 of that initial expense ratio, understanding the total cost requires fractional analysis. This helps investors identify how much of their returns are eroded by fees, promoting a more cost-effective approach to investing.
Risk Assessment and Financial Modeling
In business and personal finance, understanding fractional relationships is crucial for effective risk management and building robust financial models. It allows for scenario planning and the quantification of potential impacts.
Stress Testing Scenarios: Impact of Layered Risks
Businesses frequently use stress testing to evaluate their resilience against adverse economic conditions or operational failures. Consider a business highly dependent on a few key clients. A financial model might project that 1/4 of their total client base is at high risk of default. Furthermore, within that high-risk segment, historical data suggests that 1/3 of those defaults are typically unrecoverable due to insolvency.
To assess the maximum potential impact on revenue, the business would calculate:
1/4 (of clients at high risk) × 1/3 (of high-risk defaults unrecoverable) = 1/12 of the total client base’s revenue is potentially lost and unrecoverable.
This fractional approach allows companies to quantify layered risks and develop contingency plans. For individuals, similar logic applies when assessing job security (what fraction of your income is tied to one volatile source?) or the impact of market downturns on diversified portfolios.
Understanding Leverage and Debt Structures
In corporate finance, leverage involves using borrowed capital to finance assets. Debt can be structured in complex ways, with different tranches and repayment schedules. Understanding fractional ownership of debt, or fractional interest payments, is vital. For instance, if a company has multiple lenders, and one lender holds 1/4 of the total debt, and the interest payments on that specific tranche of debt represent 1/3 of the company’s total annual interest expense, then:
1/4 (of total debt by lender) × 1/3 (of total interest by that lender) = 1/12 of total interest expense attributed to that specific portion of debt from that specific lender.
Such detailed analysis helps in managing cash flow, negotiating terms, and understanding the true cost and distribution of debt obligations.
From Theory to Action: Applying Fractional Wisdom for Wealth Building
The journey from understanding “1/4 of 1/3” to building substantial wealth is paved with consistent application of these fractional insights. It’s about more than just numbers; it’s about a mindset.
Empowering Financial Decisions with Proportional Thinking
Embracing fractional thinking empowers individuals and businesses to make more nuanced and effective financial decisions. It moves us beyond simplistic “all or nothing” approaches, enabling the allocation of resources precisely where they are most needed or where they can generate the greatest returns. Whether it’s carving out a specific percentage for emergency savings, diversifying an investment portfolio across various sectors, or breaking down a large expense into smaller, manageable payments, proportional thinking provides the clarity and control necessary to navigate the financial world confidently. It fosters a proactive rather than reactive approach to money management.
The Compounding Effect of Small, Consistent Allocations
Perhaps the most profound takeaway from the concept of “1/4 of 1/3” in finance is its connection to the power of compounding. While the calculation itself deals with immediate proportions, the underlying principle – that small parts contribute to a larger whole – is central to long-term wealth accumulation. Regularly setting aside even a small fraction of your income for savings or investments, and then allowing those fractions to grow and earn returns, demonstrates the exponential power of compounding. Each fractional contribution, however small, becomes a building block, and when combined with the returns generated from previous contributions, the growth accelerates over time. This consistent, disciplined fractional allocation is the secret sauce behind many successful long-term financial strategies.
In conclusion, “what is 1/4 of 1/3?” is far from a trivial question in the financial domain. Its simple answer of 1/12 belies a profound truth: the world of money is built on fractions, proportions, and layers of allocation. By mastering this fundamental concept, individuals and businesses gain an invaluable tool for precise financial planning, astute investment, effective budgeting, and robust risk management. It transforms complex financial landscapes into understandable, manageable segments, ultimately paving the way for more informed decisions and greater financial well-being.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.