
At first glance, the question “what is 1/2 of 1 and 3/4” appears to be a straightforward arithmetic problem, a relic from elementary school textbooks. The solution, which we will derive shortly, is indeed simple. However, dismissing such a fundamental query as merely basic math overlooks its profound significance in the realm of personal finance, investing, and business strategy. In a world increasingly driven by complex financial instruments and data, the ability to grasp and apply foundational mathematical concepts like fractions is not just an academic exercise; it is a critical skill for financial literacy and empowerment.
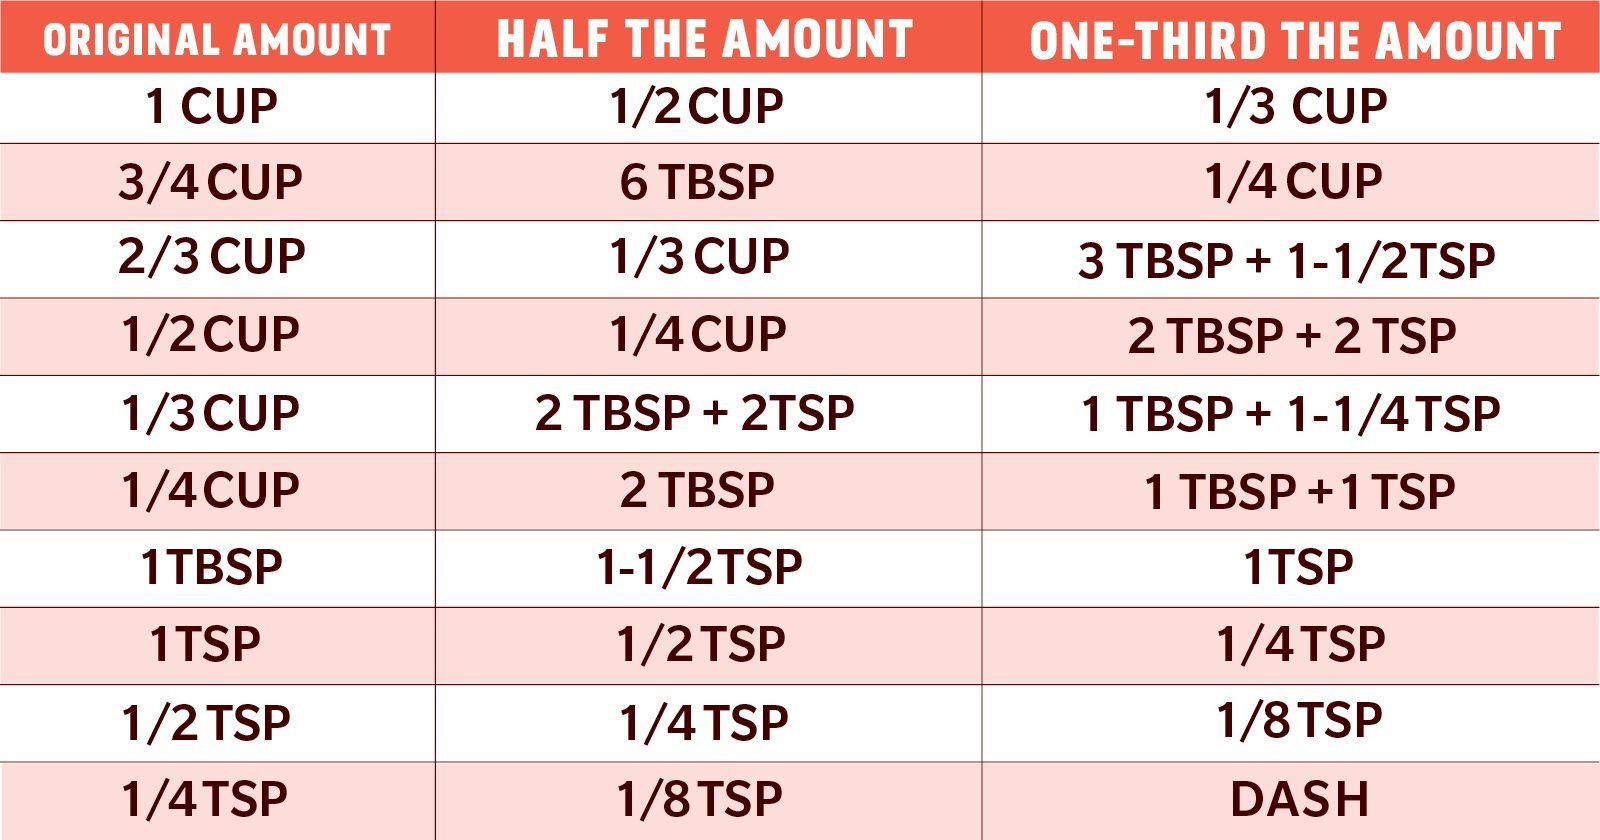
Understanding fractions is the bedrock upon which percentages, ratios, and ultimately, sophisticated financial models are built. Whether you’re budgeting your household income, calculating investment returns, analyzing a company’s financial statements, or negotiating a business deal, the principles encapsulated in “1/2 of 1 and 3/4” are constantly at play. This article delves into how this seemingly simple mathematical operation underpins a vast array of financial scenarios, transforming basic arithmetic into a powerful tool for informed decision-making and wealth creation.
Let’s first quickly solve the problem to establish our base:
To calculate “1/2 of 1 and 3/4”:
-
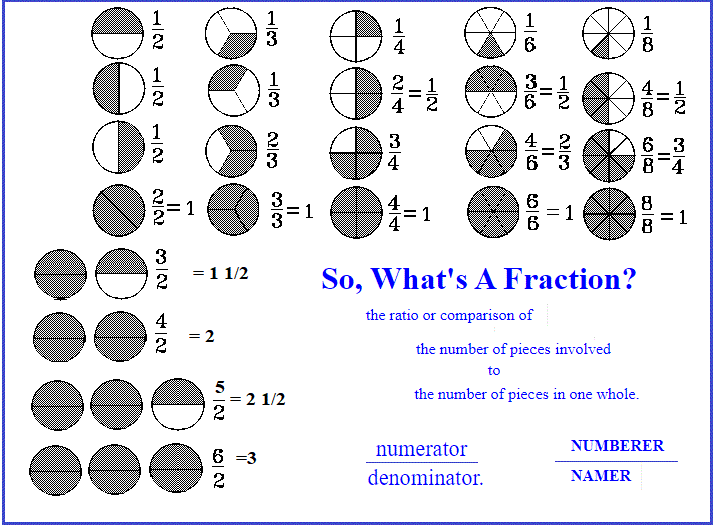
Convert the mixed number to an improper fraction: 1 and 3/4 = (1 * 4 + 3) / 4 = 7/4.
-
Multiply this fraction by 1/2: (1/2) * (7/4) = 7/8.
So, 1/2 of 1 and 3/4 is 7/8.
Now, let’s explore why understanding this seemingly simple calculation is so vital in the world of money.
The Unseen Power of Fractions in Everyday Finance
Every day, we encounter financial situations that demand an intuitive understanding of fractions, even if we label them as percentages or ratios. From managing personal budgets to making purchasing decisions, the ability to break down whole amounts into their constituent parts is indispensable.
Budgeting and Expense Allocation: Dividing the Financial Pie
The concept of a budget is fundamentally about allocating fractions of your income. When you decide to save 10% of your paycheck, you’re essentially earmarking 1/10 of it. When you set aside money for housing, food, transportation, and entertainment, you’re dividing your entire financial “pie” into various fractional slices.
Consider a practical example rooted in our initial problem: Imagine your monthly income is your “whole,” and you’ve allocated a certain portion for discretionary spending. Let’s say this discretionary portion already accounts for 1 and 3/4 times your typical spending from last year due to a recent pay raise. Now, you decide to direct precisely 1/2 of this new, larger discretionary amount towards a specific savings goal or a new hobby. To understand how much of your total income is truly going to that new goal, you would perform the exact calculation: “1/2 of 1 and 3/4” represents how much larger this new allocation is compared to a base unit. This helps you visualize how new spending or saving habits ripple through your overall financial plan, ensuring that no single category disproportionately consumes your resources without your conscious decision.
Understanding Discounts, Sales, and Price Adjustments
Discounts and sales are prime examples of fractional calculations in action. A “half-off” sale is explicitly 1/2 reduction. But what if there’s a layered discount? “An item is 1 and 3/4 times its original price due to inflation, but you’re getting a special discount equivalent to 1/2 off that inflated price.” This might be a convoluted scenario, but it illustrates how real-world pricing can combine multipliers and fractional reductions. Without the ability to work with fractions, evaluating the true cost or benefit of such offers becomes a guessing game. From understanding “buy one get one half off” to calculating compounded percentage increases or decreases, a solid fractional foundation helps you make smarter purchasing decisions and discern genuine value.
Investing and Wealth Building: Portions of Growth and Risk
The world of investing is inherently fractional. Investors deal with shares, dividends, returns, and portfolio allocations, all of which are expressions of parts of a whole. Misinterpreting these fractions can lead to suboptimal decisions or significant financial losses.
Calculating Returns and Portfolio Allocations
When you invest, you often allocate your capital across different asset classes – stocks, bonds, real estate, etc. This is a direct application of fractional thinking. For instance, you might decide to put 1/2 of your portfolio into equities and the remaining 1/2 into fixed-income securities. Or perhaps a more nuanced approach: 1/2 into diversified ETFs, and of the remaining capital, 3/4 into high-growth tech stocks, leaving the final 1/4 of that remaining half for alternative investments.
Connecting back to our problem, imagine an investment fund that has grown to 1 and 3/4 times its initial value over a year. If you, as an investor, own a portion equivalent to 1/2 of that fund’s total holdings, then your personal stake’s growth is directly proportional to “1/2 of 1 and 3/4.” This calculation gives you your exact fractional ownership of the overall growth, allowing you to accurately assess your portfolio’s performance and make informed adjustments based on your financial goals and risk tolerance. Understanding that your share of the return is 7/8 of the fund’s total growth factor is crucial for accurately tracking your wealth accumulation.
Shares, Dividends, and Business Ownership
In the corporate world, ownership is defined by shares, which are fractions of the company’s total equity. If you own 1/2 of a small business, you are entitled to 1/2 of its profits and voting rights. Similarly, dividends are often calculated as a fraction or percentage of earnings per share.
Consider a scenario where a company announces that its dividend payout will be 1 and 3/4 times what it was last quarter due to exceptional performance. If you own 1/2 of the total available shares for that specific dividend class, your personal dividend income will be calculated based on “1/2 of 1 and 3/4” of the new total payout factor relative to previous periods. This precise fractional understanding ensures you can accurately project your income streams from investments and understand your proportional claim on a company’s success.
Debt, Loans, and Interest: The Fractional Cost of Money
Debt might seem like a whole number problem, but its underlying mechanics are deeply rooted in fractions and percentages, particularly when it comes to interest and repayment schedules.
Loan Repayments and Interest Calculation
When you take out a loan, the interest rate is a fraction (or percentage) of the principal amount that you pay over time. Mortgage payments, for example, are complex calculations that involve amortizing the principal and interest over decades, where each payment is a fractional contribution to both. Understanding how much of each payment goes to interest versus principal is critical for knowing when your debt will be fully repaid.
Applying our problem: Suppose you took out a business loan where the total repayment, including interest, is projected to be 1 and 3/4 times the original principal amount. If you’ve been advised to pay off an extra 1/2 of that projected total repayment amount within the first year to save significantly on interest, you’d be looking at “1/2 of 1 and 3/4” times the original principal as your accelerated payment target. This helps borrowers comprehend the true cost of borrowing and strategize for earlier debt retirement, transforming abstract rates into concrete repayment strategies.
Understanding APR and Effective Rates
Annual Percentage Rate (APR) and effective interest rates are crucial for comparing loans and credit products. These rates are often presented as percentages, but they are fundamentally fractions indicating the cost of borrowing per year. A slightly higher fractional rate can translate into thousands more over the life of a loan. When financial institutions quote rates, they often layer various fees and compounding methods. Knowing how these fractional components interact allows consumers to accurately compare offers and choose the most cost-effective financing options.
Business Finance and Strategic Decision-Making: Beyond Simple Arithmetic
In the corporate world, leaders and analysts constantly deal with fractional data to assess performance, allocate resources, and chart strategic directions.
Profit Sharing and Equity Distribution
For partnerships and startups, how profits are shared and equity is distributed is often a matter of precise fractions. If a new partner is brought in and is allocated 1/2 of the existing profit share that was previously 1 and 3/4 times the original founders’ initial contribution, the calculation “1/2 of 1 and 3/4” becomes directly relevant to determining their exact stake and the remaining shares for existing partners. These fractional agreements are legally binding and form the backbone of a company’s ownership structure and incentive schemes.
Resource Allocation and Project Budgeting
Businesses allocate budgets to various departments, projects, and initiatives. These allocations are almost always fractional. A marketing budget might be 1/2 of the total operating expenses, with 3/4 of that marketing budget dedicated to digital advertising. The ability to break down and rebuild these fractional budgets ensures that resources are deployed efficiently and strategically, aligning with overall business objectives. This meticulous fractional planning is vital for maintaining financial health and achieving growth targets.
Cultivating Financial Literacy: The Foundation of Empowerment
The journey to financial independence and success begins with a solid understanding of fundamental concepts. “What is 1/2 of 1 and 3/4” is more than just a math problem; it’s a gateway to advanced financial comprehension.
Bridging the Gap: From Basic Math to Financial Confidence
Mastering simple fractional calculations builds confidence, allowing individuals to approach more complex financial problems without intimidation. It demystifies financial jargon and empowers people to take control of their money. When you can intuitively understand that 1/2 of an amount that’s already 1 and 3/4 times larger than a base unit translates to 7/8 of that base unit, you’re not just doing math; you’re building a mental model for proportionality and scaling that is invaluable in every financial decision. This proficiency helps individuals critically analyze financial products, understand contracts, and evaluate investment opportunities with a discerning eye.

Practical Applications and Continuous Learning
The challenge for individuals and professionals alike is to move beyond rote calculation and develop a deep intuition for how fractions operate in the financial world. This involves actively seeking out opportunities to apply these concepts—whether it’s breaking down your monthly expenses, calculating the true yield of an investment, or analyzing a company’s financial report. Continuous learning and practical application transform abstract mathematical principles into tangible financial insights, leading to more secure and prosperous financial futures.
In conclusion, the seemingly innocuous question “what is 1/2 of 1 and 3/4” serves as a powerful reminder that fundamental mathematical skills are indispensable tools for navigating the complexities of modern finance. From personal budgeting to global investing, the ability to work with fractions is not just an advantage, but a necessity for anyone aspiring to financial acumen and empowerment.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.