
In the world of personal finance and wealth management, we often discuss market volatility, inflationary pressures, and diversified portfolios. However, one of the most significant threats to a stable financial trajectory is the sudden, unexpected health crisis. The phrase “what happens when you fall asleep with a concussion” is often whispered in emergency rooms with a sense of medical urgency, but from a financial perspective, it represents the moment a person “falls asleep” to their financial preparedness. A concussion is not just a biological event; it is a disruptive economic force that can dismantle months or even years of meticulous budgeting and saving.

Understanding the financial anatomy of a head injury is essential for anyone looking to safeguard their net worth. When a traumatic brain injury (TBI) occurs, the immediate medical concerns are paramount, but the secondary wave of fiscal impact—ranging from emergency room surcharges to long-term loss of productivity—can be just as debilitating. This exploration dives into the financial reality of recovery, the hidden costs of medical negligence regarding insurance, and how to build a fiscal “helmet” to protect your wealth from the unexpected.
The Immediate Economic Impact: From the ER to the Bank Account
The moment a concussion occurs, a timer starts on a series of cascading expenses. For the average individual, the initial point of contact is the Emergency Department (ED). Unlike a planned surgery or a routine check-up, an emergency visit for a head injury bypasses the opportunity for price shopping or network verification.
Emergency Room Economics and Diagnostic Surcharges
The cost of treating a concussion in an emergency setting can vary wildly, often ranging from $2,000 to over $20,000 depending on the facility and the required diagnostics. If a physician suspects a brain bleed or a more severe TBI, they will likely order a Computed Tomography (CT) scan or a Magnetic Resonance Imaging (MRI) session. In the United States, a single CT scan can be billed at upwards of $3,000.
Furthermore, “falling asleep” with a concussion often leads to an overnight observation stay. In the financial world, this is known as “observation status,” which can be a trap for the underinsured. Hospital observation is often classified as outpatient care, meaning the patient may be responsible for a higher percentage of the bill than if they were admitted as an inpatient. These immediate out-of-pocket costs can quickly exhaust an emergency fund, forcing individuals to dip into long-term investments or accrue high-interest credit card debt.
The Specialist Referral Loop
Recovery from a concussion rarely ends at the hospital exit. Patients are often referred to neurologists, physical therapists, and occupational therapists. Each of these visits carries a specialist co-pay, often significantly higher than a primary care visit. For those with high-deductible health plans (HDHPs), these recurring costs become a monthly drain on disposable income. When you factor in the cost of prescription medications for symptom management—such as anti-nausea or pain-relief drugs—the “minor” concussion starts to look like a major line item in the annual budget.
The Productivity Deficit: Why Rest is a Costly Investment
In the modern knowledge economy, your cognitive function is your primary asset. When a doctor prescribes “brain rest” following a concussion—meaning no screens, no reading, and no complex decision-making—they are essentially prescribing a period of zero productivity. For high-earners, freelancers, and small business owners, this is where the true financial danger lies.
The Gap Between Sick Leave and Financial Stability
While salaried employees may have a bank of sick days, a concussion often requires weeks, or even months, of cognitive downtime. Once sick leave is exhausted, many employees find themselves navigating the complexities of Short-Term Disability (STD). Most STD policies only cover 60% to 70% of a worker’s salary. For an individual living in a high-cost-of-living area with a tight budget, a 30% reduction in gross income for two months can be catastrophic.
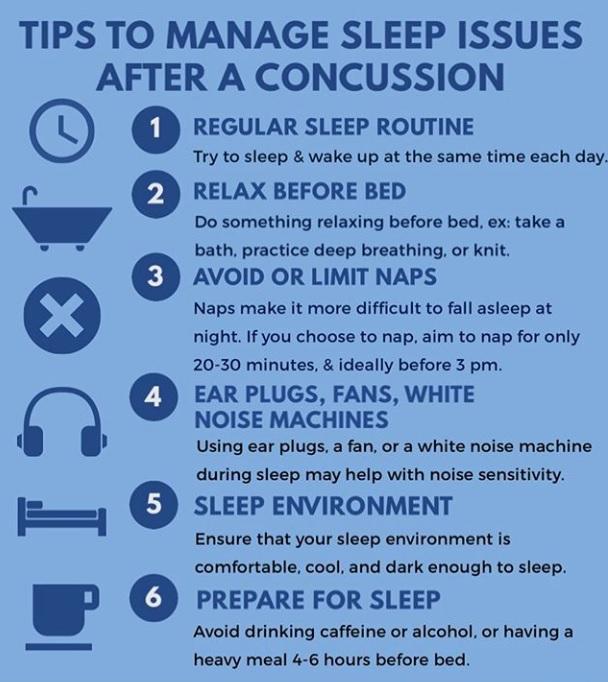
The “concussion fog” also impacts job performance upon return. If a professional returns to work too early—driven by financial fear—they risk making costly errors, missing deadlines, or failing to meet KPIs, which can ultimately lead to job loss or missed promotions. The “cost of rest” is high, but the “cost of premature return” can be the permanent derailment of a career trajectory.
The Gig Economy and the Vulnerability of the Self-Employed
For those in the “Money” sector who operate as independent contractors or digital entrepreneurs, there is no safety net. If a freelance developer or a day trader cannot look at a screen due to light sensitivity from a concussion, their revenue stream stops instantly. This highlight’s the necessity of “Business Interruption” insurance or robust personal disability insurance. Without these tools, a head injury isn’t just a health hurdle; it’s a total cessation of business operations.
Navigating the Insurance Labyrinth and Protecting Personal Assets
The complexity of medical billing is such that even the most financially literate individuals can find themselves overwhelmed while recovering from a brain injury. Protecting your wealth requires an active, strategic approach to insurance and debt management.
The Role of Health Savings Accounts (HSAs) and FSAs
One of the most effective ways to mitigate the financial blow of a concussion is through the strategic use of a Health Savings Account (HSA). Because HSA contributions are pre-tax and the funds can be invested, they serve as a specialized emergency fund for medical crises. For those who have “fallen asleep” on their HSA contributions, a concussion serves as a harsh reminder of the tax-advantaged growth they’ve missed. Utilizing these funds allows a patient to pay for high-cost diagnostics and specialist fees without touching their primary savings or retirement accounts.
Negotiating Medical Bills and Avoiding Collections
In the aftermath of a concussion, the mailbox will inevitably fill with “Explanation of Benefits” (EOB) forms and invoices. It is vital to scrutinize these documents. Coding errors are frequent in emergency medicine; a “Level 5” ER visit might be billed when only a “Level 3” service was provided.
Engaging in medical bill negotiation is a critical financial skill. Many hospitals offer “prompt pay” discounts or financial assistance programs for those whose income has been impacted by their injury. Taking an active role in this process—or hiring a medical billing advocate—can save thousands of dollars, preserving capital for future investments.
The Long-Term Wealth Implications of Cognitive Health
If we view our brain as a “wealth-generating engine,” then a concussion is a mechanical failure that requires precision repair. The long-term financial implications of recurring head injuries (Post-Concussion Syndrome) can include a permanent reduction in earning capacity and an increase in lifetime medical spending.
Investing in Preventive and Recovery Tech
From an investment standpoint, the “Brain Health” sector is a burgeoning field. As individuals become more aware of the financial risks associated with cognitive decline and TBI, there is an increasing flow of capital toward wearable technology that monitors impact and AI-driven diagnostic tools. For the savvy investor, understanding the impact of concussions on the workforce can lead to strategic placements in biotech and MedTech firms focusing on neuro-regeneration.
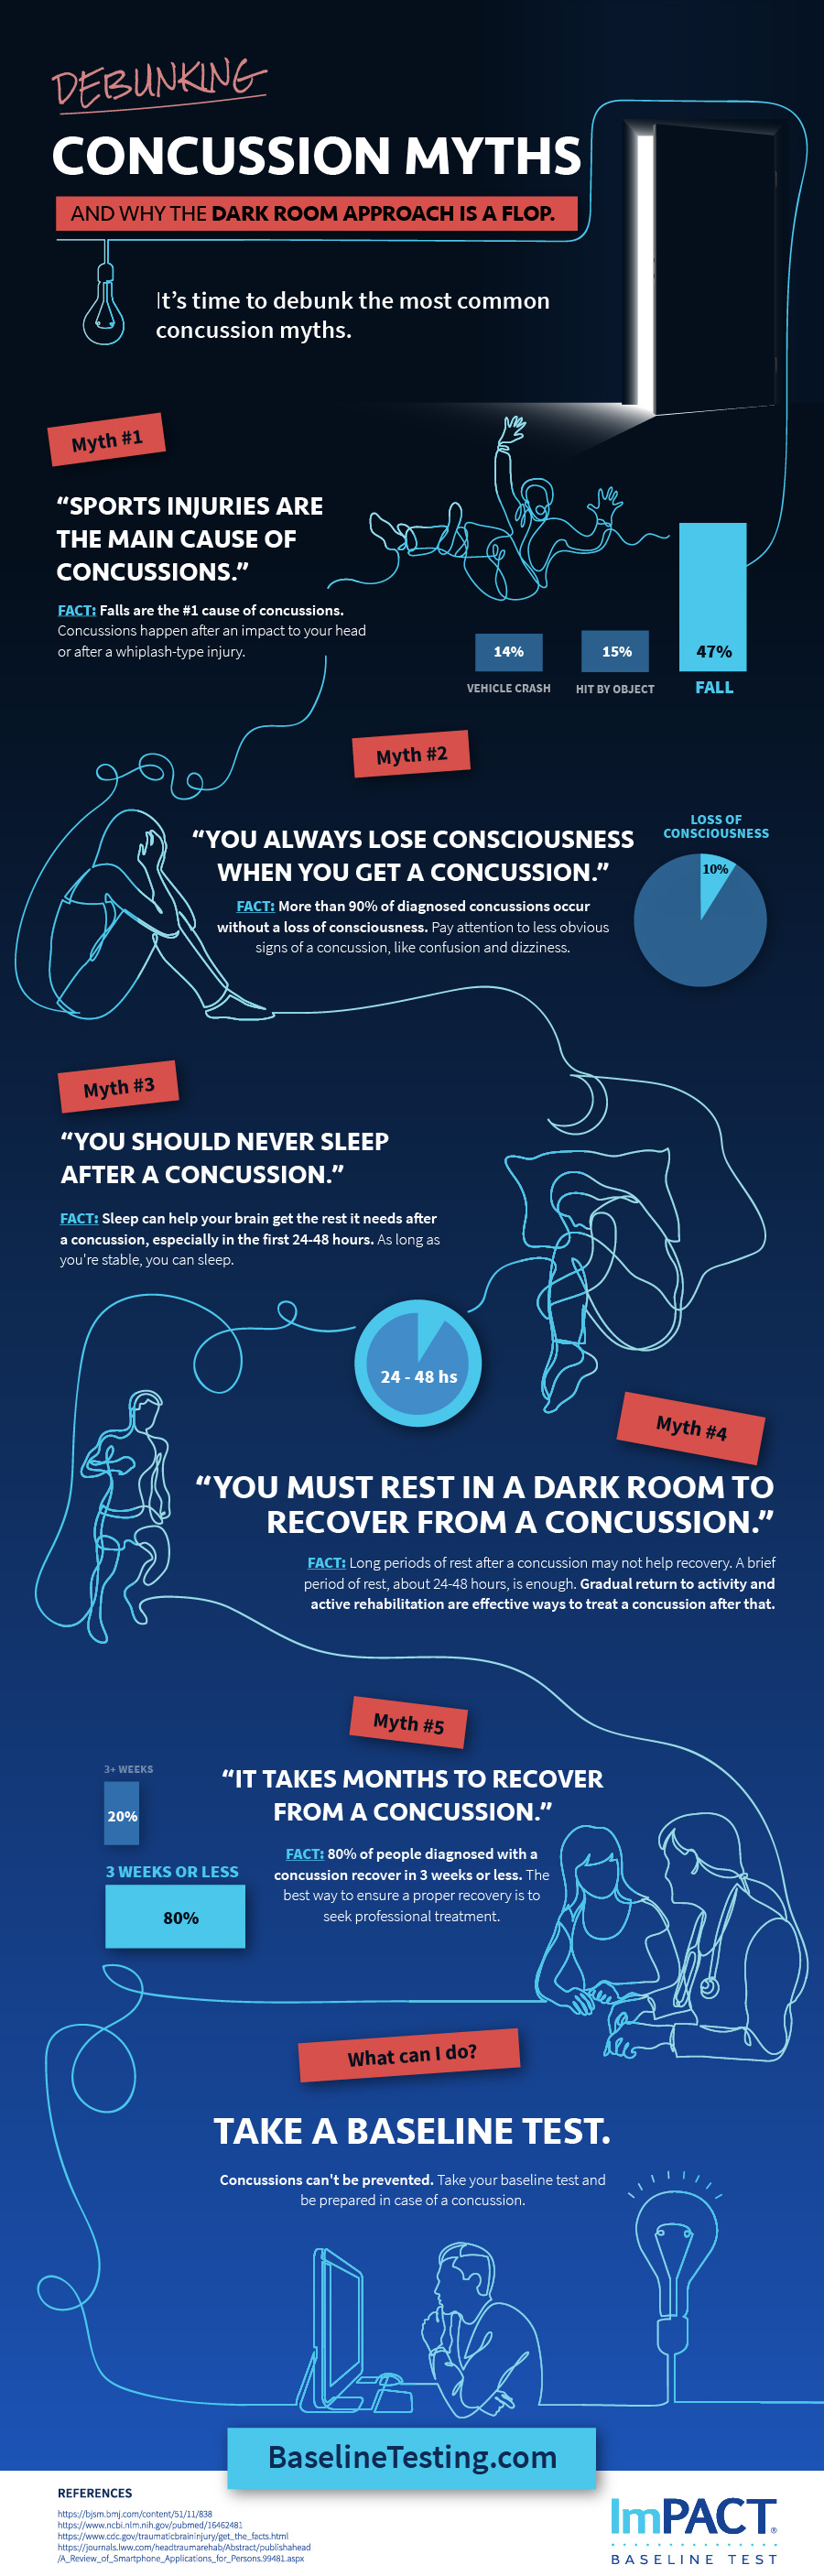
The ROI of Holistic Recovery
It is often more cost-effective to spend money upfront on high-quality rehabilitation than to suffer the long-term effects of an improperly healed brain. This might include investing in specialized “concussion clinics” that offer multi-disciplinary care. While the initial price tag is higher, the Return on Investment (ROI) is measured in the restoration of full earning power and the prevention of future medical complications.
In conclusion, “falling asleep” with a concussion is a metaphor for the financial complacency that many people harbor regarding their health. A concussion is a stark reminder that our physical well-being is the bedrock of our financial portfolios. By understanding the immediate costs, the impact on productivity, the necessity of insurance navigation, and the long-term value of cognitive health, individuals can ensure that a physical blow to the head does not become a permanent blow to their financial future. Wealth management is not just about picking the right stocks; it is about building a resilient life that can withstand the high cost of a recovery you never saw coming.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.