
In the world of personal finance, the metaphor of physical health is more than just a convenient comparison; it is a foundational blueprint. When we ask “what fruit is good to lose weight” in a financial context, we are looking for the “low-hanging fruit”—those immediate, high-impact actions that allow us to shed the “weight” of debt and trim the “fat” of unnecessary expenses. Just as a nutritionist looks for nutrient-dense foods to optimize a metabolism, a financial strategist looks for high-yield opportunities and cost-cutting measures that yield the greatest return for the least amount of effort.
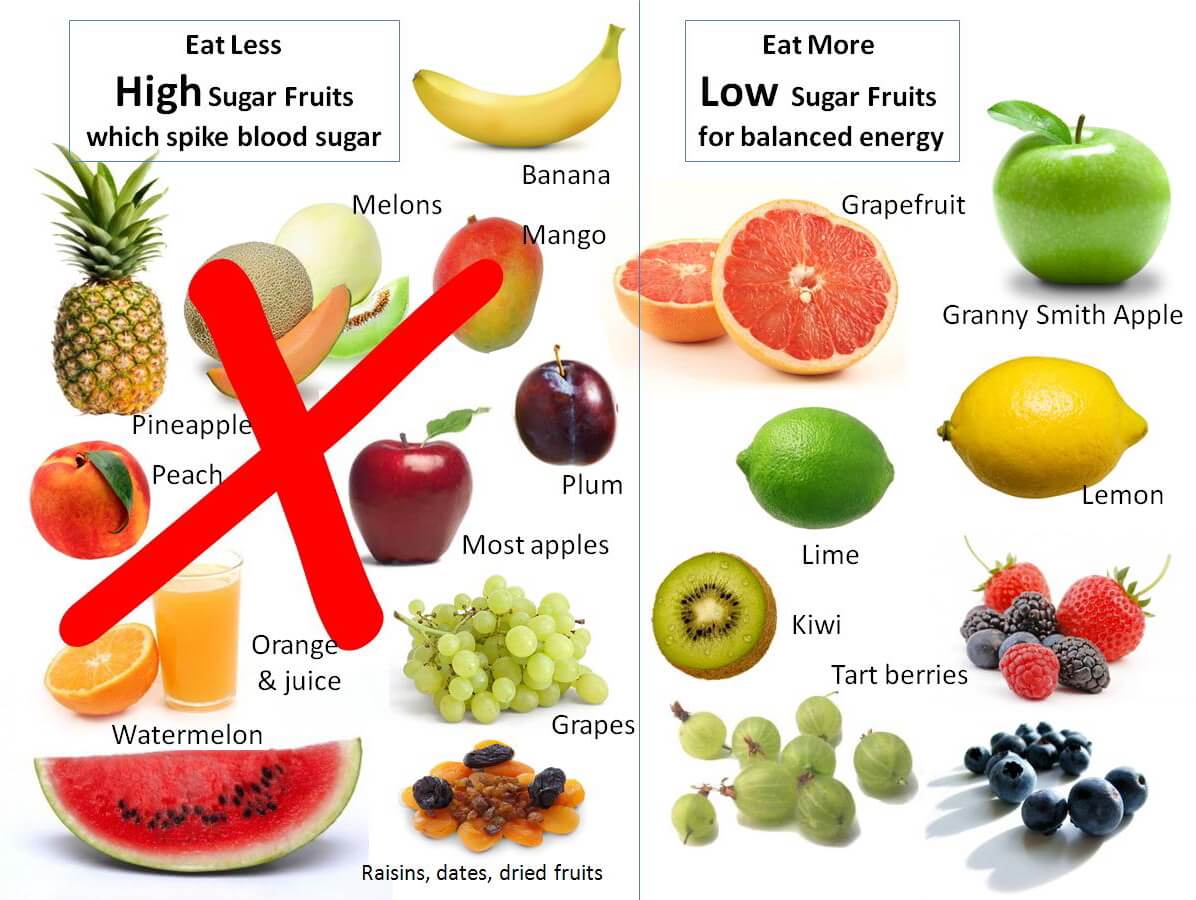
To achieve true financial fitness, one must adopt a holistic approach. This involves not only cutting back on excess but also nourishing the “body” of your portfolio with assets that promote sustainable growth. This article explores how to identify the metaphorical fruits of the financial world that will help you lose the weight of liability and build a leaner, stronger economic future.
Trimming the Fat: Auditing Your Expenses to Eliminate Financial Waste
Before you can build muscle—or in this case, capital—you must address the bloat. Financial weight often comes in the form of “lifestyle creep” and invisible expenses that accumulate over time. These are the empty calories of your budget. By conducting a thorough audit, you can identify the low-hanging fruit of savings.
Subscription Audits: The Easiest Fruit to Pick
In the digital age, subscription services are the silent killers of a lean budget. From streaming platforms and software-as-a-service (SaaS) tools to monthly curated boxes, these recurring costs often go unnoticed. Identifying and canceling unused or redundant subscriptions is the “weight loss” equivalent of cutting out sugary drinks. It is an immediate win that requires minimal effort but results in significant long-term savings.
To execute this, use a financial tracking app or review the last three months of bank statements. Look for “zombie” subscriptions—services you signed up for during a free trial but never canceled. By pruning these, you are essentially reclaiming “lost” income that can be redirected toward debt repayment or investment.
Negotiating Interest Rates: Reducing the Weight of Debt
Debt is the heaviest weight an individual can carry. However, not all debt is created equal. High-interest credit card debt acts as a metabolic inhibitor, slowing down your ability to build wealth. One of the most effective “fruits” to grab is the renegotiation of your interest rates.
Contacting creditors to request a lower APR (Annual Percentage Rate) or utilizing balance transfer offers can significantly reduce the “weight” of your monthly payments. This doesn’t just lower your expenses; it changes the composition of your payments so that more of your money goes toward the principal rather than the interest. This is a strategic move that accelerates the debt-reduction process, much like high-intensity interval training accelerates fat loss.
Harvesting Gains: Identifying Low-Risk, High-Yield Investment Fruits
Once the excess waste has been trimmed, the focus must shift to nourishment. In finance, nourishment comes from investments. To “lose weight” on your liabilities while growing your net worth, you must pick the right investment fruits—those that offer a balance of safety and growth.
Index Funds and ETFs: The Nutritious Core of Your Portfolio
For the majority of people looking to build wealth, the “superfood” of the investment world is the low-cost index fund or Exchange-Traded Fund (ETF). These financial instruments provide broad market exposure, diversification, and low management fees. Rather than trying to “pick the winner” (the equivalent of a fad diet), index funds allow you to capture the growth of the entire market.
Historical data shows that consistent, long-term investment in broad market indices outperforms most actively managed portfolios. This is the “slow and steady” approach to financial health. It ensures that your wealth grows organically, bolstered by the power of compound interest, which is the ultimate “growth hormone” for your capital.
Tax-Advantaged Accounts: Maximizing the Harvest
To ensure you keep more of what you earn, you must utilize tax-advantaged accounts such as 401(k)s, IRAs, or HSAs. These accounts are the high-yield fruits of the financial orchard. By contributing to a 401(k), especially if there is an employer match, you are effectively receiving a 100% return on your investment immediately.
The tax benefits—whether tax-deferred growth or tax-free withdrawals—act as a shield for your assets. Minimizing your tax liability is one of the most sophisticated ways to “lose weight” on your expenses. Every dollar saved in taxes is a dollar that remains in your “body” of wealth, where it can continue to compound and grow.
Side Hustles: Planting New Seeds for Accelerated Growth
If trimming expenses is “dieting,” then increasing your income is “exercise.” To reach your financial goals faster, you may need to look beyond your primary salary and plant new seeds of income. Identifying the right side hustle is about finding the “fruit” that fits your skill set and schedule.
Digital Real Estate: Passive Income as a Long-Term Asset
One of the most attractive fruits in the modern economy is digital real estate. This includes things like creating an online course, writing an e-book, or building a niche blog that generates ad revenue. While these require an initial investment of time (planting the seed), they eventually produce passive income (the harvest).
The beauty of digital assets is their scalability. Unlike a service-based job where you trade hours for dollars, a digital product can be sold to thousands of people simultaneously. This “weightless” income stream allows you to scale your wealth without a corresponding increase in your workload, creating a lean, high-output financial engine.
Skill Monetization: Converting Expertise into Cash Flow
Every individual possesses “low-hanging fruit” in the form of existing skills. Whether it is consulting, freelance writing, graphic design, or coding, your professional expertise can be packaged and sold as a secondary income stream. This is often the fastest way to increase your cash flow because it requires no capital investment—only the application of your current “muscle.”
By dedicating even five hours a week to a high-value side hustle, you can generate an extra $500 to $2,000 a month. If this “extra” income is funneled directly into debt repayment or investments, it acts as a catalyst, drastically shortening the time it takes to reach your financial goals.
The Psychology of Wealth: Maintaining a Lean Financial Lifestyle
Just as maintaining a healthy weight requires a lifestyle change rather than a temporary diet, financial fitness requires a psychological shift. You must learn to distinguish between “nutritious” spending that adds value to your life and “junk” spending that only provides a temporary dopamine hit.
Lifestyle Creep: Avoiding the Sugar Rush of Impulsive Spending
Lifestyle creep occurs when your expenses rise at the same rate as your income. As you earn more, it is tempting to buy a bigger house, a faster car, or more expensive clothes. This is the financial equivalent of a sugar rush—it feels good in the moment but leads to long-term “weight gain” in the form of higher overhead and less liquidity.
To combat this, adopt the “50/50 rule” for every raise or bonus you receive: put 50% toward your future (savings/investments) and allow yourself to spend the other 50% on lifestyle improvements. This allows for a better quality of life while ensuring that your financial foundation continues to strengthen.

Automated Systems: Setting Your Gains on Autopilot
The most successful “dieters” in the financial world are those who remove willpower from the equation. By automating your finances—setting up automatic transfers to your savings, investment accounts, and bill payments—you ensure that your “nutritional” habits happen without you having to think about them.
Automation is the “fruit” that keeps on giving. It prevents the temptation to spend money that should be saved and ensures that you are consistently “working out” your portfolio. Over years and decades, these automated habits build the massive momentum required to achieve financial independence and true wealth.
In conclusion, “what fruit is good to lose weight” in the financial sector is not about a single magic solution. It is about identifying the low-hanging fruit of expense reduction, the high-yield fruit of smart investing, and the new seeds of diversified income. By trimming the financial fat and nourishing your assets, you can transform your economic health and build a lean, resilient, and prosperous future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.