
A career in veterinary medicine is often seen through the lens of compassion, scientific expertise, and a deep love for animals. Aspiring veterinarians envision themselves healing pets, contributing to public health, or protecting livestock, driven by a noble purpose. While the academic rigor and scientific knowledge required are widely acknowledged, the financial education and strategic planning needed to navigate this demanding path successfully are often less discussed. This article aims to reframe the question “what education do you need to be a veterinarian?” not just in terms of biology and chemistry, but through the crucial prism of personal finance, investment, and long-term wealth management. Becoming a Doctor of Veterinary Medicine (DVM) is one of the most significant financial undertakings an individual can embark upon, requiring meticulous financial foresight from the earliest stages of ambition through to a thriving professional life. Understanding the costs, funding mechanisms, and financial realities post-graduation is as vital as mastering anatomy or pharmacology.
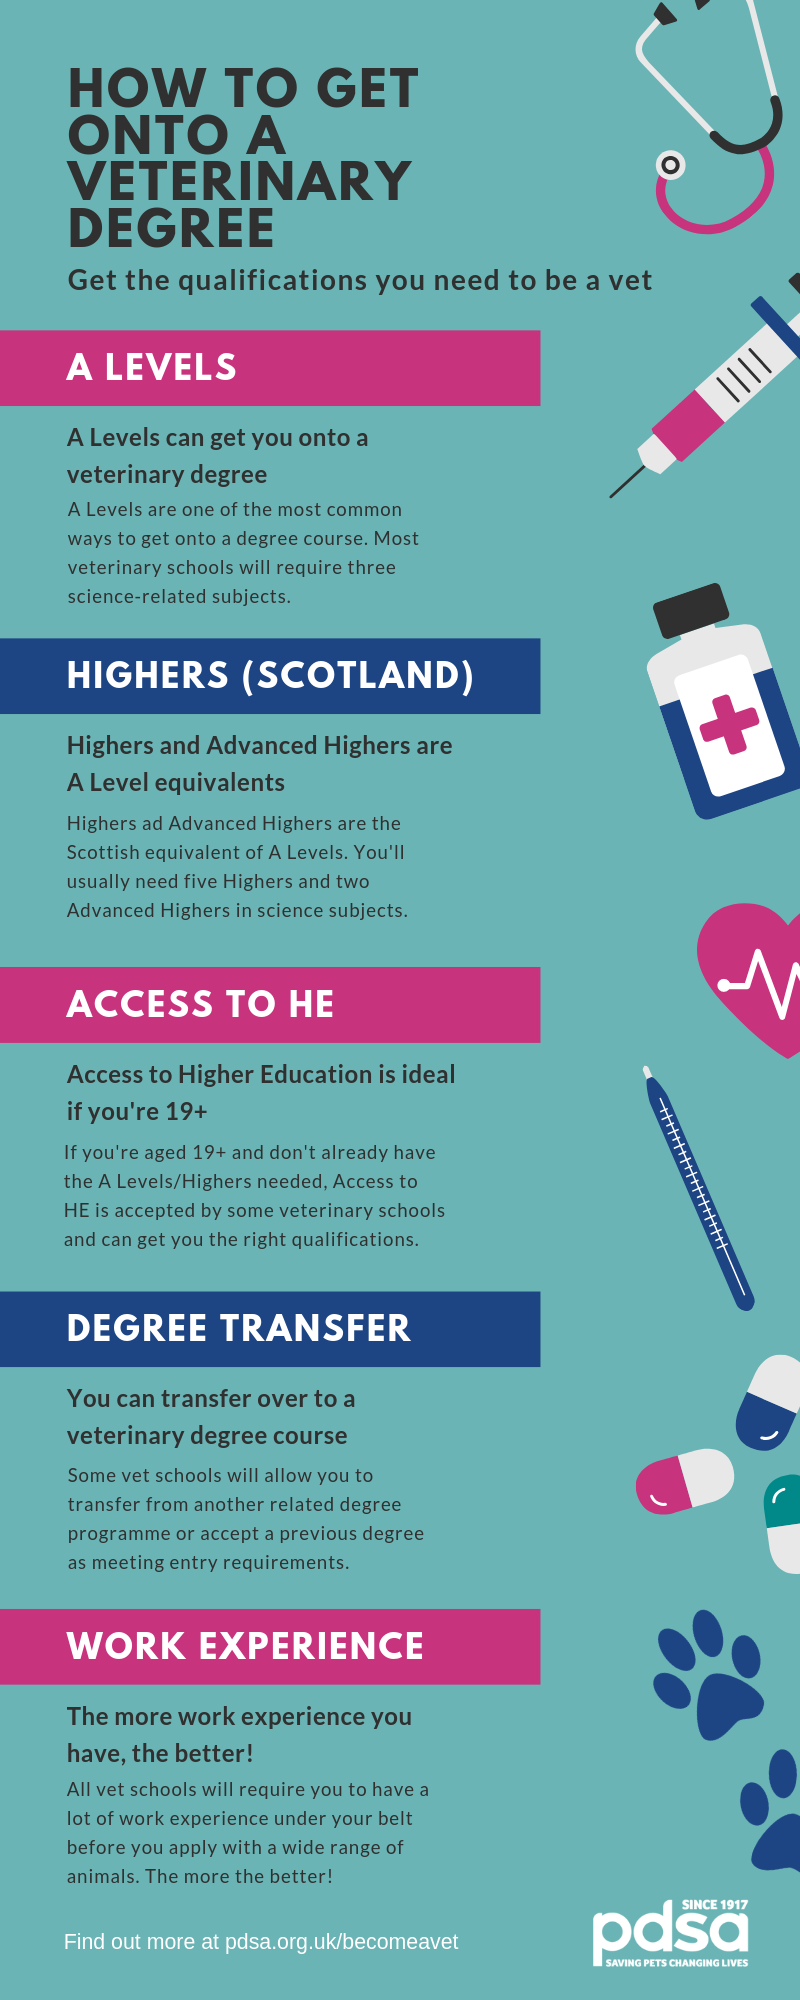
The True Cost of Veterinary Education: Beyond Tuition Fees
Embarking on a journey to become a veterinarian means preparing for a substantial financial investment. It’s an education renowned for its intensity and, consequently, its cost. While tuition figures are often the first number that comes to mind, the true financial commitment extends far beyond these publicized figures, encompassing a myriad of direct, indirect, and often overlooked expenses that can dramatically inflate the overall bill. A comprehensive financial education starts with a realistic assessment of these costs.
Understanding Direct Educational Expenses
The most apparent costs are tuition and mandatory university fees. These vary widely based on whether an institution is public or private, and whether the student qualifies for in-state or out-of-state tuition. Public university DVM programs can range from $30,000 to $60,000 annually for in-state residents, while out-of-state and private institutions can easily exceed $70,000 per year. Over four years, this alone accumulates to a staggering sum. Beyond tuition, there are recurring costs for textbooks, specialized medical equipment (such as stethoscopes, diagnostic kits, and scrubs), mandatory health insurance, and various administrative fees. These add thousands of dollars annually, essential expenditures that cannot be bypassed. Budgeting for these from day one is critical, recognizing that they are not optional but integral parts of the educational package.
Accounting for Living Expenses and Opportunity Costs
A DVM program is a full-time, highly demanding commitment, leaving little to no room for significant part-time employment. This makes living expenses a crucial, often underestimated, component of the overall financial burden. Rent, utilities, food, transportation, personal care, and social activities all add up. Depending on the city or region where the veterinary school is located, these costs can range from $15,000 to $30,000 per year. Over four years, this can amount to an additional $60,000 to $120,000.
Furthermore, there’s the concept of “opportunity cost.” This refers to the income an individual foregoes by choosing to pursue full-time education rather than working in a full-time, potentially higher-paying job. For a pre-veterinary student who might otherwise be earning a modest salary, this opportunity cost might seem minimal. However, for someone with a bachelor’s degree who could be earning a professional wage, the cumulative loss of income over four years of DVM study can be substantial, representing hundreds of thousands of dollars that could have been saved or invested. This lost income, though not an out-of-pocket expense, is a real financial sacrifice for the pursuit of a veterinary career.
The Hidden Costs: Application Fees, Interview Travel, Professional Exams
The journey to veterinary school is itself fraught with hidden financial costs. Prospective students often apply to multiple schools, incurring application fees for each submission, which can total hundreds of dollars. If invited for interviews, travel expenses for flights, accommodation, and meals can quickly escalate, especially for out-of-state or international applicants. Once accepted and during the program, there are fees for professional organization memberships, licensing exams (such as the NAVLE), and potentially certification exams for specialized fields. These seemingly minor costs accumulate, forming a significant chunk of the pre-enrollment and in-program financial outlay, demanding careful consideration in a thorough financial education plan.
Funding Your Veterinary Dream: Strategic Financial Planning
Given the formidable costs, a robust financial strategy is not merely advisable but absolutely essential for aspiring veterinarians. This segment of their “education” focuses on how to fund their path responsibly, minimizing long-term debt burden while maximizing financial aid opportunities. Understanding the landscape of scholarships, loans, and alternative funding methods is paramount.
Exploring Scholarships, Grants, and Fellowships
The most desirable forms of financial aid are scholarships, grants, and fellowships because they do not require repayment. These can be awarded based on academic merit, financial need, specific demographic criteria, research interests, or commitment to particular fields (e.g., large animal medicine, public health). Veterinary schools often have institutional scholarships, and numerous external organizations, professional associations (like the AVMA), and private foundations offer dedicated funding for DVM students. Diligent research and consistent application for these opportunities can significantly reduce reliance on loans. Developing strong writing skills for essays and maintaining an impressive academic record are crucial “educational” components for unlocking these non-repayable funds.
Navigating Student Loans: Federal vs. Private Options
For most veterinary students, student loans become an unavoidable part of their financial plan. Understanding the differences between federal and private loans is critical. Federal student loans typically offer more favorable terms, including fixed interest rates, income-driven repayment plans, and potential eligibility for public service loan forgiveness programs. Graduate PLUS loans are a common federal option for DVM students. Private loans, offered by banks and credit unions, often come with variable interest rates, fewer borrower protections, and may require a co-signer. While private loans can sometimes offer competitive rates to borrowers with excellent credit, they generally carry higher risks. A thorough financial education involves understanding the interest accrual, repayment terms, and long-term implications of each loan type before signing on the dotted line.
Creative Funding Strategies: Side Hustles and Savings
Beyond traditional financial aid, many aspiring and current DVM students employ creative strategies to fund their education. Building up a substantial savings cushion before beginning veterinary school can dramatically reduce the need for loans. This might involve working for a few years post-bachelor’s degree or diligently saving throughout undergraduate studies. During veterinary school, while time is scarce, some students manage to engage in flexible side hustles—tutoring, online freelancing, pet-sitting, or working veterinary technician shifts during breaks—to generate supplementary income. While not enough to cover tuition, these funds can significantly offset living expenses, thereby reducing the amount borrowed. This practical application of financial resourcefulness is a crucial, if unofficial, part of their financial education.
Post-Graduation Financial Realities: Managing Debt and Building Wealth

Graduating with a DVM degree is a monumental achievement, but it often comes hand-in-hand with substantial student loan debt. The average debt for a veterinary school graduate can exceed $180,000, with many carrying balances well over $250,000. Navigating this financial landscape effectively requires a continuation of their financial education, pivoting from funding acquisition to debt management and wealth building.
Student Loan Repayment Strategies
Upon graduation, veterinarians must immediately confront their student loan obligations. A comprehensive financial strategy involves exploring various repayment options. Income-Driven Repayment (IDR) plans (such as PAYE, REPAYE, IBR, ICR) adjust monthly payments based on income and family size, potentially offering relief in early career stages when salaries might be lower relative to debt. Public Service Loan Forgiveness (PSLF) is another critical program for those who work for qualifying non-profit organizations or government entities. Alternatively, refinancing student loans, particularly private ones, can sometimes secure lower interest rates, but it often means sacrificing federal loan protections. A crucial part of a DVM’s financial education is understanding these complex options and choosing the strategy that best aligns with their career path and financial goals.
Entry-Level Salaries and Career Progression for Veterinarians
While the debt burden is significant, veterinary medicine offers a stable and often rewarding career path. Entry-level salaries for general practitioners typically range from $80,000 to $110,000, varying by region, practice type (small animal, large animal, mixed), and specialization. With experience, specialization (e.g., surgery, internal medicine, ophthalmology), or ownership of a practice, income potential can rise significantly, often exceeding $150,000 to $200,000. It’s important for new graduates to have a realistic understanding of these figures and to factor them into their loan repayment and budgeting plans. A financial education includes understanding the market value of their skills and negotiating fair compensation.
Budgeting and Financial Planning for New DVMs
Beyond loan repayment, new DVMs need a robust personal finance framework. This includes creating and sticking to a budget, establishing an emergency fund (typically 3-6 months of living expenses), and beginning to save for retirement. Even with high student loan payments, it’s crucial to start building a financial safety net and investing early, leveraging the power of compound interest. Seeking advice from financial planners specializing in high-debt, high-income professionals can be invaluable, offering guidance on investment strategies, tax planning, and overall wealth accumulation. This ongoing financial literacy is arguably as important for long-term well-being as their clinical skills.
Investing in Your Future: Beyond the DVM Degree
The DVM degree is a foundational investment, but continuous financial and professional development ensures long-term career satisfaction and financial security. A truly comprehensive “education” for a veterinarian doesn’t stop with graduation; it evolves to encompass ongoing learning, strategic career moves, and astute financial growth.
Continuing Education as a Financial Investment
The field of veterinary medicine is constantly advancing, making continuing education (CE) not just a requirement for licensure, but a crucial investment in a veterinarian’s professional capital. Attending conferences, workshops, and pursuing additional certifications in specialized areas can enhance skills, improve patient outcomes, and significantly increase earning potential. These CE opportunities, while incurring costs (registration fees, travel, lost workdays), often yield a high return on investment through career advancement and higher compensation. From a financial perspective, viewing CE as an essential business expense that fuels professional growth is key.
Entrepreneurship in Veterinary Medicine: Opening Your Own Practice
For many veterinarians, the ultimate career goal is to own their own practice. This entrepreneurial path offers significant financial rewards but also comes with substantial risk and the need for a completely different set of financial and business acumen. Opening a practice requires capital for real estate, equipment, staff salaries, and operational expenses, often involving significant business loans. Successfully navigating this path demands a deep understanding of business finance, market analysis, risk management, and human resources—an entirely new layer of “education” beyond clinical medicine. For those considering this route, early financial planning and acquiring business management skills are paramount.
Planning for Retirement and Long-Term Financial Security
The journey through veterinary education and practice culminates in the need for long-term financial security, particularly retirement planning. Given the often delayed start to significant wealth accumulation due to student debt, veterinarians must be proactive in setting up retirement accounts (e.g., 401(k)s, IRAs), exploring real estate investments, and diversifying their financial portfolios. Understanding the principles of investment, asset allocation, and risk tolerance becomes an ongoing financial education. The DVM education sets the stage, but astute financial management throughout their career is what ultimately ensures a comfortable and secure future.
Financial Literacy: The Unsung Prerequisite for Veterinary Success
Ultimately, while the formal curriculum focuses on animal health, the “education you need to be a veterinarian” must fundamentally include robust financial literacy. It’s the invisible curriculum that underpins all other successes, enabling students to pursue their dreams without being overwhelmed by debt and allowing professionals to build stable, prosperous lives.
Essential Money Management Skills for Aspiring Vets
From the moment an aspiring vet decides on this career path, they need to cultivate strong personal finance habits. This includes diligent saving, understanding credit scores, managing personal budgets, and making informed decisions about small loans or credit card usage. These foundational skills, honed during undergraduate years, provide a crucial head start when confronting the much larger financial challenges of DVM education.
The Importance of Professional Financial Advice
Given the complexity of student loan debt, tax implications, and investment strategies unique to the veterinary profession, engaging with financial advisors early and throughout a veterinarian’s career is an invaluable investment. Professionals can help navigate repayment plans, structure investments for optimal growth, and plan for major life events like practice ownership or family planning, ensuring that financial decisions are always strategically aligned with long-term goals.

Building a Financial Safety Net
Life, even for a dedicated veterinarian, is unpredictable. Illness, unexpected expenses, or economic downturns can derail even the best-laid plans. Therefore, a critical aspect of financial education is building a robust emergency fund and considering appropriate insurance policies (disability, life, malpractice). This financial safety net provides peace of mind and resilience, allowing veterinarians to focus on their demanding profession without undue financial stress.
In conclusion, while the question “what education do you need to be a veterinarian?” typically evokes images of demanding science courses and intensive clinical rotations, a truly holistic answer must embrace the profound importance of financial education. From meticulously planning for the enormous costs of veterinary school to strategically managing post-graduation debt, building wealth, and preparing for future financial security, money management is an indispensable skill set. Mastering financial literacy is not merely a supplementary aspect of becoming a DVM; it is a core prerequisite for sustained success, well-being, and professional fulfillment in a career dedicated to the health of animals.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.