
The term “pensioner” often conjures images of leisure and a life free from the daily grind of work. While this vision holds a kernel of truth, the reality of what it means to be a pensioner is far more complex, especially from a financial perspective. At its core, a pensioner is an individual who receives a regular income, known as a pension, typically after ceasing full-time employment, often due to age or disability. This financial life stage marks a significant transition, moving from earned income to drawing on accumulated savings and public provisions. Understanding the financial implications of being a pensioner is crucial, not only for those nearing retirement but for anyone planning for their long-term financial security.
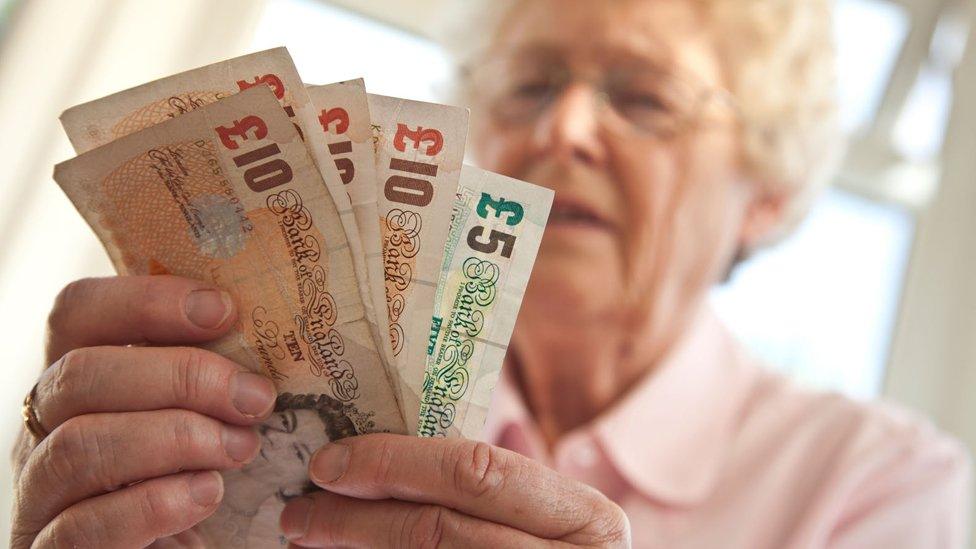
Beyond a simple dictionary definition, being a pensioner signifies entry into a new economic phase, where managing existing wealth, optimizing income streams, and navigating various financial instruments become paramount. It’s a period defined by the culmination of decades of financial planning (or lack thereof), with direct impacts on lifestyle, healthcare, and overall financial well-being. This article delves into the financial intricacies of being a pensioner, exploring the sources of pension income, the unique financial landscape of retirement, crucial planning strategies for future pensioners, and their evolving role in the broader economy.
The Core Definition: Beyond a Simple Label
To truly grasp what a pensioner means, we must move beyond the surface-level understanding and explore the financial mechanisms that underpin this status. It’s not merely an age marker but a state of financial reliance on previously accumulated funds or state provisions.
The Source of the Pension: Differentiating Government, Occupational, and Private Pensions
The income a pensioner receives can originate from several distinct sources, each with its own structure, eligibility criteria, and financial implications. Understanding these sources is fundamental to comprehending a pensioner’s financial stability.
-
State Pension (Government Pension): This is a regular payment from the government, provided to eligible individuals upon reaching a specific retirement age, often contingent on a sufficient national insurance or social security contribution history. For many, the state pension forms a crucial, albeit often insufficient, baseline income in retirement. Its purpose is to provide a safety net, ensuring a basic standard of living, but it rarely covers all the expenses associated with a comfortable retirement. Eligibility rules, payment amounts, and qualifying conditions vary significantly by country and are subject to governmental policy changes, making it essential for individuals to stay informed about their national system.
-
Occupational/Company Pensions: These pensions are provided by employers and are a cornerstone of many individuals’ retirement planning. They come in primarily two forms:
-
Defined Benefit (DB) Schemes: Once common, these promise a specific income level in retirement, often based on salary and years of service. The employer bears the investment risk, guaranteeing a predictable income stream. While attractive for their certainty, DB schemes are increasingly rare due to their high cost to employers.
-
Defined Contribution (DC) Schemes: These are now the prevailing type. Employers and employees contribute to a personal fund that is invested. The retirement income depends on the total amount contributed and the investment performance. The individual bears the investment risk, making financial literacy and active management crucial for maximizing retirement income. Many employers offer matching contributions, which can significantly boost savings and should be fully utilized.
-
-
Private Pensions/Personal Retirement Accounts: These are self-directed savings vehicles established by individuals outside of state or employer schemes. Examples include Individual Retirement Accounts (IRAs) and 401(k)s in the U.S., or Self-Invested Personal Pensions (SIPPs) and Personal Pensions in the UK. These allow individuals to save and invest for retirement with various tax advantages, such as tax-deferred growth or tax-free withdrawals in retirement, depending on the specific account type and jurisdiction. They offer flexibility in investment choices and contribution levels, making them powerful tools for supplementing other pension sources.
The Transition to Pensioner Status: The Concept of Retirement Age and Its Evolving Nature
Becoming a pensioner is intrinsically linked to the concept of retirement, which itself is undergoing significant evolution. The ‘retirement age’ is no longer a fixed, universal benchmark but a more fluid concept with financial ramifications.
-
Official Retirement Age: This refers to the age at which individuals become eligible to claim their full state pension and often, the age at which occupational pension schemes are designed to pay out. Globally, state pension ages are rising due to increased life expectancy and demographic pressures, compelling individuals to work longer or plan for a longer retirement period.
-
Early Retirement: Some individuals choose to become pensioners before the official retirement age. This often requires substantial personal savings and meticulous financial planning to bridge the income gap until state or occupational pensions become accessible. Financial independence movements highlight strategies for achieving early retirement through aggressive saving and investing. However, early retirement means a longer period of drawing down savings, potentially reducing the overall annual income available.
-
Phased Retirement: A growing trend, phased retirement allows individuals to gradually reduce their working hours while simultaneously beginning to draw a portion of their pension. This offers a softer transition from full-time work, provides continued income, and allows for a more gradual adjustment to pensioner life, both financially and psychologically. It can also help stretch retirement savings by deferring full pension drawdown.
The Financial Landscape of a Pensioner
Life as a pensioner introduces a distinct financial landscape. The steady, predictable paycheck from employment is replaced by a mix of pension incomes, investments, and potentially other benefits, requiring a different approach to budgeting, expense management, and income optimization.
Income Streams in Retirement: Understanding the Mosaic of a Pensioner’s Finances
A pensioner’s income is rarely monolithic; instead, it’s often a mosaic of various financial inflows, each contributing to their overall financial security.
-
Pension Income: As discussed, this is typically the primary income source, encompassing state, occupational, and private pensions. It’s crucial to understand how these pensions are taxed, as tax rules often differ for pension income compared to earned income. Some pensions may be inflation-linked, providing a valuable safeguard against the erosion of purchasing power, while others might offer fixed payments, necessitating careful consideration of future inflation.
-
Other Income Sources: Many pensioners supplement their core pension income through various means. This can include:
-
Part-time Work: Engaging in casual or part-time employment not only provides additional income but can also offer social engagement and purpose.
-
Investments: Income from dividends, interest on savings, or capital gains from selling assets can significantly bolster retirement finances. A well-diversified investment portfolio designed for income generation is a common strategy.
-
Rental Income: For those who own additional properties, rental income can be a stable and substantial source of funds.
-
Annuities: Purchased with a lump sum, annuities provide a guaranteed income stream for a set period or for life, offering peace of mind but usually at the cost of flexibility.
-
-
Social Benefits: Depending on the jurisdiction and individual circumstances, pensioners may be eligible for various state-provided benefits beyond the basic state pension. These could include housing benefits, council tax reductions, energy bill support (like winter fuel payments), or discounted public transport. These benefits act as a vital safety net and can significantly alleviate financial pressure, especially for those with lower pension incomes.
Managing Expenses and Budgeting: Life After Regular Paychecks
The shift from a regular salary to pension income necessitates a revised approach to managing expenses and budgeting. Without the potential for salary increases, optimizing outflows becomes critical.
-
Fixed vs. Variable Costs: Pensioners must meticulously categorize their expenses. Fixed costs like mortgage payments (if any), rent, utilities, and insurance premiums remain constant. Variable costs, such as groceries, leisure, travel, and healthcare, offer more scope for adjustment. A detailed budget helps in understanding where money is going and identifying areas for potential savings.
-
Healthcare Costs: For many pensioners, healthcare costs represent a significant and often unpredictable financial burden. While some countries have universal healthcare, others require substantial out-of-pocket expenses, insurance premiums, or co-pays. Planning for potential long-term care needs, which can be astronomically expensive, is a critical, albeit often overlooked, aspect of retirement financial planning.
-
Lifestyle Adjustments: Retirement often brings changes in lifestyle. While some anticipate increased spending on travel and hobbies, others might find themselves needing to downsize their homes, reduce discretionary spending, or seek more cost-effective forms of entertainment. Proactive financial planning can help align retirement income with desired lifestyle without unexpected compromises.
Financial Planning for the Future Pensioner
Becoming a pensioner isn’t a passive event; it’s the culmination of decades of financial choices. Effective planning is the most powerful tool for ensuring a comfortable and secure retirement.
Starting Early and Maximizing Contributions: The Power of Compound Interest
The single most impactful strategy for future pensioners is to start saving early and consistently contribute as much as possible to retirement accounts.
-
The Importance of Early Saving: Due to the power of compound interest, money saved in one’s 20s and 30s has far more time to grow than money saved later in life. Even small, regular contributions initiated early can accumulate into substantial sums over several decades. Illustrative examples often show that someone who saves diligently for 10 years early in their career can end up with more than someone who saves for 30 years starting later, due to the extended compounding period.
-
Employer Matching Schemes: Many employers offer to match a portion of employee contributions to occupational pension schemes. Failing to contribute enough to receive the full employer match is essentially leaving free money on the table, representing an immediate and guaranteed return on investment. Maximizing these contributions should be a top priority.
-
Regular Reviews: Financial circumstances change throughout life (e.g., salary increases, new dependents, changing goals). Regularly reviewing pension contributions and overall financial plans ensures they remain aligned with current goals and future aspirations. Adjusting contributions upwards during periods of higher income can significantly boost retirement savings.
Investment Strategies for Retirement Savings: Balancing Risk and Return
How retirement savings are invested plays a crucial role in their growth and sustainability. A thoughtful investment strategy balances risk tolerance with the desire for return.
-
Diversification: Spreading investments across different asset classes (e.g., stocks, bonds, real estate, cash) is essential to mitigate risk. A diversified portfolio is less susceptible to the poor performance of any single asset class.
-
Risk Tolerance: Investment strategies typically evolve closer to retirement. Younger individuals with a longer time horizon can generally afford to take on more investment risk, as they have time to recover from market downturns. As one approaches retirement, the strategy usually shifts towards more conservative investments to protect accumulated capital. This transition involves gradually reducing exposure to volatile assets like stocks and increasing allocation to more stable assets like bonds.
-
Professional Advice: Navigating complex investment markets and understanding tax implications can be daunting. Engaging a qualified financial advisor can provide personalized guidance, help create a suitable investment plan, and manage the portfolio to meet retirement goals.
Understanding Annuities and Drawdown Options: Converting Savings into Income
When individuals become pensioners, they face critical decisions about how to convert their accumulated pension savings into a sustainable income stream.
-
Annuities: An annuity is an insurance product that converts a lump sum into a guaranteed stream of income for a set period or for life. While they offer certainty and protection against outliving one’s savings, annuities typically involve giving up control over the capital and may not offer inflation protection unless specifically chosen. Various types exist, including immediate, deferred, fixed, and variable annuities, each with different features and risks.
-
Pension Drawdown (Flexi-Access Drawdown): This option allows pensioners to keep their pension pot invested and draw an income directly from it, offering flexibility but requiring careful management. The remaining fund stays invested, with the potential for further growth, but also subject to market fluctuations. This option carries the risk of outliving one’s savings if withdrawals are too high or investment returns are poor.
-
Lump Sums: Many pension schemes allow for a portion of the pension fund (often 25%) to be taken as a tax-free lump sum at retirement. Decisions about how to use this lump sum – whether to invest it, pay off debts, or fund a significant purchase – have substantial financial implications and require careful consideration of tax rules.
The Evolving Role of Pensioners in the Economy
Far from being a drag on the economy, pensioners represent a significant and increasingly powerful demographic, contributing in various ways while also facing unique economic challenges.
Consumer Power and Economic Contribution: Dispelling Myths
The stereotype of pensioners as financially inactive or dependent is increasingly outdated.
-
“Grey Pound/Dollar”: Older generations often possess significant disposable income, especially those who own their homes outright and have well-funded pensions. This “grey pound” or “grey dollar” fuels substantial consumer spending in sectors ranging from travel and leisure to healthcare and home improvements, making pensioners a vital economic force.
-
Volunteering and Mentorship: Many pensioners dedicate their time and experience to volunteering, contributing immense social value that is often overlooked in economic metrics. They also serve as mentors, passing on invaluable knowledge and skills to younger generations, both formally and informally.
-
Part-time Employment: As noted earlier, a growing number of pensioners choose to remain in the workforce part-time. This not only supplements their income but also helps fill skill gaps, particularly in industries facing labor shortages, contributing to overall economic productivity.

Addressing Challenges: Longevity and Inflation: Sustaining Financial Security
Despite their contributions, pensioners face distinct economic challenges, primarily stemming from increased longevity and the persistent threat of inflation.
-
Increased Life Expectancy: While a triumph of modern medicine, living longer means retirement savings must stretch over a longer period. This necessitates more robust financial planning, potentially higher savings rates, and a re-evaluation of withdrawal strategies to ensure funds don’t run out prematurely.
-
Inflation Risk: The erosion of purchasing power due to inflation is a significant concern for pensioners, especially those on fixed incomes. Over several decades of retirement, even low inflation rates can significantly reduce the real value of a pension. Planning for inflation through inflation-linked pensions or investments designed to outpace inflation is crucial.
-
Healthcare Costs in Later Life: As people age, the likelihood of needing significant medical care or long-term care increases. These costs can be exorbitant and represent one of the largest financial risks for pensioners. Planning for potential medical expenses, through insurance or dedicated savings, is an essential component of comprehensive retirement planning.
In conclusion, understanding “what does pensioner mean” extends far beyond a simple age categorization. It encapsulates a complex financial journey defined by various income streams, unique expenditure patterns, and critical planning decisions. Being a pensioner signifies a transition into a life stage where financial acumen, disciplined budgeting, and astute investment management become paramount for maintaining a desired lifestyle and ensuring long-term security. For future pensioners, the message is clear: proactive, informed financial planning, initiated early and regularly reviewed, is the cornerstone of a secure and fulfilling retirement. As the demographic landscape continues to shift, recognizing and supporting the financial realities of pensioners is not just a personal endeavor but an increasingly important societal and economic imperative.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.