
In the world of personal finance and business management, “dry mouth” is a metaphor for one of the most uncomfortable sensations an investor or entrepreneur can experience: a total lack of liquidity. Just as physical xerostomia makes it difficult to speak, swallow, or function comfortably, financial “dry mouth” occurs when your capital is locked away, your cash flow has slowed to a trickle, and your ability to respond to market opportunities is parched.
When you ask, “What can I take for dry mouth?” in a financial context, you are looking for more than just a quick fix; you are looking for a systemic remedy to hydrate your portfolio and ensure that your wealth remains fluid and functional. This article explores the strategies, “medications” (financial tools), and lifestyle changes (budgetary shifts) required to cure a dry financial throat and restore a healthy flow of capital.
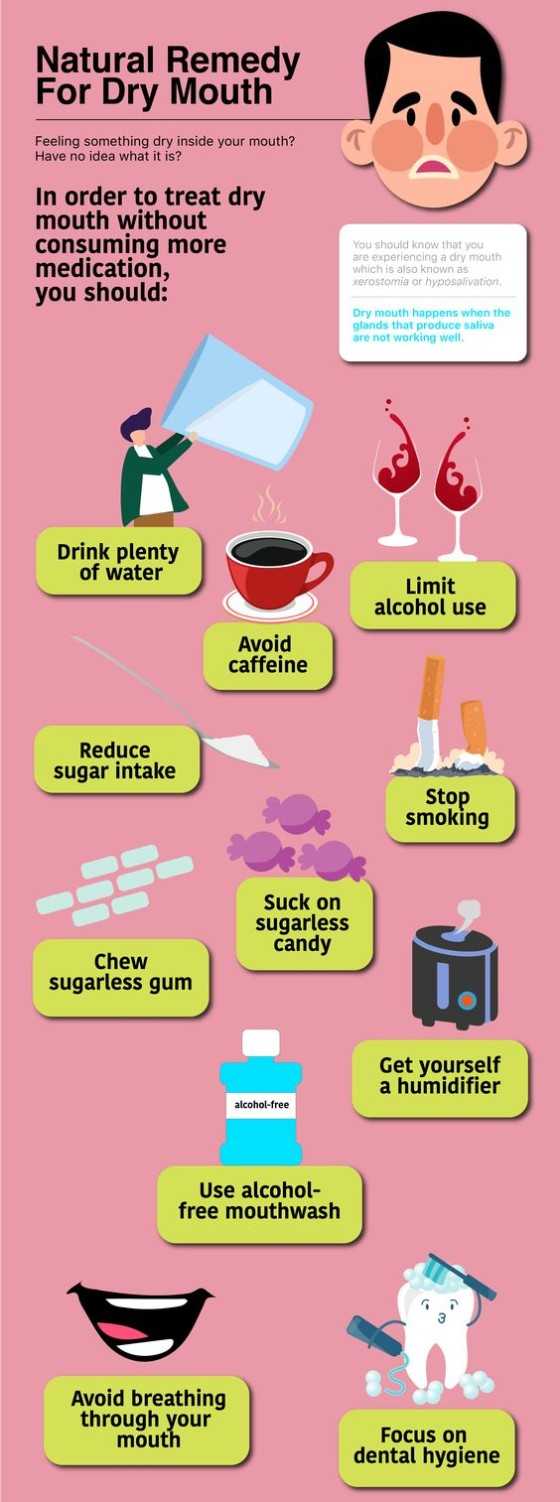
1. Identifying the “Dry Mouth” Symptoms in Your Portfolio
Before you can apply a remedy, you must diagnose the severity of your financial dehydration. Financial dry mouth often stems from over-leveraging, poor asset allocation, or a failure to account for the “evaporation” caused by inflation.
Recognizing the Sensation of Illiquidity
The most common symptom of financial dry mouth is the “stuck” feeling. You might see a high net worth on paper—perhaps through real estate holdings or locked retirement accounts—but find yourself struggling to cover immediate expenses or capital calls. This is a classic liquidity trap. Your assets are “dry” because they cannot be easily converted into cash without significant loss of value or heavy tax penalties.
The Impact of “Inflationary Heat” on Cash Reserves
Inflation acts like a desert sun on your savings. If your money is sitting in a traditional, low-interest checking account, the purchasing power is evaporating. This creates a psychological dry mouth: the realization that while the number in your account stays the same, its ability to provide “nourishment” (goods and services) is shrinking. Recognizing this early is the first step toward seeking a cure.
Assessing Your Debt-to-Income “Saliva” Levels
Healthy cash flow acts as the saliva of your financial life, lubricating transactions and allowing for smooth transitions between investments. If your debt obligations are consuming more than 30–40% of your take-home pay, your “saliva production” is dangerously low. You are essentially living in a state of chronic dehydration, where one small emergency could lead to a total financial shutdown.
2. Immediate “Hydration”: Short-term Solutions for Liquidity Gaps
If you are currently experiencing a liquidity crisis, you need immediate interventions. These are the financial equivalents of an electrolyte drink—designed to restore balance quickly so you can focus on long-term health.
Utilizing High-Yield Savings and Money Market Accounts
The first “supplement” anyone with financial dry mouth should take is a High-Yield Savings Account (HYSA) or a Money Market Account (MMA). Unlike traditional savings, these tools offer interest rates that can help mitigate the effects of inflation while keeping your money 100% liquid. In a high-interest-rate environment, these accounts serve as a primary source of hydration, ensuring that your emergency fund isn’t just sitting idle but is actively working to maintain its volume.
Liquidating Non-Performing “Dry” Assets
Look through your portfolio for “dead weight.” These are investments that aren’t yielding a return and are tying up capital that could be better used elsewhere. Whether it’s a piece of equipment in a business that no longer serves a purpose or a stock that has been underperforming for years with no signs of recovery, selling these assets provides an immediate “sip of water” to your cash reserves.
Optimizing Your Credit Lines as a Temporary Reservoir
While debt is often the cause of financial dryness, a well-managed line of credit can serve as a temporary reservoir. A Home Equity Line of Credit (HELOC) or a business line of credit provides a safety net that allows you to bridge gaps in cash flow without having to sell off long-term investments at an inopportune time. However, this should be treated like a specialized medication: use it sparingly and only under professional observation to avoid “side effects” like increased debt burdens.
3. Long-term “Saliva Production”: Building Sustainable Passive Income
A permanent cure for financial dry mouth requires building systems that generate “saliva” (cash flow) automatically. You want a portfolio that produces its own moisture, regardless of whether you are actively working or not.
The Power of Dividend-Growth Investing
One of the most effective “prescriptions” for chronic financial dryness is dividend-growth investing. By owning shares in companies that regularly pay out a portion of their profits to shareholders, you create a recurring stream of income. Over time, as you reinvest these dividends, the “hydration” levels in your portfolio grow exponentially. This ensures that even during a market downturn, you have cash flowing into your accounts, preventing that parched feeling that comes with a stagnant market.
Creating Digital “Aqueducts” via Side Hustles
In the modern economy, “what you can take” for a dry income is often a new project. Digital assets—such as online courses, e-books, or automated e-commerce stores—act as aqueducts, funneling wealth from the global market directly into your bank account. These side hustles provide a secondary source of moisture that protects you if your primary “well” (your main job or business) ever runs dry.
Real Estate and the Rental Income Stream
For many, the ultimate cure for financial dry mouth is real estate. While the entry cost is high and the asset itself is illiquid, the rental income it generates is highly “hydrating.” Monthly rent checks provide a consistent flow of cash that can cover living expenses or be funneled into other investments. When structured correctly, real estate provides both the “bulk” of a solid asset and the “fluidity” of regular cash flow.
4. Preventing Future Dehydration: Strategic Financial Planning
Once you have restored your liquidity, the goal is to prevent the “dryness” from returning. This requires a disciplined approach to financial hygiene and a proactive strategy for asset management.
Diversification: The Multi-Source Water Strategy
Relying on a single source of income is the fastest way to suffer from financial dry mouth. If that one source fails, you are immediately in a crisis. True financial health comes from diversification. You should have “water” coming from various sources: capital gains, dividends, interest, and earned income. This multi-source strategy ensures that if one well runs dry due to industry shifts or economic downturns, the others can sustain you.
Establishing a “Hydration Ratio” (The Emergency Fund)
A professional approach to money management requires a strict “hydration ratio.” This is the amount of liquid cash you keep on hand relative to your monthly expenses. Most experts recommend keeping 3 to 6 months of expenses in a highly liquid state. This is your “canteen” for the desert. It ensures that no matter how dry the economic landscape becomes, you have enough to survive until you reach the next oasis.
Regular Financial “Check-ups” and Rebalancing
Market conditions change, and so should your strategy. A portfolio that was perfectly hydrated two years ago might be parched today due to shifting interest rates or tax law changes. “What you take” for your finances should be reviewed at least twice a year. Rebalancing involves selling some of your high-performing (but perhaps over-extended) assets to replenish your cash reserves or to invest in undervalued areas. This keeps the cycle of liquidity moving and prevents any one area of your financial life from becoming too “stiff” or “dry.”

Conclusion: Living with a Well-Hydrated Portfolio
When you ask “what can I take for dry mouth” in the realm of money, the answer is a combination of immediate liquidity tools and long-term cash-flow systems. Financial dryness is not just a nuisance; it is a risk factor that can lead to missed opportunities and increased stress.
By treating your cash flow with the same importance as your net worth, you ensure that your financial life remains vibrant and flexible. Use high-yield accounts for immediate relief, build dividend and rental streams for long-term health, and always maintain an emergency reservoir. With these strategies in place, you can stop worrying about the “dry spells” of the economy and focus on the growth and prosperity of your financial future. A well-hydrated portfolio doesn’t just survive the heat of the market—it thrives in it.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.