
For the majority of individuals, a vehicle represents the second-largest financial commitment they will make, surpassed only by the purchase of a home. Yet, unlike real estate, which historically appreciates over time, a car is a primary example of a depreciating asset. Understanding the precise value of your vehicle is not merely a matter of curiosity; it is a fundamental component of proactive personal finance. Whether you are looking to sell, trade-in, optimize your insurance premiums, or simply track your net worth with accuracy, mastering the art of vehicle valuation is an essential financial skill.

Determining a car’s worth in the modern economy requires moving beyond guesswork and gut feelings. It involves a synthesis of real-time market data, an objective assessment of condition, and an understanding of the economic variables that drive supply and demand.
The Financial Importance of Accurate Vehicle Valuation
Before diving into the tools and metrics of valuation, it is critical to understand why this number matters within the context of your broader financial portfolio. A vehicle is a liquid asset, but its liquidity is highly dependent on your understanding of its market position.
Depreciation: The Silent Budget Killer
Depreciation is the difference between what you paid for a vehicle and what you can get for it when you sell it. On average, a new car loses approximately 20% of its value in the first year and roughly 15% each year thereafter for the first five years. By accurately tracking your car’s value, you can visualize this downward slope. From a financial planning perspective, knowing your car’s value allows you to calculate the total cost of ownership (TCO). This includes not just your monthly loan payment and fuel, but the “invisible” cost of losing equity every month.
Equity and Loan-to-Value Ratios
For those who have financed their vehicles, the most critical reason to know its value is to monitor equity. “Negative equity,” often referred to as being “underwater” or “upside down” on a loan, occurs when the balance of the auto loan exceeds the current market value of the car. This is a precarious financial position. If the car is totaled in an accident or if you are forced to sell it due to a financial emergency, you will owe the lender the difference out of pocket. By staying informed on your car’s value, you can make strategic decisions, such as making extra principal payments to reach a “break-even” point faster.
Essential Tools and Methods for Price Discovery
In the digital age, consumers have access to the same high-level data that was once reserved for dealerships and insurance adjusters. Utilizing these resources effectively is the first step in a professional valuation.
Leveraging Valuation Databases
There are several gold-standard databases that provide a baseline for vehicle pricing. However, they serve different purposes:
-
Kelley Blue Book (KBB): Perhaps the most recognized name in the industry, KBB provides “Fair Purchase Price” and “Trade-In Value.” It is excellent for getting a consumer-centric view of the market, though it can sometimes lean toward optimistic pricing for private sales.
-
NADAguides (J.D. Power): This tool is frequently used by credit unions and banks to determine loan values. NADA values tend to reflect wholesale and retail trends more closely aligned with what a dealership might offer.
-
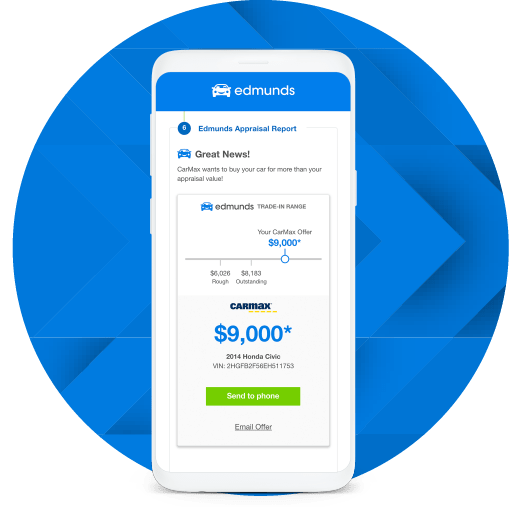
Edmunds: Known for its “True Market Value” (TMV) tool, Edmunds provides a transparent look at what others in your specific geographic area are actually paying for similar vehicles.
When using these tools, it is vital to look at the “Trade-In Value” versus the “Private Party Value.” The trade-in value is what a dealer will pay you—typically lower because the dealer needs to leave room for profit and reconditioning costs. The private party value is what you might expect to receive if you sell the car to another individual.
Real-Time Market Analysis through Local Listings
While databases provide a theoretical value based on historical data, local listings provide the actual market reality. Markets are highly localized. A four-wheel-drive SUV is worth significantly more in a mountainous, snowy climate than it is in a coastal city.
To get a “real-world” valuation, search platforms like Autotrader, Cars.com, and Facebook Marketplace for vehicles that match your year, make, model, trim, and mileage within a 50-mile radius. Take note of the “Ask Price.” Keep in mind that the listed price is a starting point for negotiations; the actual sale price is likely 5% to 10% lower. This “comparative market analysis” is the same method used in real estate and provides the most accurate snapshot of what a buyer is willing to pay right now.
Factors that Influence Market Value Beyond the Basics
Two cars of the exact same year and model can have valuations that differ by thousands of dollars. The nuance lies in the details that algorithms often struggle to capture perfectly.
Mechanical Integrity and Service Records
From a financial standpoint, a car is a collection of systems with finite lifespans. A vehicle with a documented service history is worth a premium. If you can prove that the oil was changed every 5,000 miles, the timing belt was replaced on schedule, and the tires are relatively new, you are not just selling a car; you are selling “reduced risk” to the next owner. Conversely, deferred maintenance is a direct liability that must be subtracted from the car’s “Good” or “Excellent” book value.
Cosmetic Condition and Trim Levels
The “curb appeal” of a vehicle has a psychological impact on buyers that translates into dollar value. Minor dents, scratched upholstery, or a “smoker’s car” odor can decrease a car’s value by 15% or more. Furthermore, trim levels and optional packages play a massive role. A “Base” model versus a “Limited” or “Platinum” trim can mean a difference of $5,000 or more on the secondary market. When valuing your car, ensure you are selecting the exact trim level and including high-value features like sunroofs, upgraded audio systems, or advanced safety tech.
Regional Economics and Seasonal Demand
Macroeconomic factors often dictate vehicle worth. During periods of high gas prices, fuel-efficient hybrids and electric vehicles see a surge in valuation, while large, gas-guzzling SUVs depreciate faster. Seasonality also plays a role. Convertibles are worth more in the spring and summer, while all-wheel-drive vehicles see a price hike in late autumn. Understanding these cycles allows you to time your exit from an asset to maximize your return.
Strategies for Maximizing Your Vehicle’s Resale Potential
Once you have identified the current value, the next financial step is determining how to capture as much of that value as possible. This is where strategic reconditioning and sales channel selection come into play.
Strategic Maintenance and Reconditioning
Not all repairs offer a positive return on investment (ROI). If your car is worth $10,000 and it needs a $3,000 transmission repair, you are unlikely to recoup that full $3,000 in the sale price. However, “low-hanging fruit” like professional detailing, fixing a cracked windshield (often covered by insurance), or replacing a burnt-out headlight can yield a 2x or 3x return on the cost by moving the car from the “Fair” category to “Good” or “Excellent.” In the eyes of a buyer, a clean, well-presented car suggests a well-cared-for engine.
Private Sale vs. Trade-In: The Financial Trade-Off
This is the most critical decision in the valuation process. Selling your car privately to another individual will almost always net you the highest dollar amount—often 15% to 25% more than a dealer trade-in offer. However, this comes with the “cost” of your time, the effort of marketing, and the risks of dealing with strangers.
A trade-in is a “convenience tax.” You accept a lower price in exchange for a seamless transaction. From a tax perspective, however, many states only charge sales tax on the “price difference” between your new car and your trade-in. For example, if you buy a $30,000 car and trade in your old car for $10,000, you only pay sales tax on $20,000. Depending on your local tax rate, this “tax shield” can bridge a significant portion of the gap between a trade-in offer and a private sale price.
Incorporating Vehicle Value into Your Broader Financial Plan
A car should not be viewed in isolation; it is a moving part of your overall wealth management strategy.
When to Hold and When to Fold
There is a mathematical “sweet spot” for selling a vehicle. Typically, this is before a major high-cost maintenance milestone (like 100,000 miles) or right before a new model generation is released, which instantly makes the previous generation look dated and reduces its value. If the annual cost of repairs begins to approach 50% of the car’s total value, it is often more financially sound to liquidate the asset and move into a more reliable vehicle, even if it requires a new loan.

Insurance Adjustments and Total Loss
If you discover your car is worth significantly less than it was two years ago, you may be overpaying for insurance. For older vehicles whose value has dropped below a certain threshold (e.g., $5,000), it may make financial sense to drop “collision” and “comprehensive” coverage and carry only “liability.” The premiums you save over a year or two could potentially equal a significant portion of the car’s remaining value.
Additionally, knowing your car’s value is your only defense if the vehicle is totaled. Insurance companies will offer you the “Actual Cash Value” (ACV). If you have done your research and have data to prove your car was worth more than their offer due to its condition or local market rarity, you can negotiate a higher settlement.
By treating your vehicle as a serious financial asset—valuing it regularly, maintaining it strategically, and understanding the market forces that affect its worth—you move from being a passive consumer to an active manager of your personal wealth. In the world of finance, knowledge of an asset’s true value is the ultimate leverage.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.