
Joining a financial institution is often a straightforward process, but for some, the prestige and specific membership requirements of certain credit unions can make it feel like an exclusive club. Navy Federal Credit Union (NFCU) is one such institution, renowned for its commitment to military members, veterans, and their families, offering a suite of financial products and services tailored to their unique needs. For many, becoming a member of Navy Federal isn’t just about opening an account; it’s about gaining access to a financial partner that understands their life and provides unparalleled support.
This comprehensive guide aims to demystify the process of joining Navy Federal Credit Union. We’ll delve into what makes NFCU a preferred choice for millions, explore the critical eligibility criteria, walk you through the application steps, and highlight how to maximize the financial advantages of your membership. Whether you’re an active-duty service member, a veteran, a DoD civilian, or a family member, understanding the path to membership is the first step toward unlocking a world of financial opportunities.
Understanding Navy Federal Credit Union’s Unique Value
Before diving into the “how-to,” it’s essential to grasp why so many aspire to join Navy Federal. Unlike traditional banks, credit unions operate on a not-for-profit model, meaning their profits are returned to members in the form of lower fees, better interest rates, and improved services. Navy Federal epitomizes this model, offering a distinct financial environment built on trust, service, and community.
Credit Union vs. Traditional Bank: The Member-Centric Difference
The fundamental difference lies in ownership and philosophy. Banks are typically for-profit corporations owned by shareholders, whose primary goal is to maximize profits. Credit unions, conversely, are member-owned cooperatives. When you join NFCU, you become an owner with a say in its direction (through voting rights for the board of directors). This structure translates into a focus on member well-being rather than shareholder returns. Members often benefit from more competitive loan rates (auto, mortgage, personal), higher savings rates, and significantly lower (or no) fees on various services. For individuals and families managing their personal finances, these differences can lead to substantial savings and enhanced financial growth over time.
Comprehensive Financial Services for Every Life Stage
Navy Federal isn’t just a place to deposit your paycheck. It’s a full-service financial institution designed to support members through every stage of their financial journey. From basic checking and savings accounts to complex investment solutions, NFCU offers a robust portfolio. They provide a wide array of lending products, including mortgages tailored for military families, auto loans with competitive rates, and personal loans designed to meet diverse needs. Their credit card offerings are known for competitive APRs and rewards programs. Furthermore, NFCU provides financial planning resources, wealth management services, and insurance products, making it a one-stop shop for comprehensive financial management. This breadth of services, combined with their member-first approach, helps individuals and families build, manage, and protect their wealth effectively.
The Commitment to Military and Their Families
At its core, Navy Federal Credit Union was founded to serve the financial needs of the armed forces. This deep-seated commitment translates into an understanding of military life that most commercial banks simply cannot match. They appreciate the challenges of deployments, permanent change of station (PCS) moves, and the unique pay structures. Their financial products often feature military-specific benefits, such as waived ATM fees worldwide, early access to military pay, and specialized financial counseling. This unwavering dedication to those who serve, and their loved ones, is a cornerstone of NFCU’s identity and a primary reason for its revered status within the military community.
Eligibility: Who Can Join Navy Federal?
The most crucial aspect of getting into Navy Federal Credit Union is meeting their specific eligibility requirements. While their reach is extensive, it is not universal. Membership is primarily dictated by a direct or familial connection to the armed forces or the Department of Defense.
Direct Military Affiliation (Active Duty, Reserves, Veterans, Retirees)
The core of Navy Federal’s membership lies with those who have served or are currently serving in the U.S. Armed Forces. This includes:
-
Active Duty: Members of the Army, Marine Corps, Navy, Air Force, Coast Guard, Space Force, and National Guard.
-
Reserves: Individuals serving in the Reserve components of any branch.
-
Veterans: Those who have previously served in any branch of the armed forces.
-
Retirees: Military retirees from any branch.
-
Officer Candidates: Individuals in Officer Candidate programs (e.g., ROTC, Service Academies).
-
Department of Defense (DoD) Civilians: Civilian employees of the DoD who are paid directly by the U.S. government. This also includes U.S. government employees assigned to DoD installations, and DoD contractors assigned to U.S. government installations.
Proof of service or employment is required during the application process. This could include a military ID, DD-214, or other official documentation verifying your status.
Family Membership: Extending the Reach
One of the most powerful aspects of NFCU eligibility is its ability to extend to family members. If you don’t directly qualify through military service or DoD employment, you might be eligible if a qualifying family member is already a member or is eligible to join. This includes:
-
Spouses: Wives or husbands of eligible service members or DoD civilians.
-
Parents: Mothers or fathers of eligible service members or DoD civilians.
-
Grandparents: Grandparents of eligible service members or DoD civilians.
-
Siblings: Brothers or sisters of eligible service members or DoD civilians.
-
Children: Sons or daughters (including adopted and stepchildren) of eligible service members or DoD civilians.
-
Grandchildren: Grandchildren of eligible service members or DoD civilians.
-
Household Members: This is a less common but sometimes possible route; individuals who permanently reside in the same household as a qualifying member. This typically requires more stringent verification.
For family members, you will need to provide documentation proving your relationship to the eligible individual (e.g., birth certificates, marriage licenses). It’s important to note that the eligible family member does not necessarily need to be an existing NFCU member for you to qualify; they just need to be eligible themselves. However, it’s often easiest if they are already a member and can sponsor you.
The Application Process: A Step-by-Step Guide
Once you’ve confirmed your eligibility, the application process to join Navy Federal Credit Union is designed to be straightforward, whether you prefer to apply online, over the phone, or in person.
Gathering Necessary Documentation
Preparation is key to a smooth application. Before you begin, gather the following essential documents and information:
-
Proof of Eligibility: This is paramount.
-
Military: Valid military ID, DD-214, Leave and Earnings Statement (LES), or other official military documents.
-
DoD Civilian: DoD ID, pay stub, or official letter from your employer.
-
Family: Birth certificate (to prove parent/child relationship), marriage certificate (for spouses), or other legal documents establishing your relationship to the qualifying member.
-
-
Government-Issued ID: A valid driver’s license, state ID, or passport.
-
Social Security Number (SSN): For identity verification and credit reporting.
-
Current Address Information: Including any previous addresses if you’ve moved recently.
-
Contact Information: Phone number and email address.
-
Initial Deposit: You’ll need to make a minimum initial deposit into a savings account to establish your membership. This is typically $5, signifying your “share” in the credit union.
Having these items readily available will expedite your application significantly.
Online, Phone, or Branch: Choosing Your Application Method
Navy Federal offers multiple convenient ways to apply for membership:
-
Online: This is often the quickest and most preferred method for many. Visit the official Navy Federal Credit Union website and navigate to the “Become a Member” or “Join Now” section. The online application guides you step-by-step, allowing you to upload documents digitally.
-
By Phone: You can call Navy Federal’s member service representatives, who can walk you through the application over the phone. This can be helpful if you have specific questions or prefer guided assistance.
-
In Person: If you live near one of NFCU’s many branches, you can visit to apply in person. This allows for face-to-face interaction, and branch employees can help verify your documents and answer any questions on the spot. This option can be particularly reassuring for those who prefer personal assistance.
Regardless of the method, the core information and documentation requirements remain the same.
Initial Deposit and Account Setup
To formally establish your membership, Navy Federal requires a minimum deposit into a savings account. This is usually a symbolic $5, which makes you a “shareholder” and owner of the credit union. Once this deposit is made, your membership is active. At this point, you can then open additional accounts, such as checking accounts, apply for credit cards, or explore loan options. The process is typically seamless, with your initial membership savings account acting as the foundation for all your future financial interactions with NFCU.
Understanding Membership Tiers and Account Options
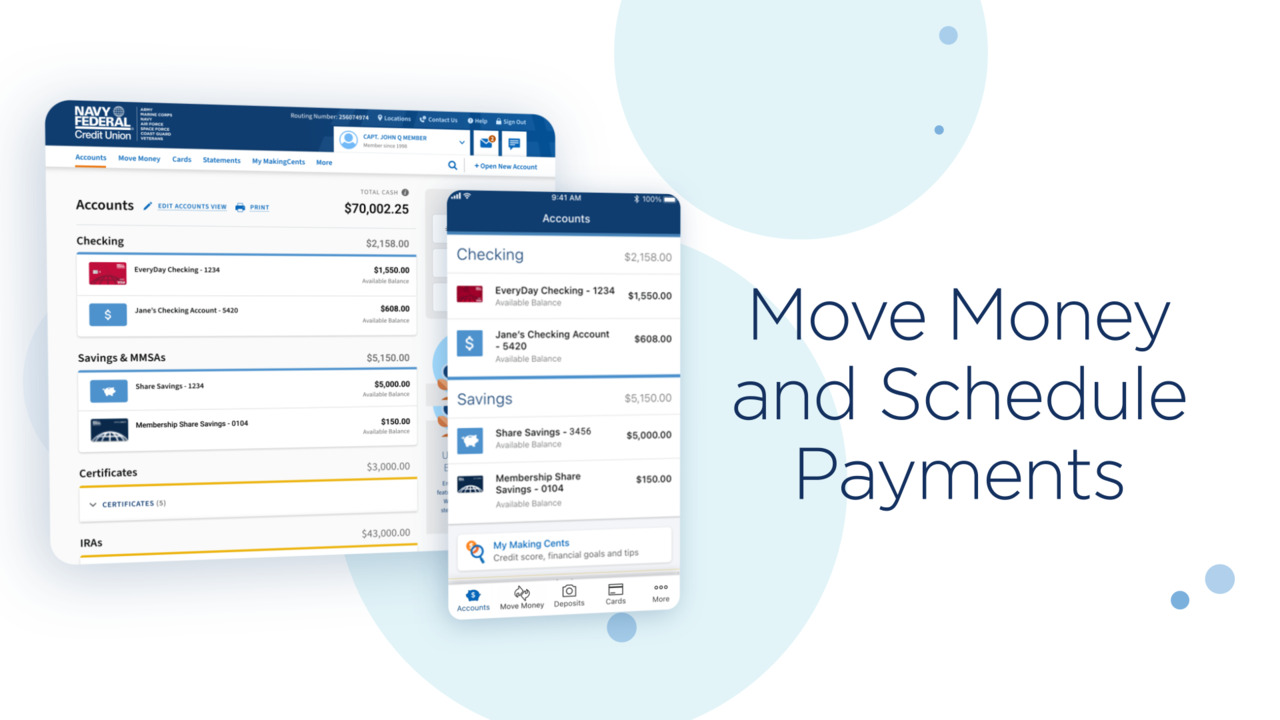
While there aren’t formal “membership tiers” in the traditional sense, your financial relationship with NFCU can deepen over time. New members typically start with a basic savings account. From there, you can explore various options:
-
Checking Accounts: Often come with no monthly fees, direct deposit, and access to a vast ATM network.
-
Savings and Money Market Accounts: For building emergency funds or saving for specific goals, often with competitive interest rates.
-
Certificates of Deposit (CDs): For higher, fixed returns on your savings over a set period.
-
Loan Products: Auto loans, mortgages, personal loans, student loans, and more, usually with rates favorable to members.
-
Credit Cards: A range of cards catering to different spending habits and credit profiles, often with rewards and competitive APRs.
It’s wise to discuss your financial goals with a Navy Federal representative to ensure you’re setting up the accounts that best serve your needs.
Maximizing Your Navy Federal Membership
Joining Navy Federal is just the beginning. The true value comes from actively utilizing the financial tools and services available to members. By leveraging their offerings, you can significantly enhance your personal finance strategy.
Leveraging Exclusive Rates and Loan Products
One of the most compelling reasons to join NFCU is access to their highly competitive loan rates. Whether you’re purchasing a car, buying a home, or consolidating debt, Navy Federal often provides rates that are more favorable than traditional banks.
-
Auto Loans: Known for offering some of the lowest auto loan rates in the industry, often with flexible terms.
-
Mortgages: Special programs and guidance for military homebuyers, including VA loans, with dedicated loan officers who understand the unique aspects of military relocations and pay.
-
Personal Loans: Competitive rates for personal expenses, debt consolidation, or unexpected costs, often with quick approval processes.
Regularly comparing NFCU’s rates with other financial institutions for any borrowing needs can lead to significant savings over the life of a loan.
Utilizing Their Credit Card Portfolio
Navy Federal offers a diverse range of credit cards designed for various financial profiles and spending habits. From cashback rewards to low-interest options and cards designed for building credit, there’s likely a product to suit your needs.
-
Rewards Cards: Earn points or cashback on everyday purchases, redeemable for travel, gift cards, or statement credits.
-
Low APR Cards: Ideal for those who occasionally carry a balance, offering lower interest rates to minimize costs.
-
Secured Cards: For members looking to build or rebuild their credit history, requiring a security deposit but providing a path to better credit.
Many cards also come with no annual fees and robust fraud protection, making them valuable tools for managing daily expenses and improving your credit score.
Exploring Savings and Investment Opportunities
Beyond checking and basic savings, Navy Federal provides avenues for growing your wealth. Their savings accounts and money market accounts often yield better interest rates than traditional banks, helping your money work harder for you. For more strategic savings, their Certificates of Deposit (CDs) offer guaranteed returns for fixed terms.
For those looking to invest, NFCU also offers wealth management services through Navy Federal Investment Services. This includes access to financial advisors, retirement planning (IRAs), college savings plans (529s), mutual funds, annuities, and other investment products. These services are invaluable for long-term financial planning, ensuring you’re preparing adequately for retirement, education, or other significant life goals.
Digital Banking and Member Support
In today’s fast-paced world, convenient access to your money is critical. Navy Federal excels in its digital offerings:
-
Mobile App: A highly rated app for managing accounts on the go, including mobile check deposits, bill pay, transfers, and budgeting tools.
-
Online Banking: Comprehensive web portal for all your financial needs, accessible 24/7.
-
ATMs and Branches: Extensive network of ATMs and branches, with many offering personalized service.
-
24/7 Member Service: Access to dedicated member service representatives by phone, ensuring help is always available, especially crucial for members who are deployed or living abroad.
These digital tools and robust support infrastructure make managing your finances with NFCU efficient and stress-free, regardless of where you are in the world.
Addressing Common Questions and Considerations
While Navy Federal offers immense value, it’s important to consider if it’s the right fit for your unique financial situation and what alternatives exist if you don’t qualify.
Is NFCU Right for Everyone? (Pros and Cons)
For those eligible, the benefits of Navy Federal Credit Union are substantial: competitive rates, low fees, excellent customer service, and a deep understanding of the military lifestyle. However, no financial institution is a perfect fit for absolutely everyone.
Pros:
-
Member-focused: Lower fees, better rates on loans and savings.
-
Comprehensive Services: All financial needs under one roof.
-
Military-centric: Tailored products and services for service members and their families.
-
Strong Digital Presence: Excellent mobile app and online banking.
-
Global Access: Support for members worldwide.
Cons:
-
Eligibility Restrictions: Not everyone can join, which can be frustrating for those without a military connection.
-
Limited Physical Branches: While extensive, their branch network isn’t as vast as some mega-banks, though digital services mitigate this.
-
Potentially Slower Technology Adoption: As a credit union, sometimes their technology upgrades might lag behind cutting-edge fintech companies, though they generally offer a very strong digital experience.
For the vast majority of eligible individuals, the pros significantly outweigh the cons, making NFCU a highly recommended financial partner.
What to Do if You Don’t Qualify (Alternative Credit Unions)
If you find that you don’t meet Navy Federal’s eligibility criteria, don’t despair. The credit union movement is vast and diverse. There are thousands of other credit unions across the United States, many of which also offer excellent rates and member-focused services.
-
Community Credit Unions: Many credit unions serve specific communities (e.g., based on where you live, work, or worship).
-
Employer-Sponsored Credit Unions: Some employers sponsor credit unions for their employees.
-
Other Affinity Credit Unions: You might qualify based on membership in a specific organization, profession, or even certain geographic areas.
Websites like MyCreditUnion.gov or CUNA (Credit Union National Association) can help you locate credit unions for which you might be eligible. While you might not get the military-specific perks of NFCU, you can still enjoy the general benefits of credit union membership.
Maintaining Your Membership
Once you’re a member of Navy Federal, your membership is generally for life, even if your military status or family affiliation changes (e.g., leaving the service, divorce). As long as you maintain your initial $5 savings deposit, you typically remain a member in good standing. This “once a member, always a member” policy is another significant advantage, offering long-term financial stability and access to their services.

Conclusion
Getting into Navy Federal Credit Union is a structured process that hinges on eligibility, primarily through military service, DoD civilian employment, or a direct family connection. For those who qualify, becoming a member opens the door to a financial institution that consistently prioritizes its members, offering competitive rates, low fees, comprehensive services, and a deep understanding of the unique financial landscape faced by service members and their families.
By understanding the eligibility requirements, preparing your documentation, and following the simple application steps, you can confidently join the ranks of millions who have chosen Navy Federal as their trusted financial partner. Taking advantage of their specialized loan products, credit cards, savings opportunities, and robust digital banking tools can significantly enhance your financial well-being and set you on a path to achieving your personal and professional financial goals. Joining NFCU isn’t just about opening an account; it’s about becoming part of a community committed to your financial success.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.